


Is a Mortgage for Life Right for Your Retirement Plan?
If you are approaching retirement with a home loan, a mortgage for life can sound either practical or unsettling. The real question is not whether debt in retirement is automatically good or bad. It is whether the payment, loan structure and purpose support the retirement you want without shrinking your safety margin.
Some households enter retirement determined to pay off the house as quickly as possible. Others prefer to keep a manageable mortgage so they can preserve cash, avoid selling investments at the wrong time or stay in a home that fits their life. Both choices can be reasonable, depending on income, health, taxes, risk tolerance and family goals.
This guide breaks down what the phrase may mean, how it can fit into a retirement plan and when another option may be safer.
What a mortgage for life can mean in retirement
First, a quick definition matters. The phrase is not one standardized product in the US mortgage market. Some people use it to describe any home loan they expect to carry deep into retirement. Others use it informally when discussing a reverse mortgage, a refinance that extends the payoff timeline or a strategy of never rushing to eliminate mortgage debt.
Before treating a mortgage for life as a retirement strategy, separate these possibilities:
| Common meaning | How it works | Retirement planning issue |
|---|---|---|
| Keeping a traditional mortgage | You continue paying principal and interest during retirement | The monthly payment must fit fixed or semi-fixed income |
| Refinancing into a longer term | You replace the current loan, often to lower the monthly payment or access equity | Closing costs and total lifetime interest may rise |
| Using a reverse mortgage | Eligible homeowners borrow against equity, often without required monthly principal and interest payments | Taxes, insurance, maintenance and long-term equity impact still matter |
For federally insured Home Equity Conversion Mortgages, the Consumer Financial Protection Bureau explains that borrowers generally must be at least 62, live in the home as a primary residence and keep up with property charges. That makes the details very different from a normal refinance.
Why some retirees choose to keep a mortgage
Used carefully, a mortgage for life can support retirement cash flow because it avoids concentrating too much wealth in home equity. A paid-off home can feel secure, but equity does not pay medical bills, replace a roof or cover a family emergency unless you borrow against it, sell the home or use another liquidity source.
Cash flow and liquidity
Keeping a predictable mortgage payment may allow a retiree to hold onto savings instead of using a large lump sum to pay off the loan. This can be useful when retirement income comes from Social Security, pensions, required minimum distributions, brokerage accounts or part-time work that may change over time.
The strongest case usually exists when the payment is stable, the rate is manageable and the borrower has enough cash reserves. A fixed-rate mortgage can provide more certainty than an adjustable loan, although taxes, insurance, HOA dues and maintenance can still increase.
Investment and tax considerations
Some retirees consider keeping a loan if they believe their invested assets may be more valuable than the interest saved by paying off the home. That comparison should be made carefully because investment returns are not guaranteed, especially in the early years of retirement when sequence-of-return risk matters.
Mortgage interest may be deductible for some homeowners, but only if they itemize and meet IRS rules. Many retirees do not benefit from the deduction. A tax professional can help you compare the after-tax cost of the mortgage with the after-tax value of keeping assets invested.
Where the strategy can go wrong
The main danger of a mortgage for life is not simply having debt. It is having debt that stays in place after income becomes less flexible. During working years, a raise, bonus or job change can help absorb a payment that feels tight. In retirement, the adjustment options can be narrower.
A mortgage that looked affordable at 60 may feel very different at 75 if insurance premiums rise, property taxes increase, healthcare costs grow or a spouse dies and household income changes. The problem is usually not one expense by itself. It is the accumulation of several fixed costs at the same time.
| Risk | Why it matters | Planning response |
|---|---|---|
| Payment strain | A mortgage can crowd out healthcare, travel, caregiving or repairs | Test the full housing payment against conservative retirement income |
| Reduced flexibility | Less free cash can make it harder to handle emergencies | Keep an emergency fund separate from home equity |
| More lifetime interest | Extending a loan can lower payments but increase total cost | Compare monthly relief with long-term cost |
| Equity erosion | Cash-out loans and reverse mortgages can reduce future home equity | Discuss downsizing, heirs and care needs before borrowing |
| Rate uncertainty | Adjustable loans can reset when income is fixed | Understand caps, reset dates and refinance alternatives |
How to test the numbers before deciding
A retirement mortgage decision should start with household cash flow, not just the interest rate. The best loan on paper can still be the wrong fit if it creates stress every month or leaves no room for repairs, health expenses and market downturns.
A mortgage for life should survive more than the best-case version of retirement. Run the numbers using realistic income, then repeat the exercise with a lower investment withdrawal, higher insurance premium or major home repair.
| Planning question | What to calculate | Why it matters |
|---|---|---|
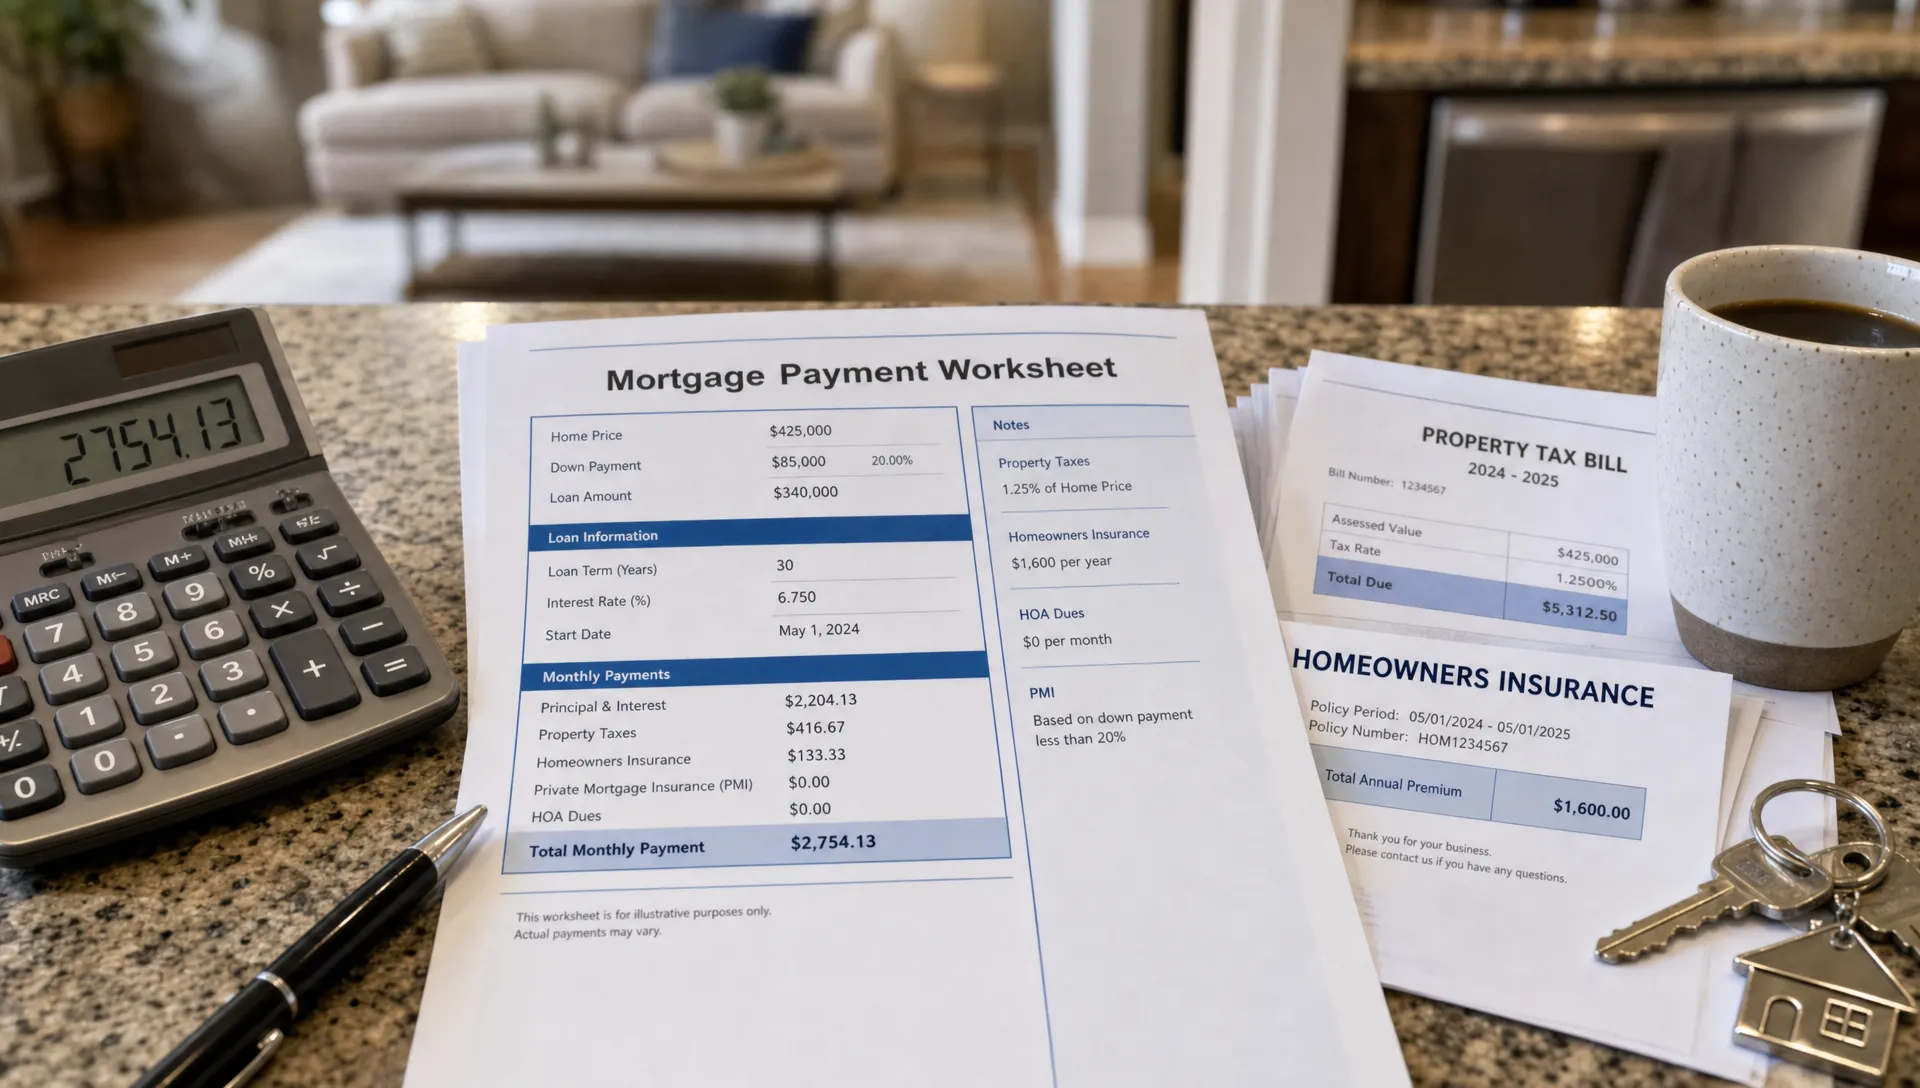
| What is the true monthly housing cost? | Principal, interest, taxes, insurance, HOA dues, utilities and maintenance | The mortgage payment alone understates the cost of staying in the home |
| How durable is your income? | Social Security, pension income, withdrawals and part-time work | Retirement income can change after market losses or a spouse's death |
| How much cash remains after housing? | Monthly surplus after essential expenses | A plan with no cushion can fail after one surprise bill |
| How long do you expect to stay? | Years in the home compared with refinance costs | Short timelines make closing costs harder to justify |
| What happens to home equity? | Future equity after interest, withdrawals or cash-out borrowing | Equity may be needed for downsizing, care or estate goals |
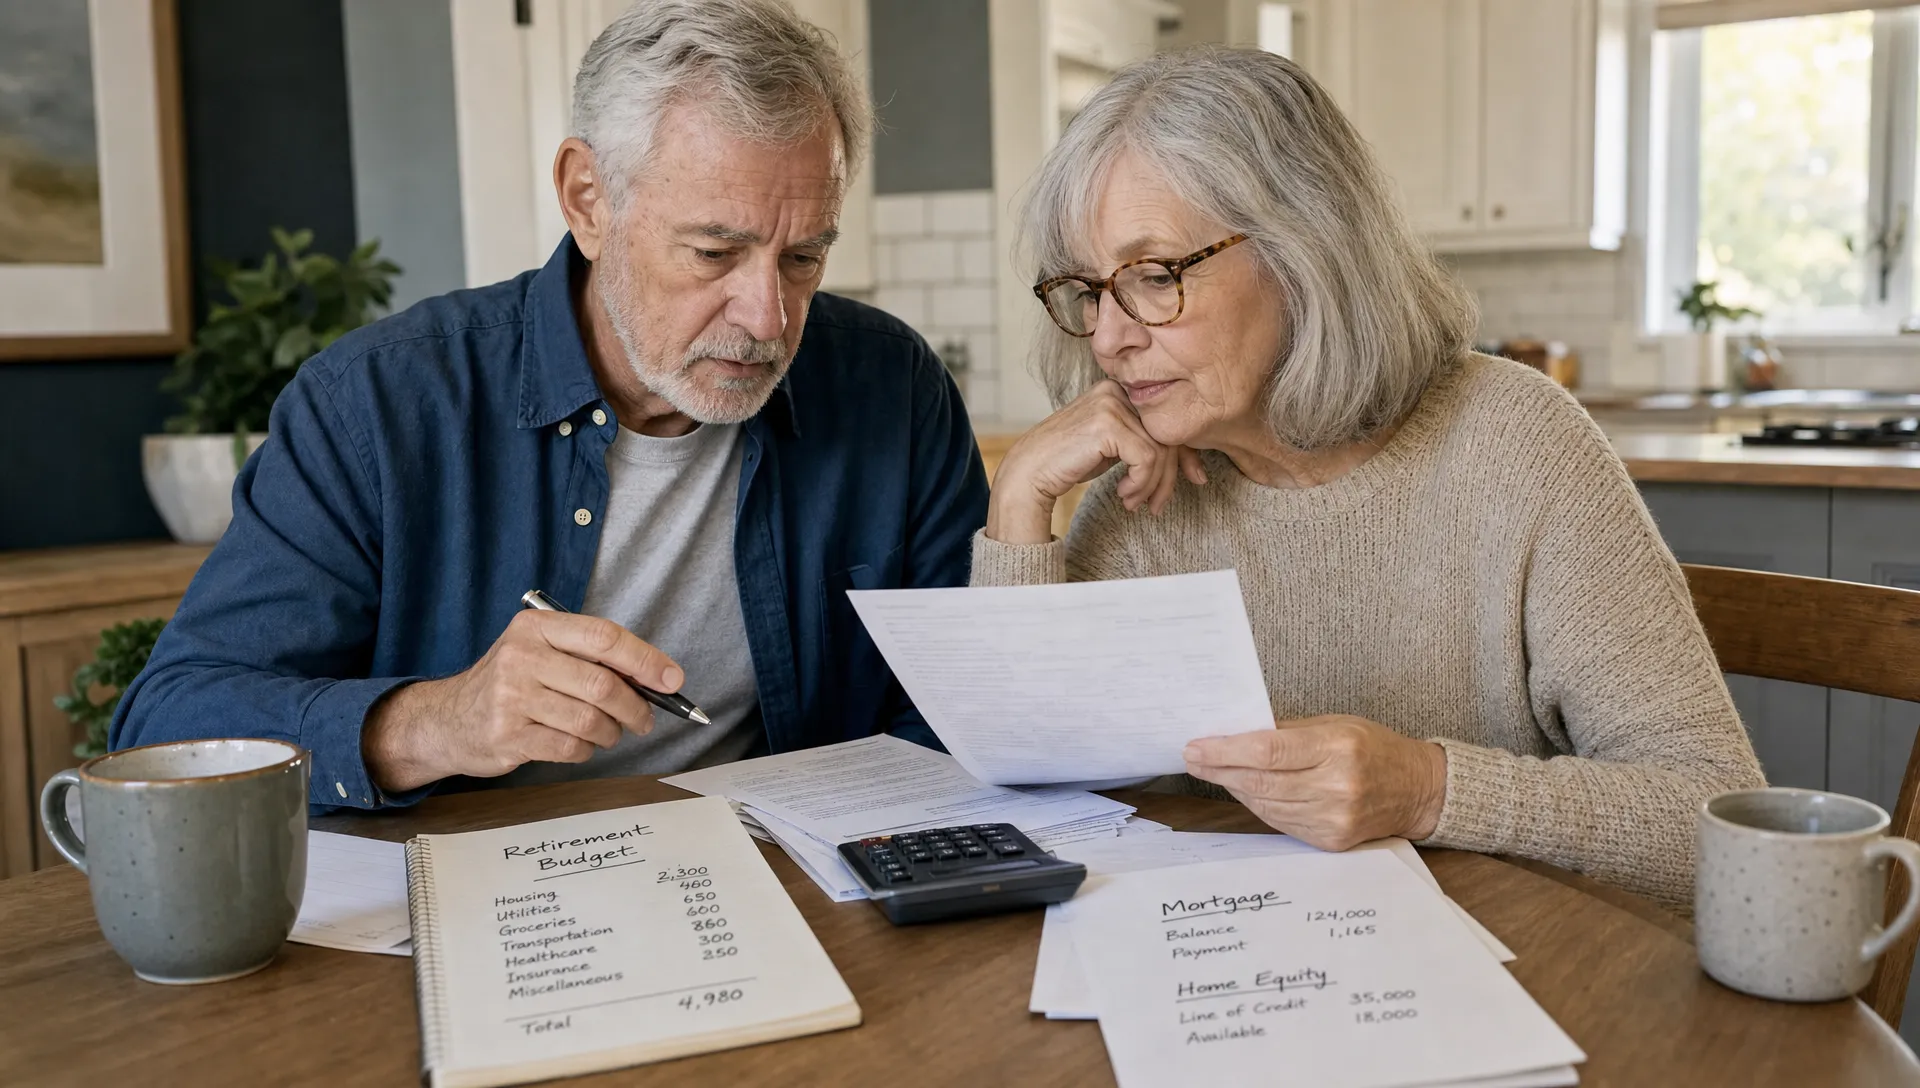
Build a retirement version of your mortgage budget
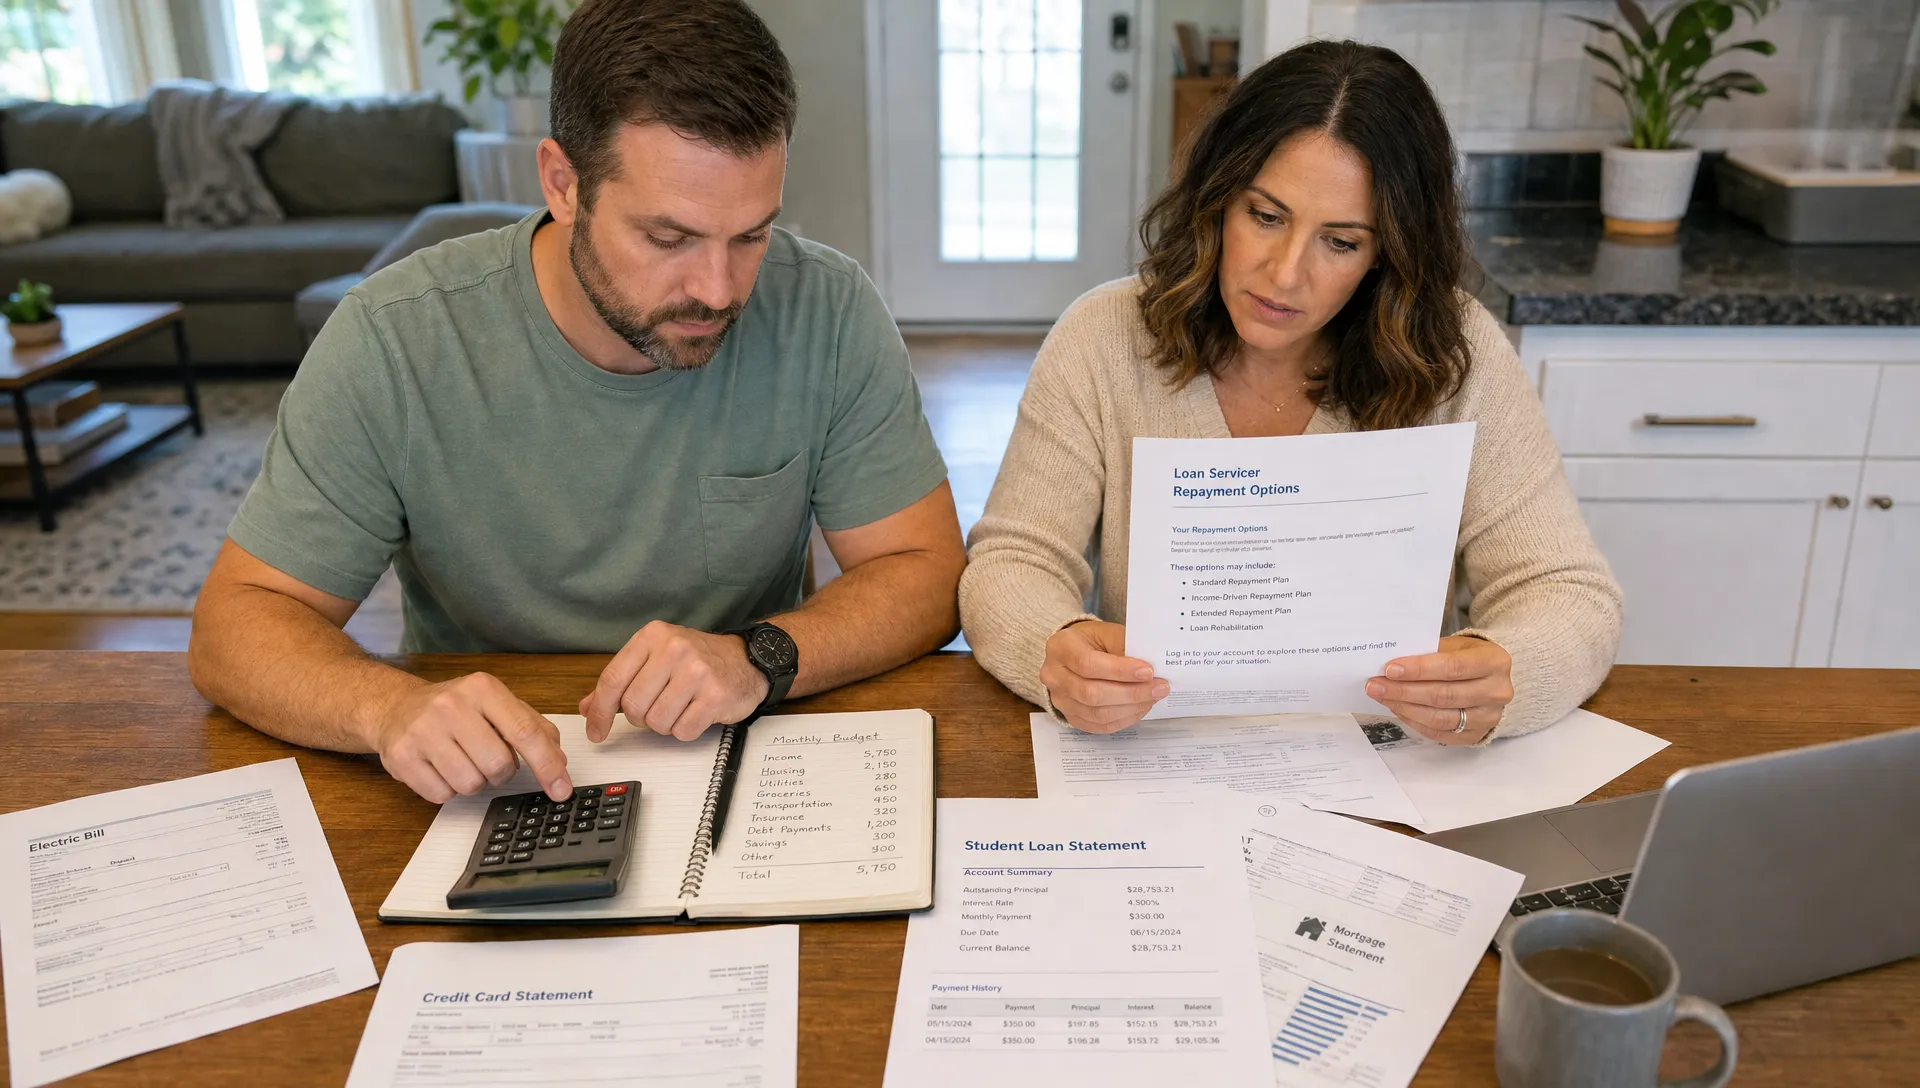
A regular mortgage budget focuses on qualifying for the loan. A retirement mortgage budget focuses on living with the loan. That means including costs lenders may not fully capture in your day-to-day comfort zone, such as prescriptions, dental care, home modifications, travel to see family and support for an aging parent or adult child.
If you need a framework for the affordability side, New Era Lending's guide to finding a mortgage that fits your budget can help you look beyond the advertised monthly payment and compare the full cost of home financing.
Stress test bad years
The most useful retirement test is not whether the mortgage works when markets are strong. It is whether it still works during a weak year, after a large repair or when one income source drops.
If you would need to sell investments at a loss, use credit cards or skip necessary maintenance to keep up with the payment, the strategy may be too tight. A smaller loan, a different term or a payoff plan may provide more peace of mind.
Include spouse and estate goals
Mortgage decisions affect more than the person who signs the loan documents. A surviving spouse may have different income, different maintenance ability and different plans for the home. Adult children may expect to inherit equity, help with care decisions or assist with selling the property later.
The goal is not to let family preferences control your retirement. It is to avoid surprises. A clear conversation now can prevent confusion if health, housing needs or estate plans change.
Alternatives to a mortgage for life
Choosing a mortgage for life is only one path. Many retirees and pre-retirees are really trying to solve one of three problems: lowering monthly obligations, preserving cash or accessing equity. The right structure depends on which problem matters most.
| Alternative | Best suited for | Watch for |
|---|---|---|
| Pay down or pay off the mortgage | Homeowners who value certainty and have strong cash reserves | Using too much cash can reduce liquidity |
| Refinance to a shorter term | Borrowers who want faster payoff and can handle higher payments | Monthly cash flow may become tighter |
| Refinance to a longer term | Borrowers who need lower monthly payments | Total interest and payoff timeline may increase |
| Recast the mortgage | Homeowners with a lump sum who want a lower payment without a full refinance | Not all loans are eligible |
| Cash-out refinance or home equity loan | Homeowners who need funds for a clear purpose | Borrowing against equity increases debt |
| Reverse mortgage | Older homeowners who want to access equity and stay in the home | Fees, property charges and future equity impact require careful review |
| Downsize or relocate | Homeowners whose current home is costly or difficult to maintain | Moving costs, taxes and lifestyle changes matter |
If your main question is whether to eliminate the payment before leaving work, the article on whether you should pay off your mortgage early offers a deeper look at the tradeoff between guaranteed interest savings and keeping cash available.
If you already have a mortgage and need more room in your monthly budget, refinancing or equity options may be worth comparing. New Era Lending also covers practical choices for homeowners who need mortgage flexibility.
When it may be right for your retirement plan
At a high level, a mortgage for life may fit a retirement plan when the payment is comfortable, the loan terms are clear and the household has a reason to preserve liquidity. It is more questionable when the loan exists only because there is no other way to cover normal living expenses.
| It may fit when... | It may not fit when... |
|---|---|
| Your full housing payment is affordable on conservative income | The payment already requires stretching every month |
| You have emergency savings outside home equity | You would need credit cards or investment sales for repairs |
| The loan has predictable terms | The rate can reset and you are unsure how high payments could go |
| You plan to stay in the home long enough to justify costs | You may sell or relocate within a few years |
| You are comfortable with less future equity | You expect to rely on home equity for care, downsizing or heirs |
The emotional side matters too. Some retirees sleep better with no mortgage, even if paying it off is not mathematically perfect. Others feel more secure with cash in the bank and a manageable monthly payment. A retirement plan should account for both the spreadsheet and the person living with it.
Frequently Asked Questions
Is a mortgage for life the same as a reverse mortgage? Not always. Some people use the phrase to describe carrying a traditional mortgage throughout retirement, while others use it when talking about reverse mortgages. A reverse mortgage has its own eligibility rules, costs and responsibilities, so the exact loan type matters.
Is it bad to retire with a mortgage? Retiring with a mortgage is not automatically bad. It becomes risky when the payment strains fixed income, reduces emergency savings or prevents you from handling healthcare, taxes, insurance and home repairs.
Should I use retirement savings to pay off my mortgage? It depends on your interest rate, tax situation, cash reserves, investment risk, income stability and comfort with debt. Paying off the home can reduce monthly obligations, but using too much savings can leave you house-rich and cash-poor.
Can refinancing before retirement help? Refinancing may help if it lowers the payment, stabilizes the rate or better matches your retirement timeline. Compare closing costs, total interest, loan term and how long you expect to stay in the home before deciding.
Talk through your retirement mortgage options
A home loan should support your retirement plan, not force the plan to work around the loan. If you are deciding whether to keep, refinance, pay down or access home equity, a personalized review can make the tradeoffs clearer.
New Era Lending combines smart mortgage technology with human guidance for home purchase, refinance and equity access solutions across 39 states. You can compare options, review terms and choose a path that fits your budget, timeline and retirement goals.