


Mortgage Payment Solutions When Costs Rise
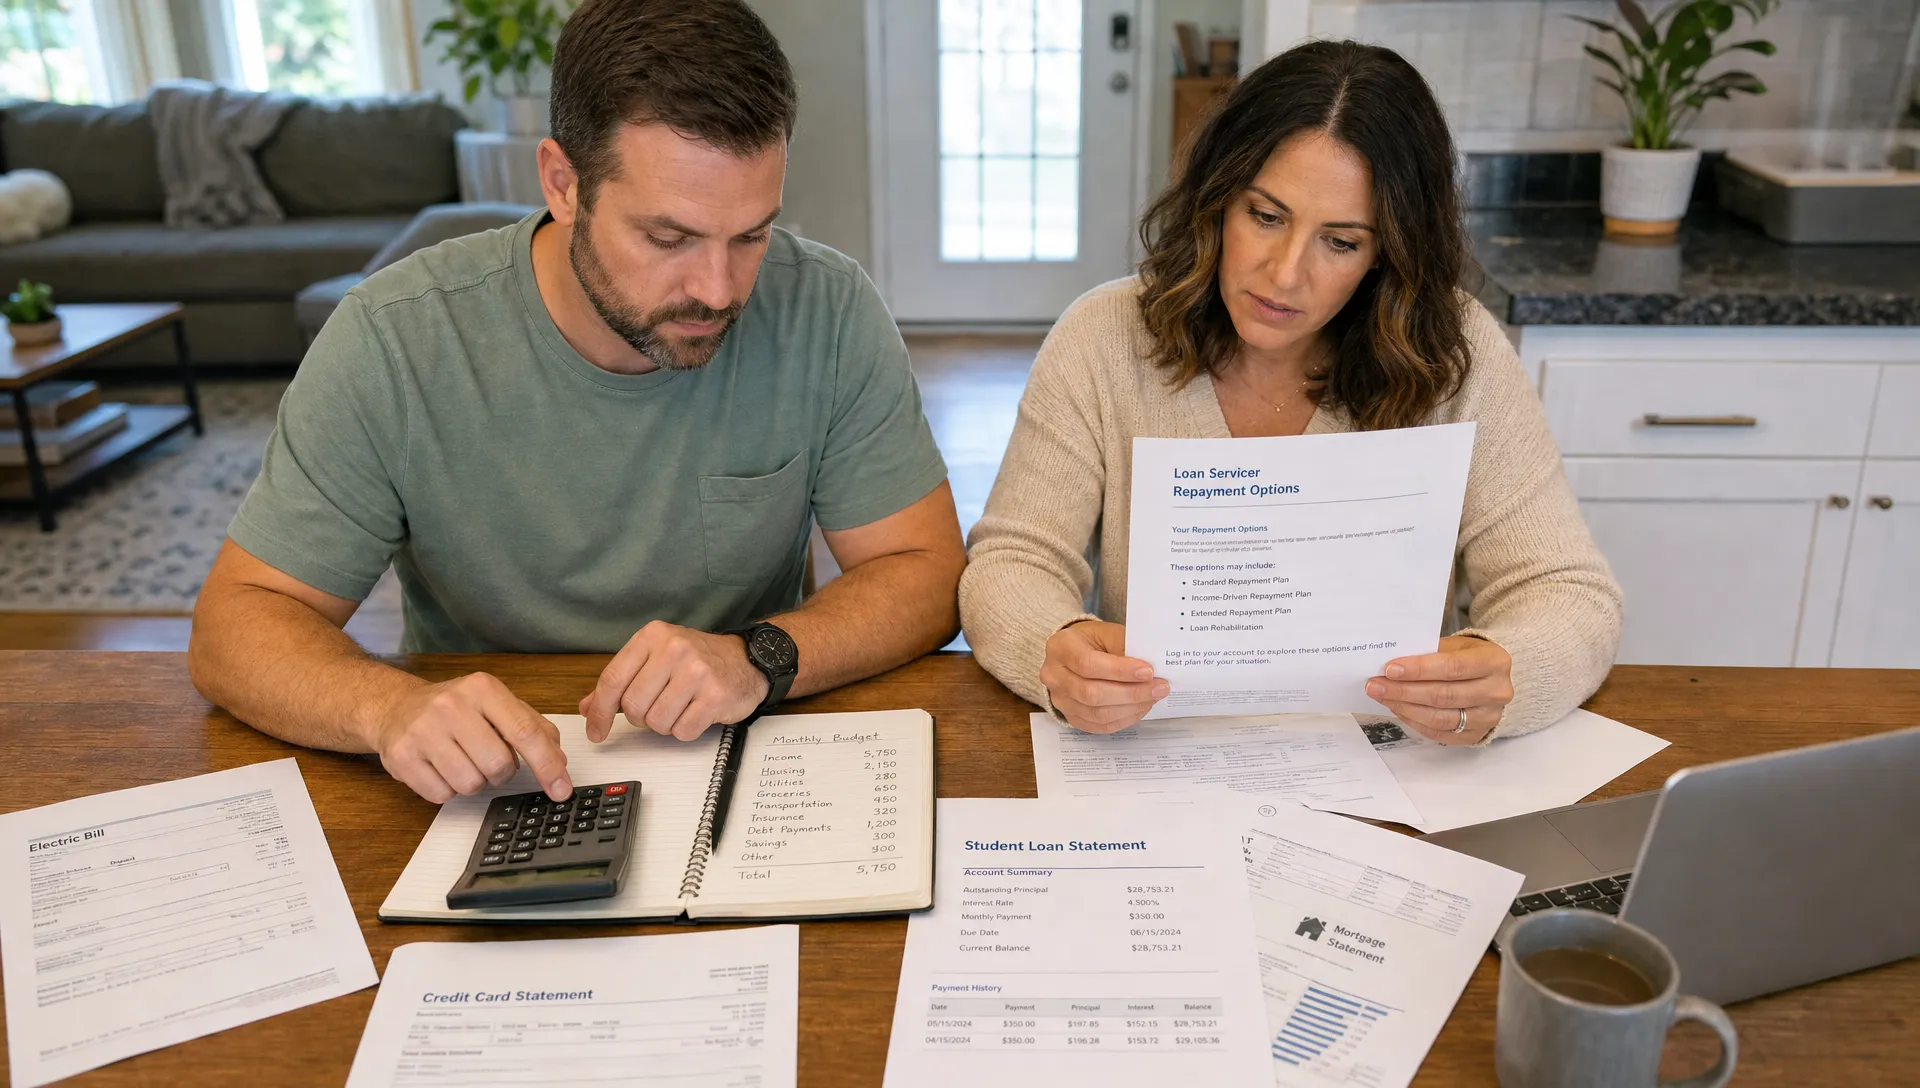
When household expenses jump, it is tempting to look for one big fix. In reality, the best mortgage payment solutions usually start with a clear diagnosis: what changed, how long the pressure is likely to last and whether your current loan still fits your income. A higher payment may come from escrow changes, insurance premiums, property taxes, an adjustable-rate reset, new debt or a temporary income gap.
Costs can rise even if you have made every payment on time and never touched your loan. Before you refinance, borrow against equity or call your servicer in a panic, separate permanent payment pressure from a short-term cash crunch. The right move for a one-time escrow shortage may be very different from the right move for a job change, insurance spike or loan term that no longer fits your budget.
Start With the Right Mortgage Payment Solutions for the Problem
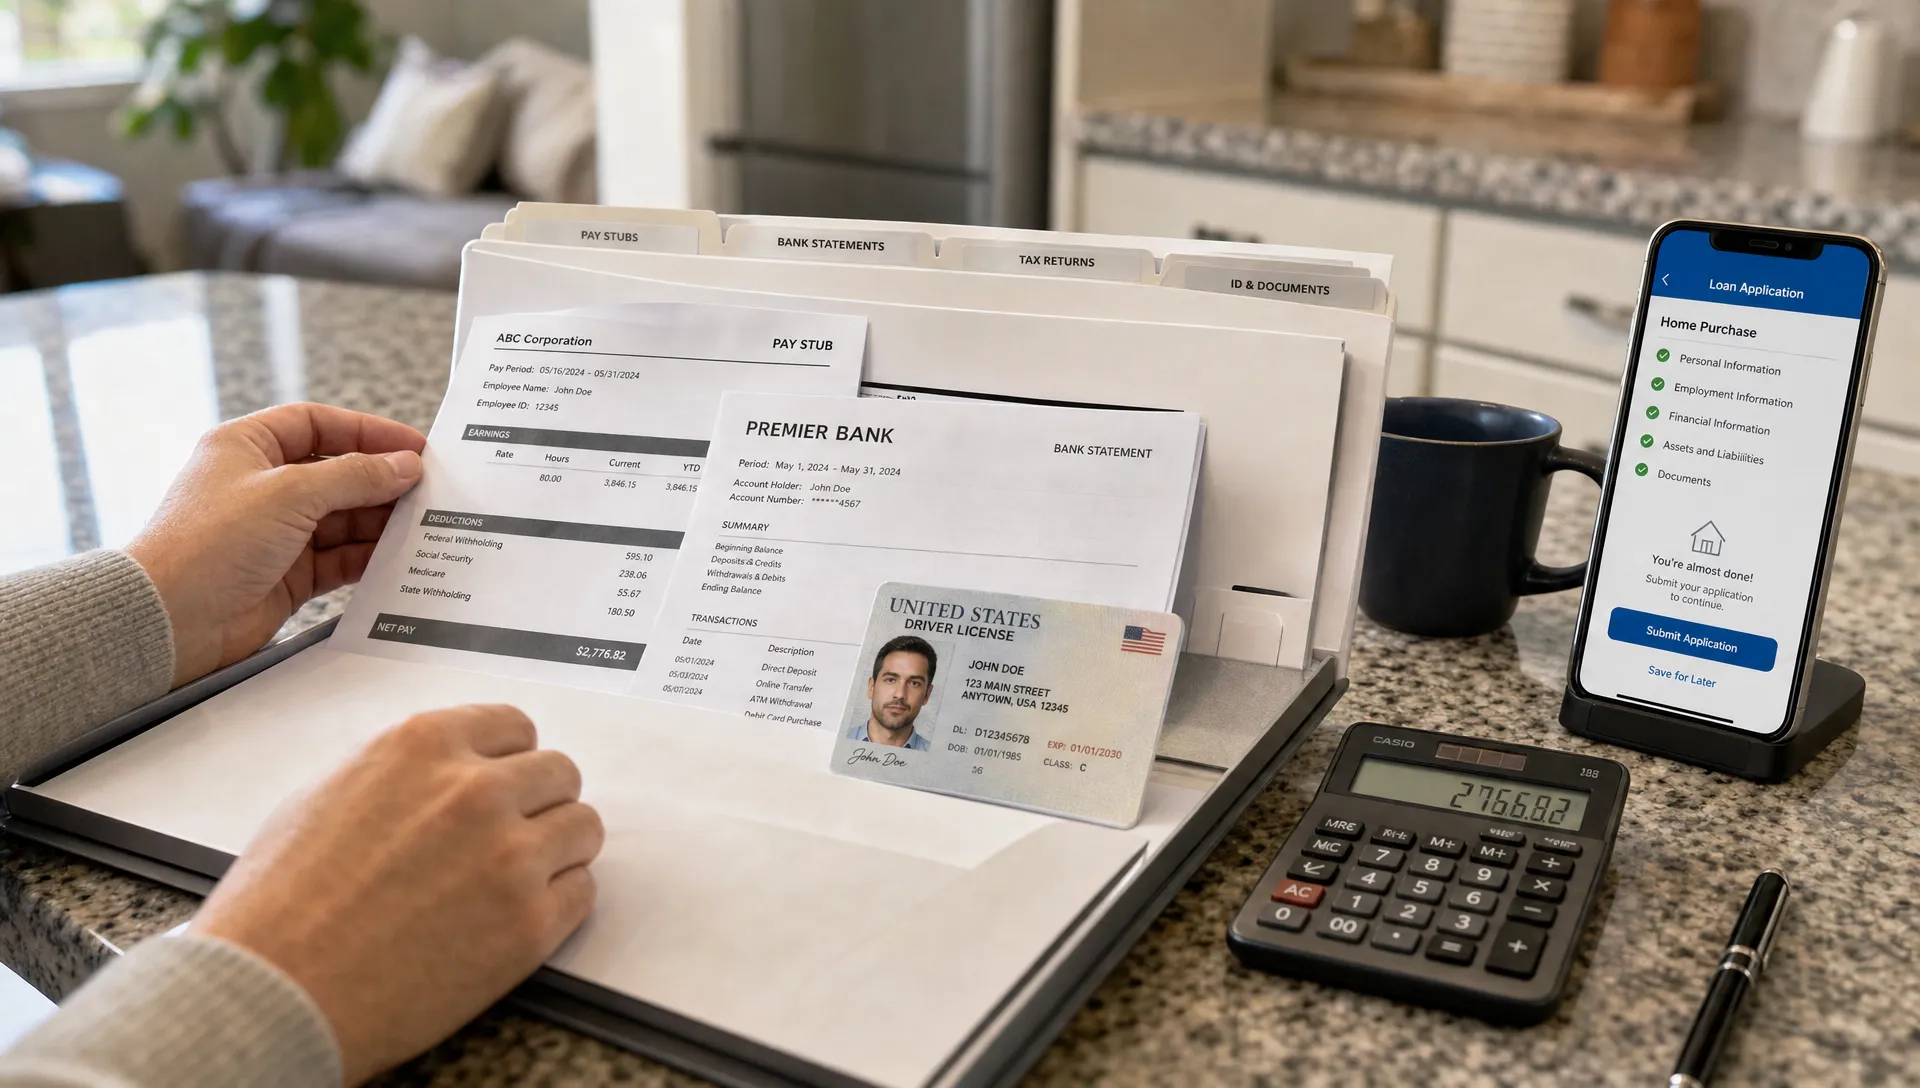
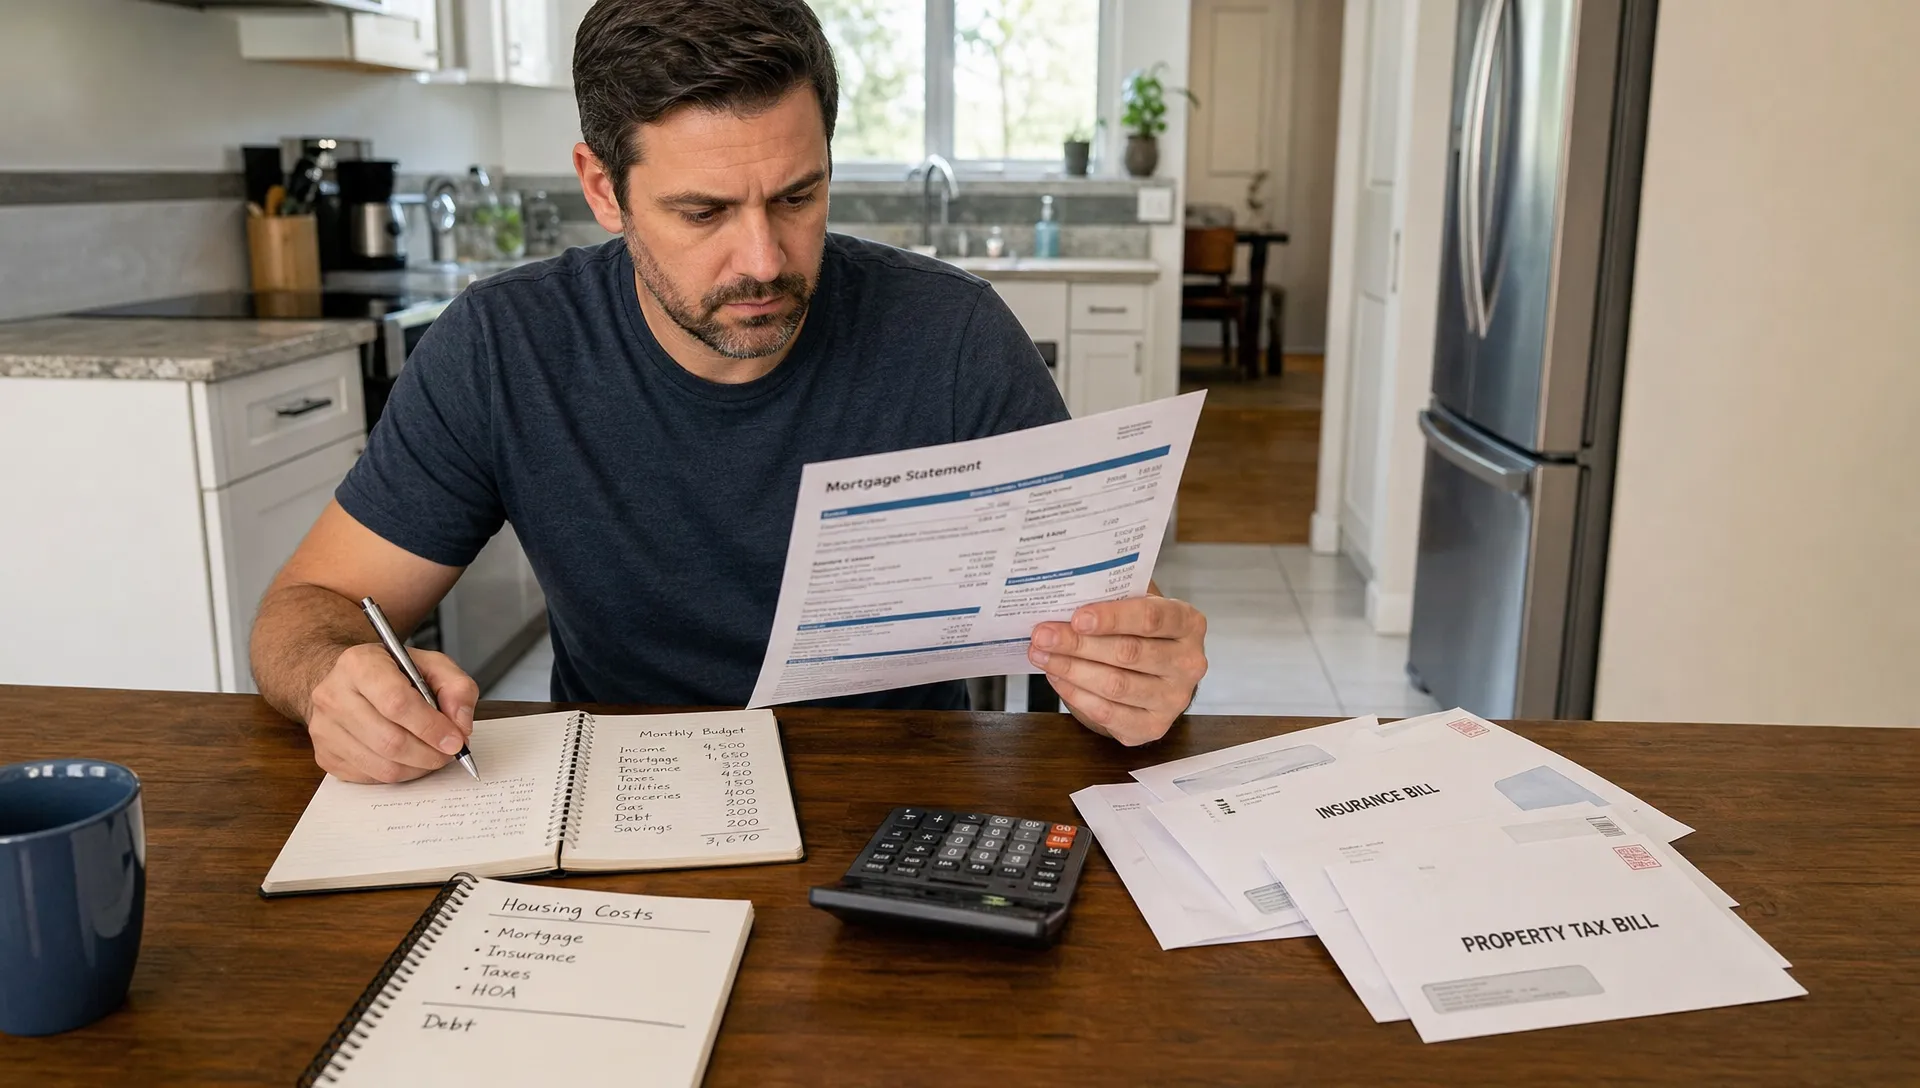
Do not start by asking, “Should I refinance?” Start by asking, “Which part of my housing cost changed?” Your mortgage statement, escrow analysis and insurance renewal notice can usually tell you whether the increase came from the loan itself or from costs collected alongside the loan.
| What changed | Common cause | First place to check |
|---|---|---|
| Escrow portion increased | Higher property taxes, insurance premiums or escrow shortage | Annual escrow statement |
| Principal and interest changed | Adjustable-rate mortgage reset, loan modification or repayment plan | Loan statement and rate change notice |
| Budget feels tighter but payment is the same | New debt, lower income, higher utilities or family expenses | Household cash flow |
| Cash reserves are shrinking | Repairs, medical bills or temporary income disruption | Savings and upcoming obligations |
Mortgage payment solutions become much clearer when the cause is visible. If the problem is escrow, refinancing may not fix it because taxes and insurance can follow you into the new loan. If the issue is an adjustable rate, a fixed-rate refinance may create stability. If the pressure is temporary, hardship assistance or a short-term budget adjustment may be safer than taking on new debt.
Diagnose What Actually Made Your Payment Rise
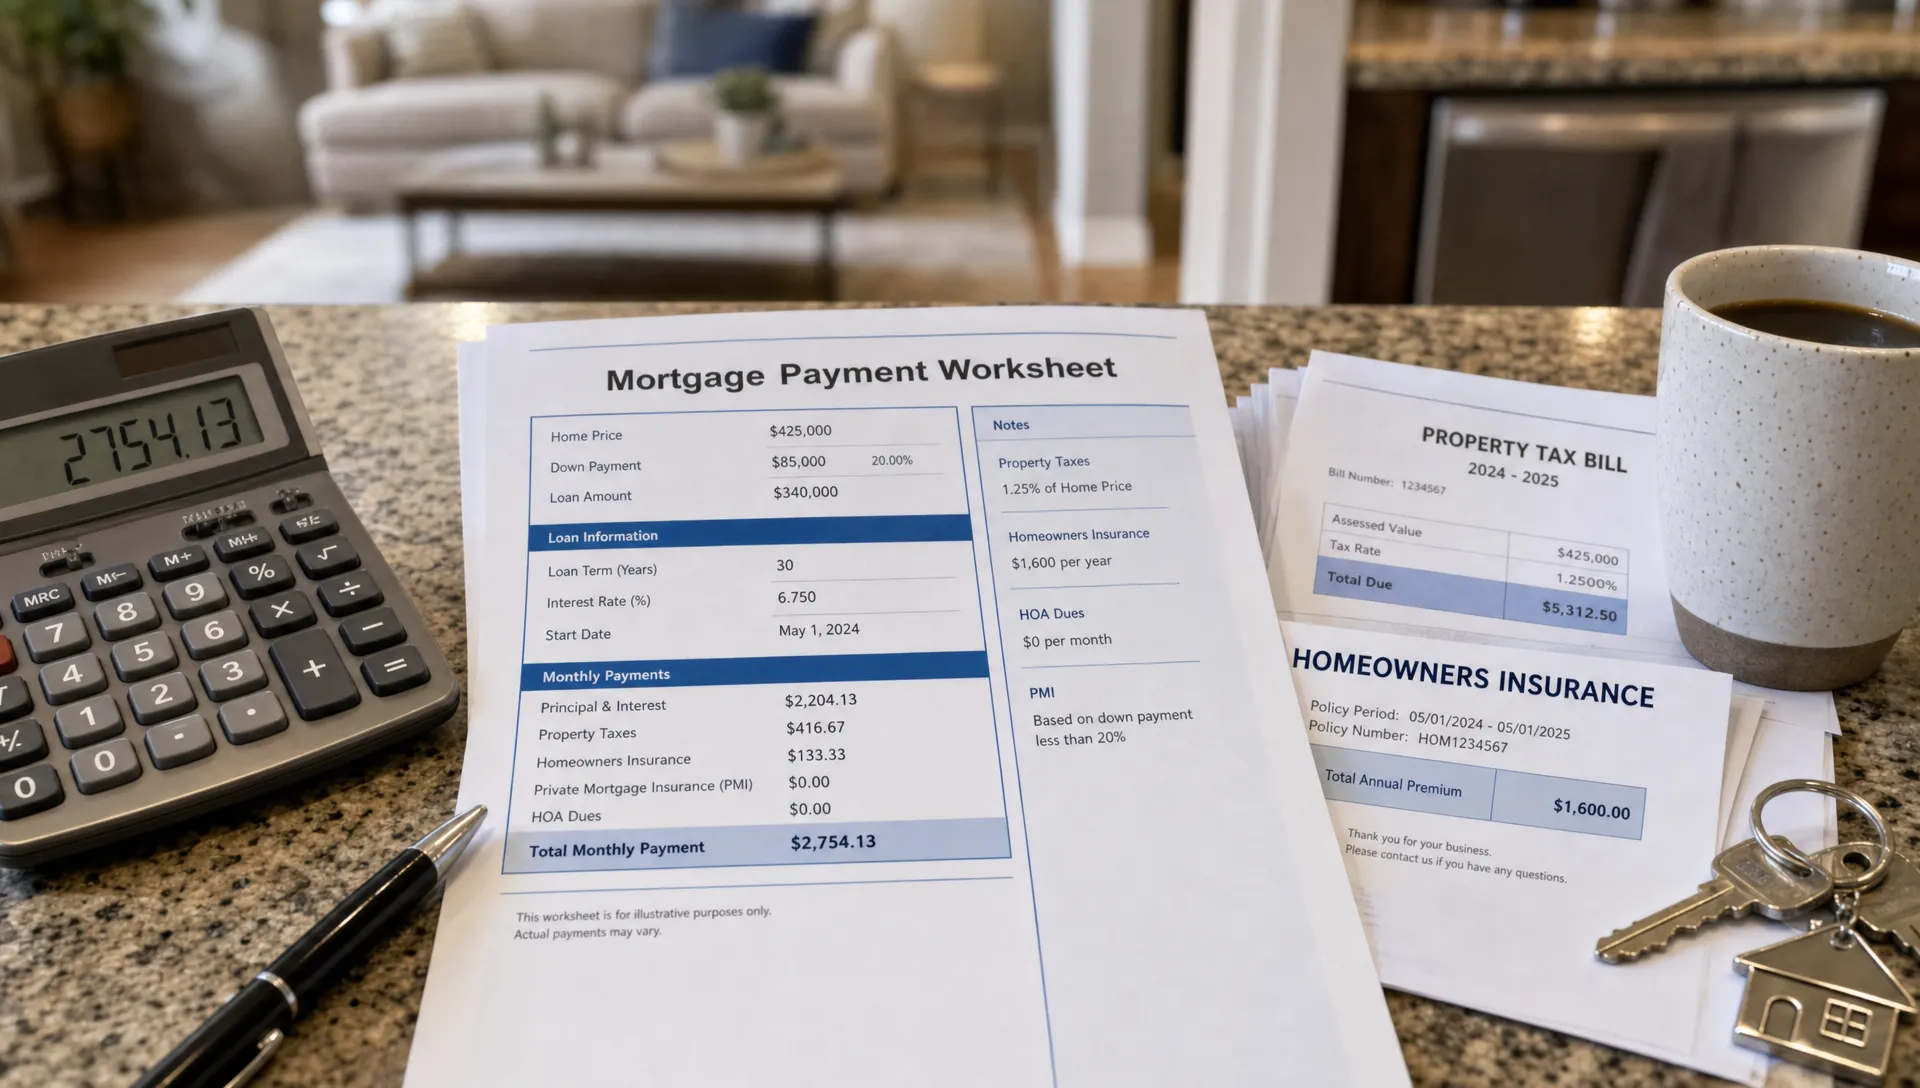
A monthly mortgage payment can include principal, interest, property taxes, homeowners insurance, mortgage insurance, HOA dues and escrow adjustments. With a fixed-rate mortgage, the principal and interest portion typically stays the same, but the total payment can still move if taxes or insurance increase.
If you are not sure which pieces are changing, review this breakdown of how mortgage payments are built and why they change. It can help you compare your old statement to your new statement without guessing.
Escrow increases deserve special attention. A servicer may raise your monthly collection if your tax bill or insurance premium went up, or if last year’s escrow account fell short. Ask for the escrow analysis, confirm the tax and insurance amounts and check whether you can spread a shortage over time instead of paying it as a lump sum.
If your loan has an adjustable rate, review the notice showing the new rate, index, margin and payment. For rising debt or income changes, the loan may not be the source of the problem at all. In that case, mortgage payment solutions should be evaluated alongside the rest of your monthly obligations, not in isolation.
Short-Term Moves That Create Breathing Room
Short-term mortgage payment solutions should protect your credit, preserve options and avoid turning a temporary squeeze into a long-term financial problem. If you can still make the payment, contact your servicer before the due date to ask about escrow shortage options, payment timing and any available assistance programs.
You can also look outside the mortgage itself. Homeowners insurance is one of the fastest-rising parts of many housing budgets, so compare coverage, deductibles and discounts before accepting a renewal increase. If you were making extra principal payments, temporarily redirecting that money to your regular payment or emergency fund may be more useful until cash flow stabilizes.
| Situation | Possible short-term action | Watch out for |
|---|---|---|
| One-time escrow shortage | Ask whether the shortage can be spread over future payments | Future payment may still stay higher |
| Insurance premium increase | Shop coverage and review deductible options | Do not reduce coverage below what your lender requires |
| Temporary income dip | Contact servicer early and review hardship options | Waiting until several missed payments can reduce choices |
| Rising non-mortgage debt | Rework budget and prioritize high-interest balances | Avoid payday loans or high-cost short-term credit |
These steps may not solve every problem, but they buy time and information. That matters because rushed decisions, especially cash-out borrowing or refinancing without comparing total costs, can create a lower payment today at the cost of a more expensive loan over time.
Refinance, Recast or Change the Loan Term
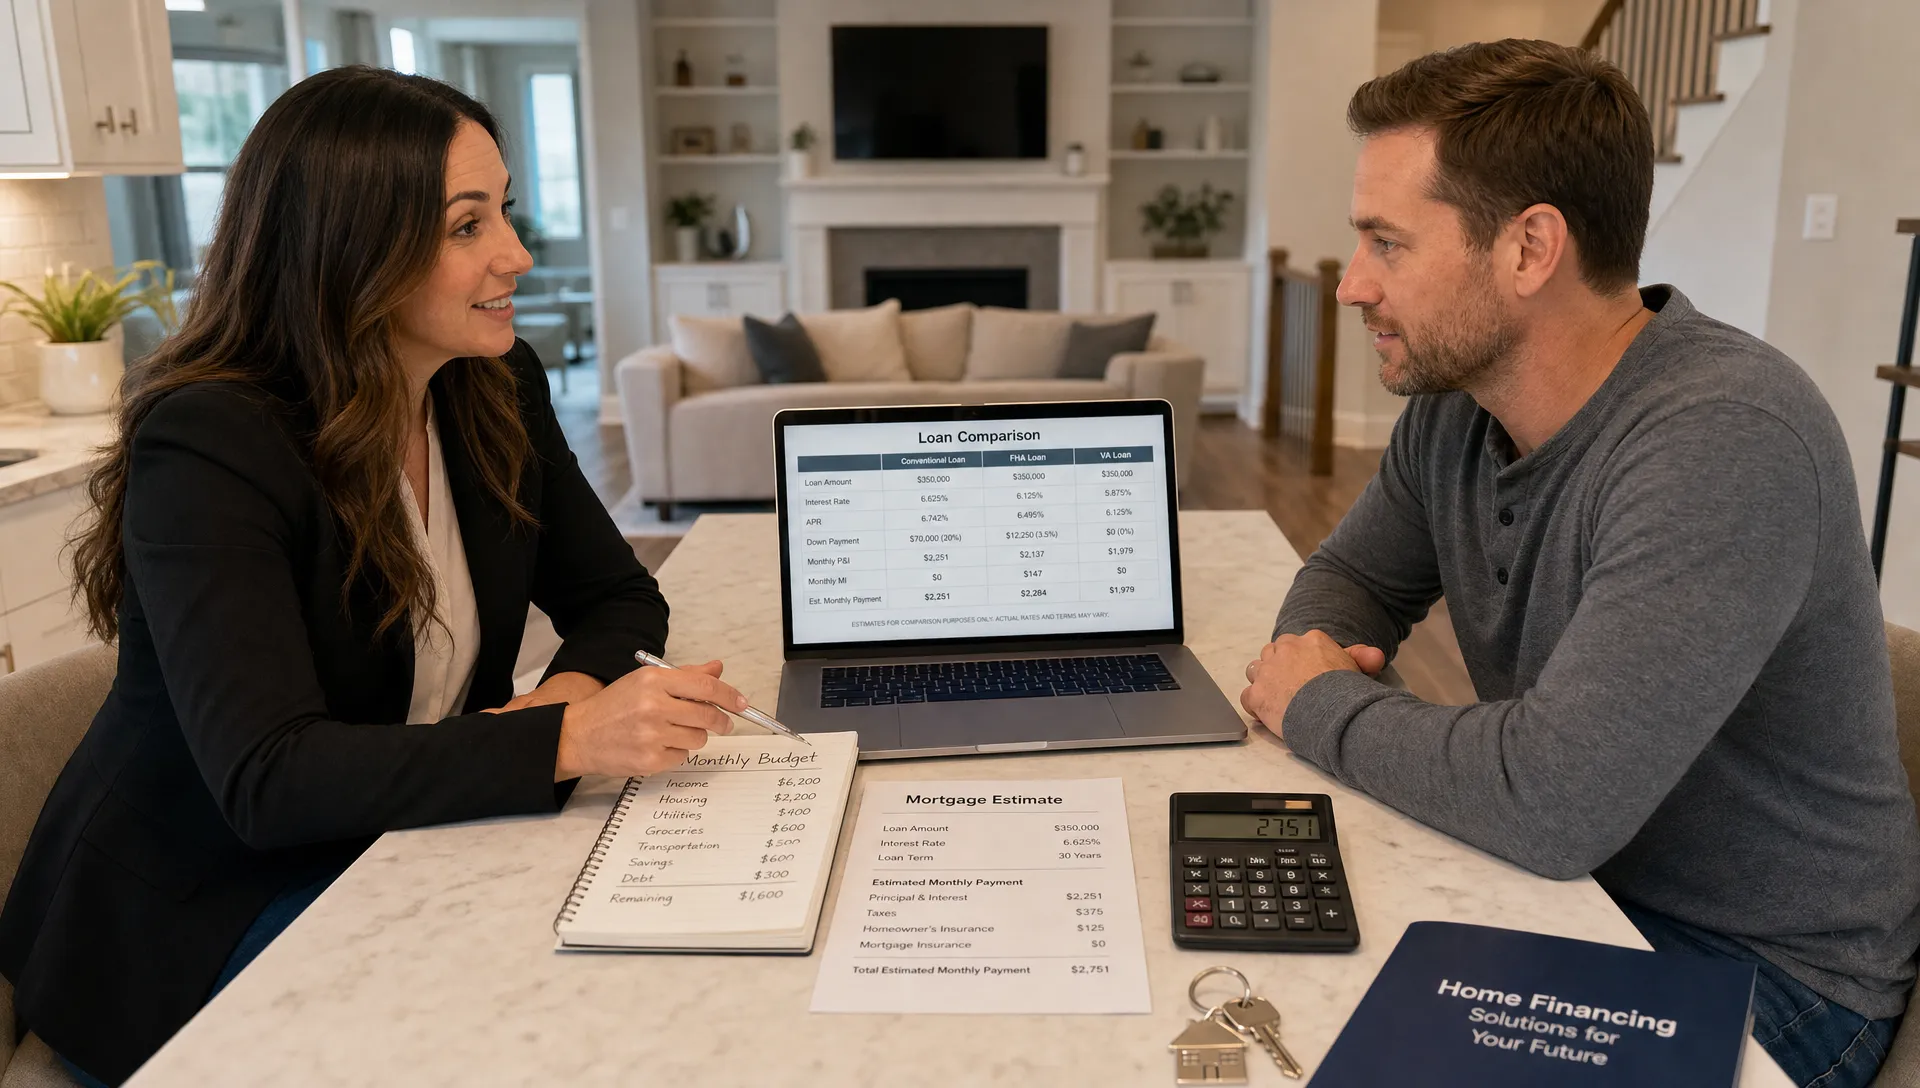
Refinancing replaces your current mortgage with a new loan. It may help if you can lower your rate, move from an adjustable rate to a fixed rate, remove mortgage insurance, extend the repayment term or consolidate certain costs into a structure that better fits your income. It can also increase total interest or closing costs, so the monthly payment should not be the only number you compare.
A refinance is one of the better-known mortgage payment solutions, but it is not automatically the best choice. A lower monthly payment can come from a better rate, a longer term or both. Extending the term may improve cash flow, yet it can keep you in debt longer. Paying points may reduce the rate, but only makes sense if the savings justify the upfront cost.
If you are considering a new term, recast or refinance, review the tradeoffs in this guide on changing mortgage terms before you commit.
| Option | When it may help | Main tradeoff |
|---|---|---|
| Rate-and-term refinance | Your current rate or structure no longer fits | Closing costs and qualification requirements |
| Longer repayment term | You need lower monthly cash outflow | More interest over the life of the loan |
| Loan recast | You have a lump sum and want a lower payment without changing the rate | Not all loans or servicers allow it |
| ARM to fixed-rate refinance | You want payment predictability | The new payment may not be lower immediately |
A recast can be useful when a homeowner has cash from a bonus, sale of another asset or other lump sum. The lender applies the money to principal, then recalculates the payment over the remaining term. It usually does not change the interest rate or loan maturity, and availability depends on the loan and servicer.
Use Home Equity or Consolidation Carefully
Debt pressure can make a mortgage feel unaffordable even when the housing payment itself has not changed. In that situation, homeowners sometimes look at cash-out refinancing, a home equity loan or a home equity line of credit. These tools can create flexibility, but they also use your home as collateral.
Home equity-based mortgage payment solutions are strongest when they solve a clear, measurable problem and fit a realistic repayment plan. For example, replacing high-interest debt with a lower structured payment may improve cash flow, but it can be risky if you continue adding new credit card balances afterward. If you are weighing that route, New Era Lending’s article on whether mortgage loan consolidation can lower your costs explains the tradeoffs in more detail.
Self-employed homeowners should be especially careful because business cash flow can blur the household budget. A food distributor, caterer or refrigerated delivery operator may be financing equipment, inventory or vehicle upgrades at the same time housing costs are rising. Businesses that depend on custom refrigerated van conversions need to account for those specialized capital costs separately from the mortgage budget before deciding how much payment flexibility the household truly needs.
The key is to avoid using home equity as a pressure release valve for an expense pattern that has not changed. Equity can be powerful, but it should be paired with a plan for income, spending and reserves.
When Hardship Assistance Is the Better Next Step
If you have already missed a payment or believe you soon will, contact your mortgage servicer as early as possible. Servicers may be able to discuss options such as forbearance, repayment plans, deferral, loan modification or program-specific assistance depending on your loan type and situation.
Hardship mortgage payment solutions are different from refinancing because they are usually designed to address financial distress, not optimize a loan for savings. A forbearance may pause or reduce payments for a period, but the missed amount still has to be resolved. A repayment plan may spread the overdue amount across future payments. A modification may change loan terms to create a more sustainable payment, subject to approval.
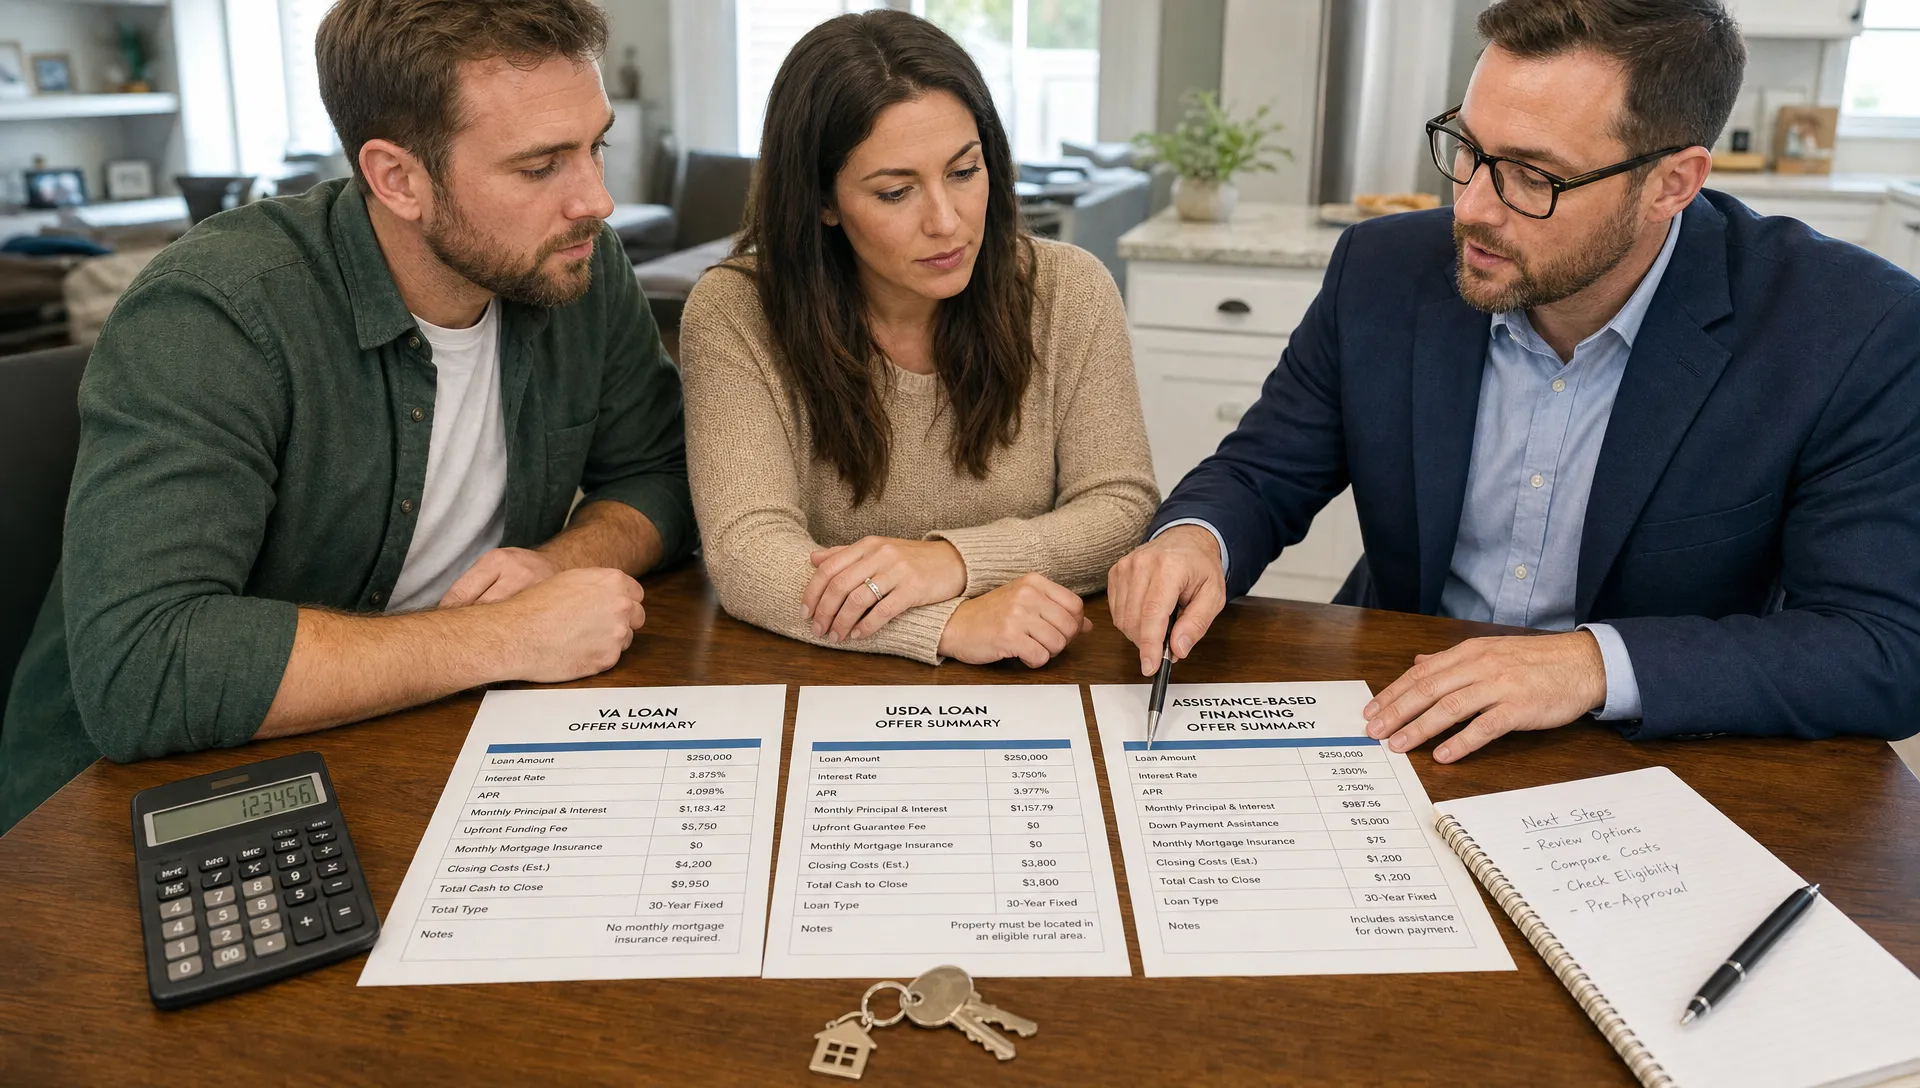
You can also contact a HUD-approved housing counseling agency for independent guidance, especially if you are behind or worried about foreclosure. If your loan is FHA, VA or USDA, ask your servicer about options tied to that program. Veteran homeowners should also make sure any advisor they work with understands VA loan rules and benefits.
A Practical Checklist Before You Choose
The best mortgage payment solutions balance monthly relief, total cost and risk. A move that lowers the payment by $200 today may not be worth it if it adds years of interest, drains your equity or leaves you with no emergency cushion.
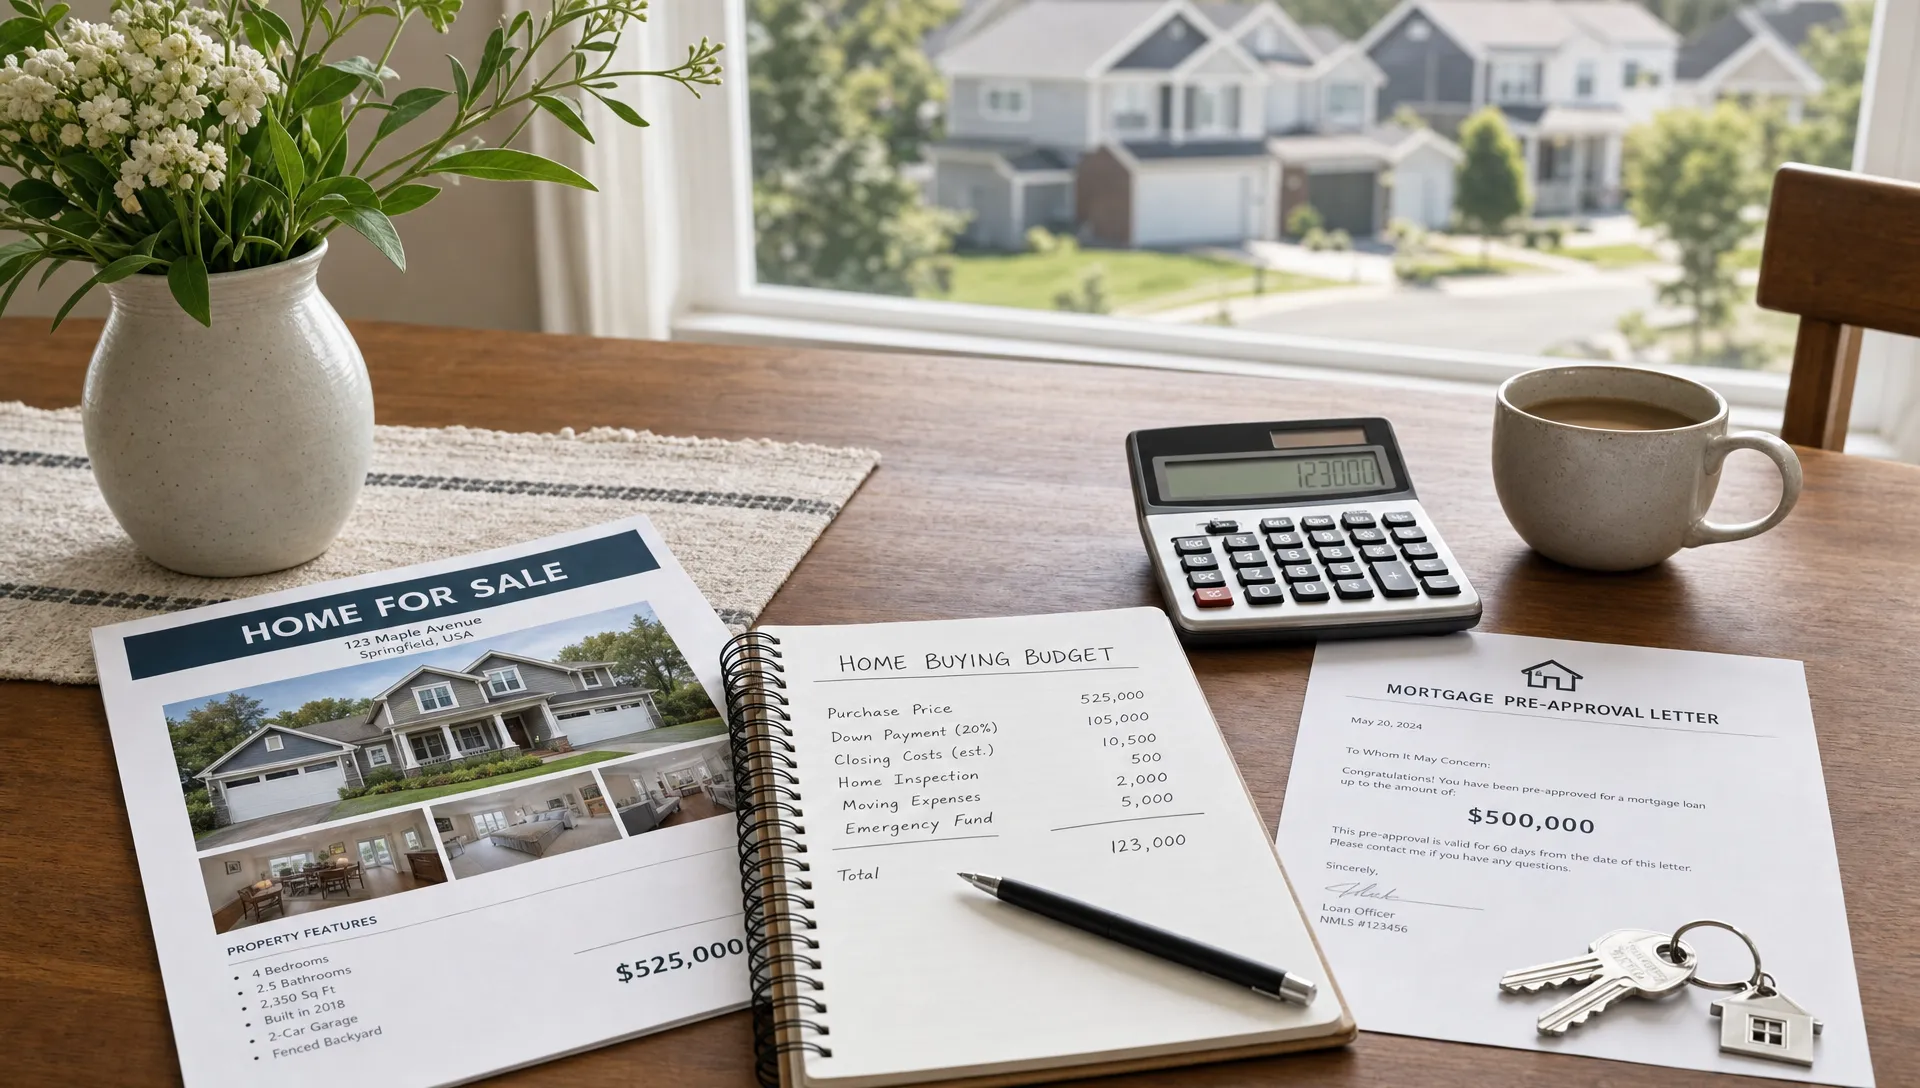
Before you act, write down the following numbers and answers:
- Your current full monthly housing payment, including escrow and HOA dues if applicable
- The exact amount of monthly relief you need to feel stable
- Whether the problem is temporary, seasonal or likely to last more than a year
- Your estimated home equity and credit profile
- Any cash needed for closing costs, escrow deposits or prepaid expenses
- How long you expect to stay in the home
- Whether you are current, late or at risk of missing the next payment
This checklist keeps the conversation grounded. If you are current and the issue is affordability, refinancing or a term adjustment may be worth comparing. If you are behind, hardship support should move to the top of the list. If your payment rose because of taxes or insurance, the solution may involve escrow planning rather than a new loan.
Frequently Asked Questions
What mortgage payment solutions should I try first when costs rise? Start by identifying what changed in your payment. Review your mortgage statement, escrow analysis, insurance renewal and tax bill. If you are current, ask about escrow shortage options and compare insurance costs. If you may miss a payment, contact your servicer right away.
Will refinancing always lower my mortgage payment? No. Refinancing can lower a payment if the new rate, term or loan structure improves your monthly cost enough to outweigh closing costs. It can also raise total interest if you extend the loan term or roll costs into the balance.
Can my lender reduce my payment if I am struggling? Your servicer may be able to review hardship options, but approval depends on your loan type, investor rules, income and documentation. Common paths include forbearance, repayment plans, deferral or loan modification.
Is it smart to use home equity to pay other debts? It can help in some cases, especially when it reduces high-interest debt and creates a payment you can sustain. It is risky if it simply moves unsecured debt onto your home without changing the spending pattern that caused the pressure.
Find a Clearer Path Before Costs Get Heavier
Rising housing costs can feel overwhelming, but you do not have to choose a solution based on guesswork. New Era Lending combines modern mortgage technology with human guidance to help homeowners compare purchase, refinance and equity-access options with a clearer view of rates, terms and documentation needs.
If your current mortgage no longer fits your budget, start by getting organized, then talk through your options before the pressure becomes urgent. You can also review New Era Lending’s guide on what to do if you have a mortgage and need flexibility for more next steps.