


How to Choose the Right Home Loan Team
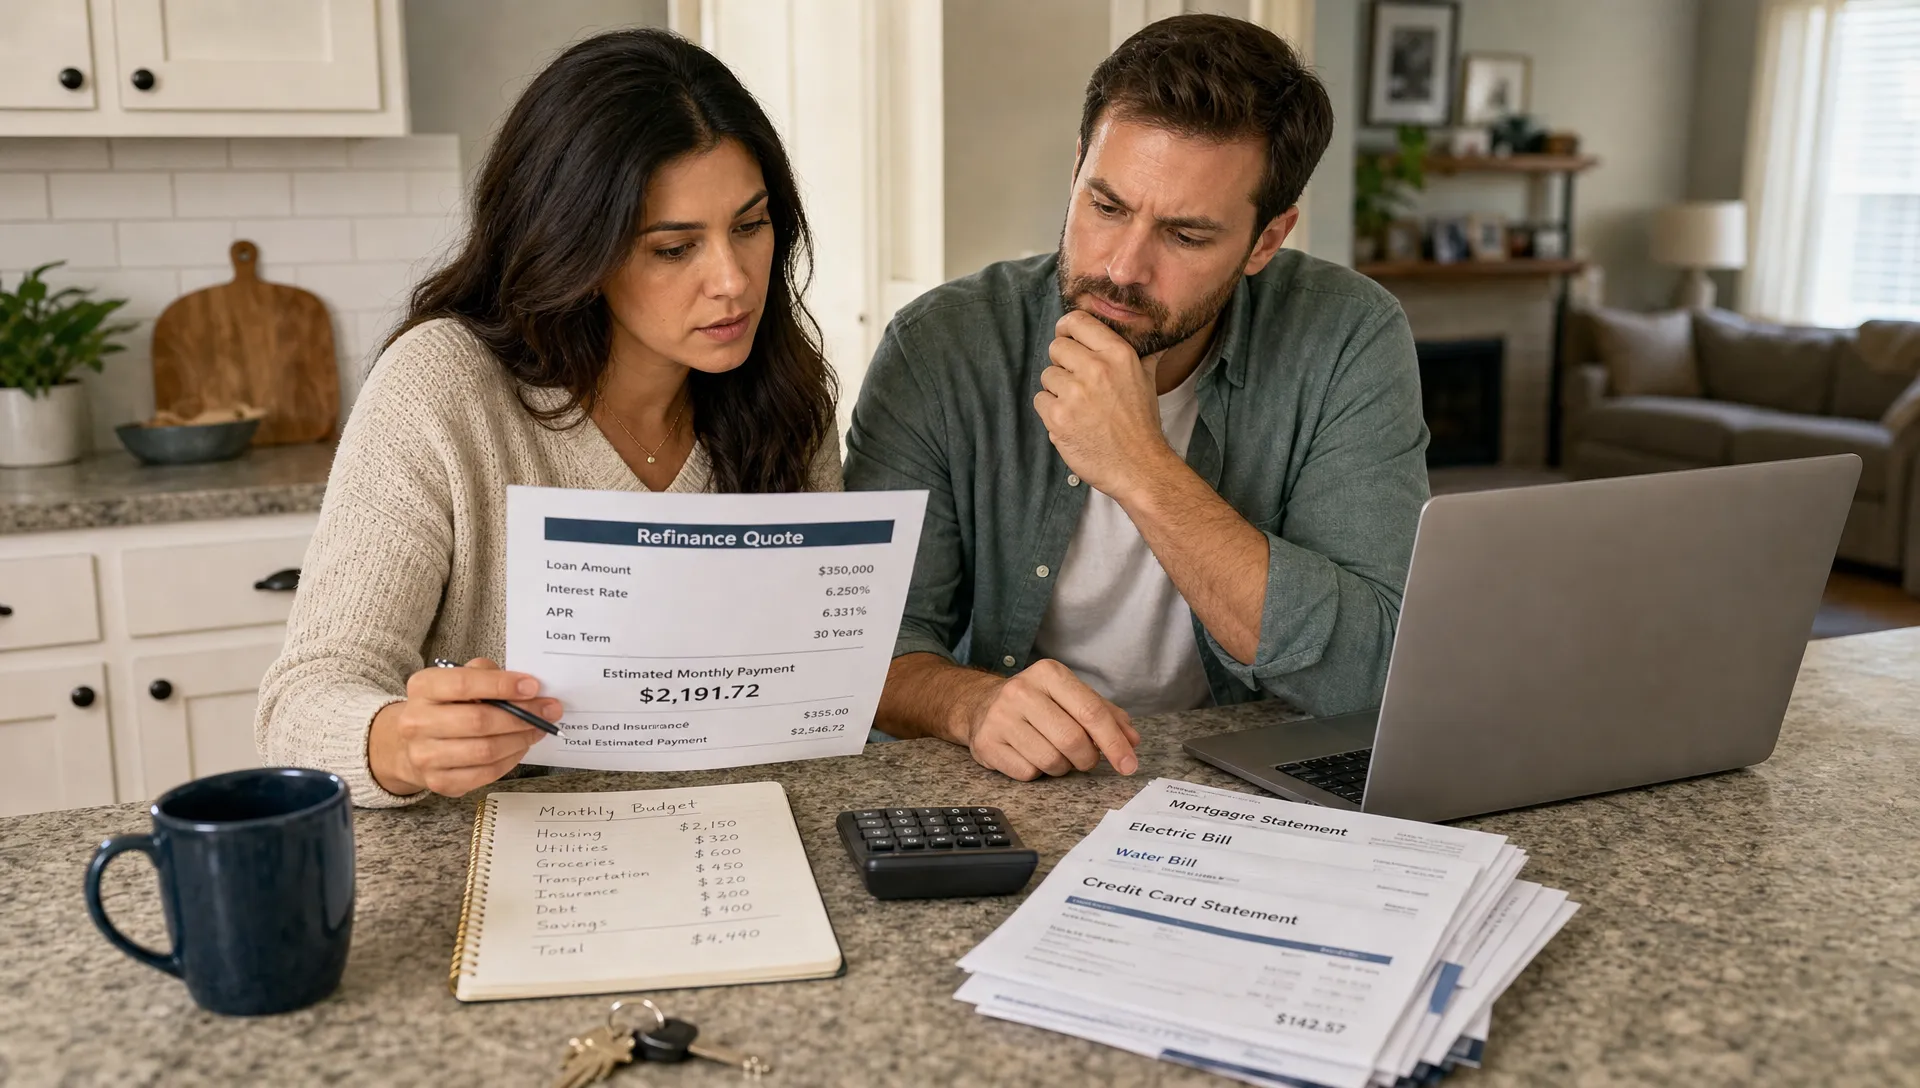
Choosing the right home loan team can shape every part of your purchase, refinance or cash-out experience: how clearly your options are explained, how quickly problems surface and how confident you feel before closing. Rates matter, but a mortgage is not just a price quote. It is a process with deadlines, documents, underwriting rules and decisions that affect your monthly budget for years.
This guide focuses on the people and process behind the loan. If you are still comparing mortgage products, it may help to first review how to choose the right new home loan so you know which questions matter most for your situation. Once you understand your goal, the next step is finding a team that can guide you through it with accuracy, speed and accountability.
What a strong home loan team actually does
A mortgage may feel like one conversation with one loan officer, but several people usually help move the file from application to closing. Your main contact explains options, collects information and helps you prepare. A processor checks documents and keeps the file moving. An underwriter reviews risk, eligibility and guidelines. A closing or funding specialist helps finalize the last steps.
At a minimum, a dependable home loan team should translate this process into plain language. You should know what is needed, why it is needed and when each milestone is expected. A good team does not make you guess whether your bank statements were received or whether your rate lock is still active.
The best teams also tell you when a loan structure is not a fit. That candor matters. A lender who only says yes during the first conversation may leave you exposed later if the file is not reviewed carefully.
Start with licensing, reputation and accountability
Before you compare personalities, confirm that the lender and mortgage professional are properly licensed for your state. The Nationwide Multistate Licensing System offers NMLS Consumer Access, where borrowers can look up licensing details and regulatory history for mortgage companies and individual originators.
Licensing does not guarantee a perfect experience, but it is a baseline. You also want to know who is responsible if something changes. Ask whether you will have one primary point of contact, who covers that person when they are unavailable and how escalations are handled if the closing timeline gets tight.
When a home loan team is accountable, they can explain their process without sounding evasive. They should be comfortable discussing fees, documentation, underwriting conditions and realistic timelines. For a broader framework, New Era Lending’s guide on how to choose a lending company you can trust covers licensing, transparency and warning signs in more detail.
Evaluate communication before you apply
Communication is not a soft bonus in mortgage lending. It can affect whether you win a purchase offer, avoid last-minute stress or understand the true cost of a refinance. Slow answers, vague updates and inconsistent instructions create friction at the exact moments when clarity matters most.
When you compare a home loan team, pay attention to how they respond before you are a client. Do they ask about your timeline, income structure, down payment and comfort zone? Do they explain next steps clearly? Do they answer the question you asked, or do they rush toward an application?
Ask these communication questions early:
- How quickly do you usually respond during business hours?
- Will I communicate by phone, email, text or a secure portal?
- Who will update my real estate agent if I am buying a home?
- How will I know which documents are still missing?
- What happens if a problem comes up close to closing?
Fast replies are useful, but accuracy is more important than speed alone. A same-day answer that misses a key detail can cost more time than a careful answer delivered with a clear explanation.
Compare guidance, not just rate quotes
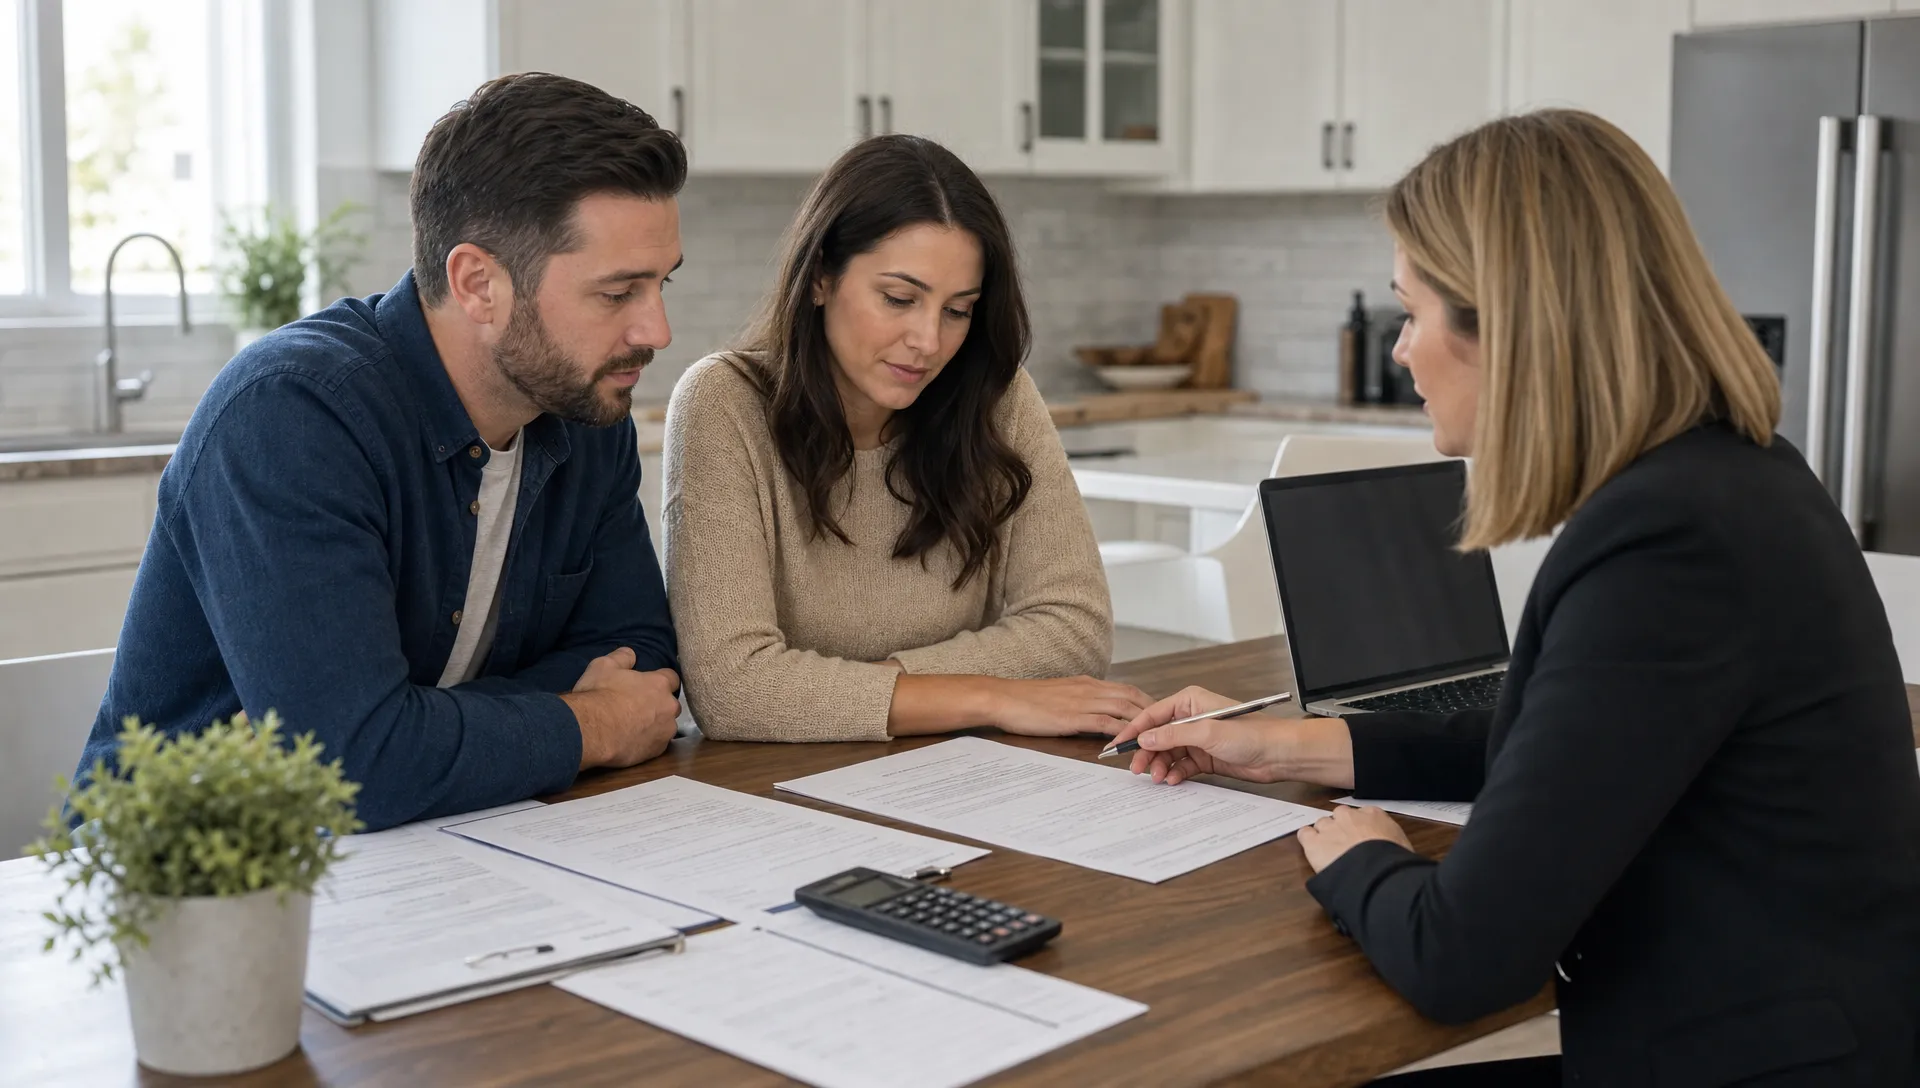
The lowest advertised rate is not always the best loan. A quote may include discount points, lender credits, assumptions about credit score or a different lock period. That is why serious comparisons should use the official Loan Estimate, which the Consumer Financial Protection Bureau explains in its guide to reviewing and comparing mortgage offers.
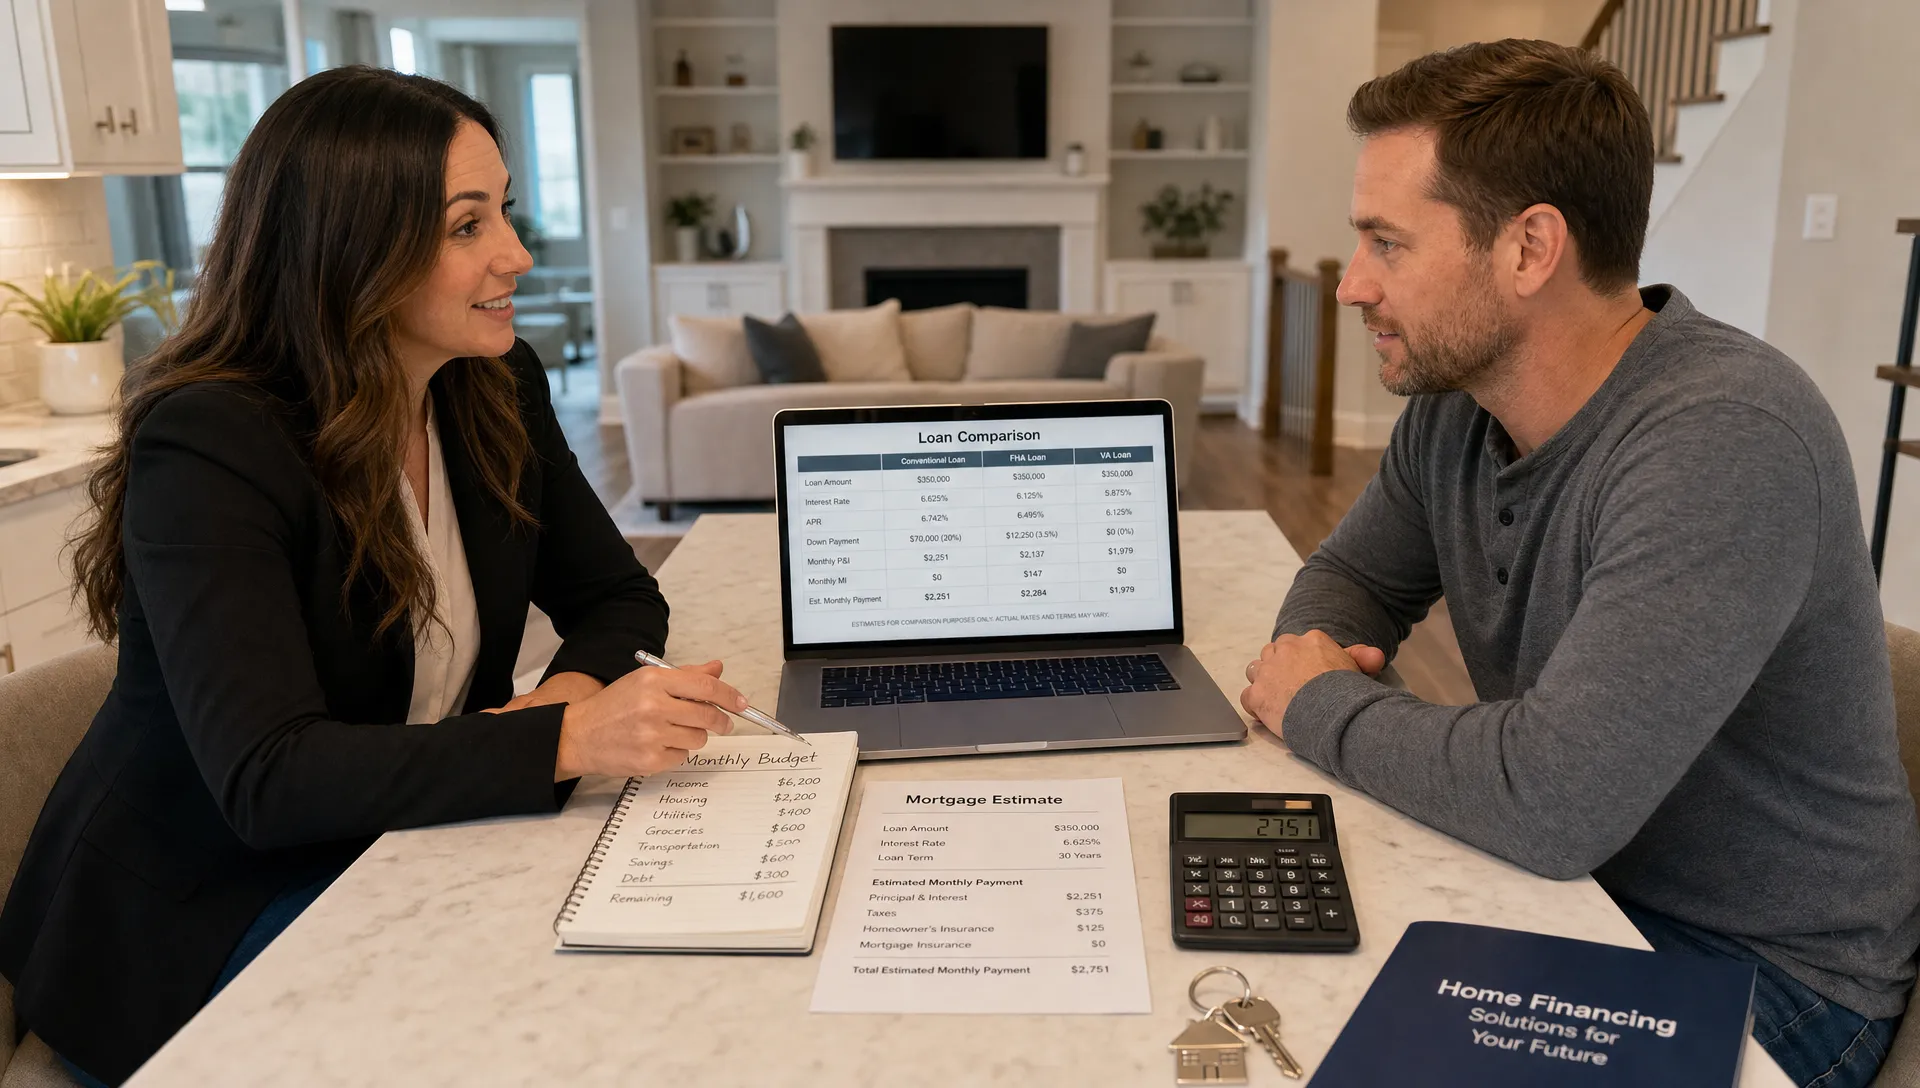
A strong lender will walk you through the full picture: interest rate, APR, closing costs, cash to close, prepaid items, mortgage insurance if applicable and monthly payment. If you are actively comparing quotes, this guide to home loan lending rates explains how to look beyond the headline rate.
The right home loan team should help you understand tradeoffs, not push you toward the option that looks cheapest on day one. A lower rate with high upfront points may make sense if you keep the loan for many years, but it may not help if you expect to sell or refinance sooner.
| What to compare | Why it matters | What to ask |
|---|---|---|
| Interest rate and APR | APR reflects certain loan costs, not just the note rate | What assumptions are included in this quote? |
| Discount points | Points can lower the rate but increase upfront cost | What is the break-even period? |
| Lender credits | Credits can reduce cash to close but may raise the rate | How does this change my monthly payment? |
| Cash to close | Buyers and refinancers need a realistic closing estimate | Which costs can still change? |
| Rate lock terms | Lock length affects protection and pricing | What happens if closing is delayed? |
Match the team to your loan scenario
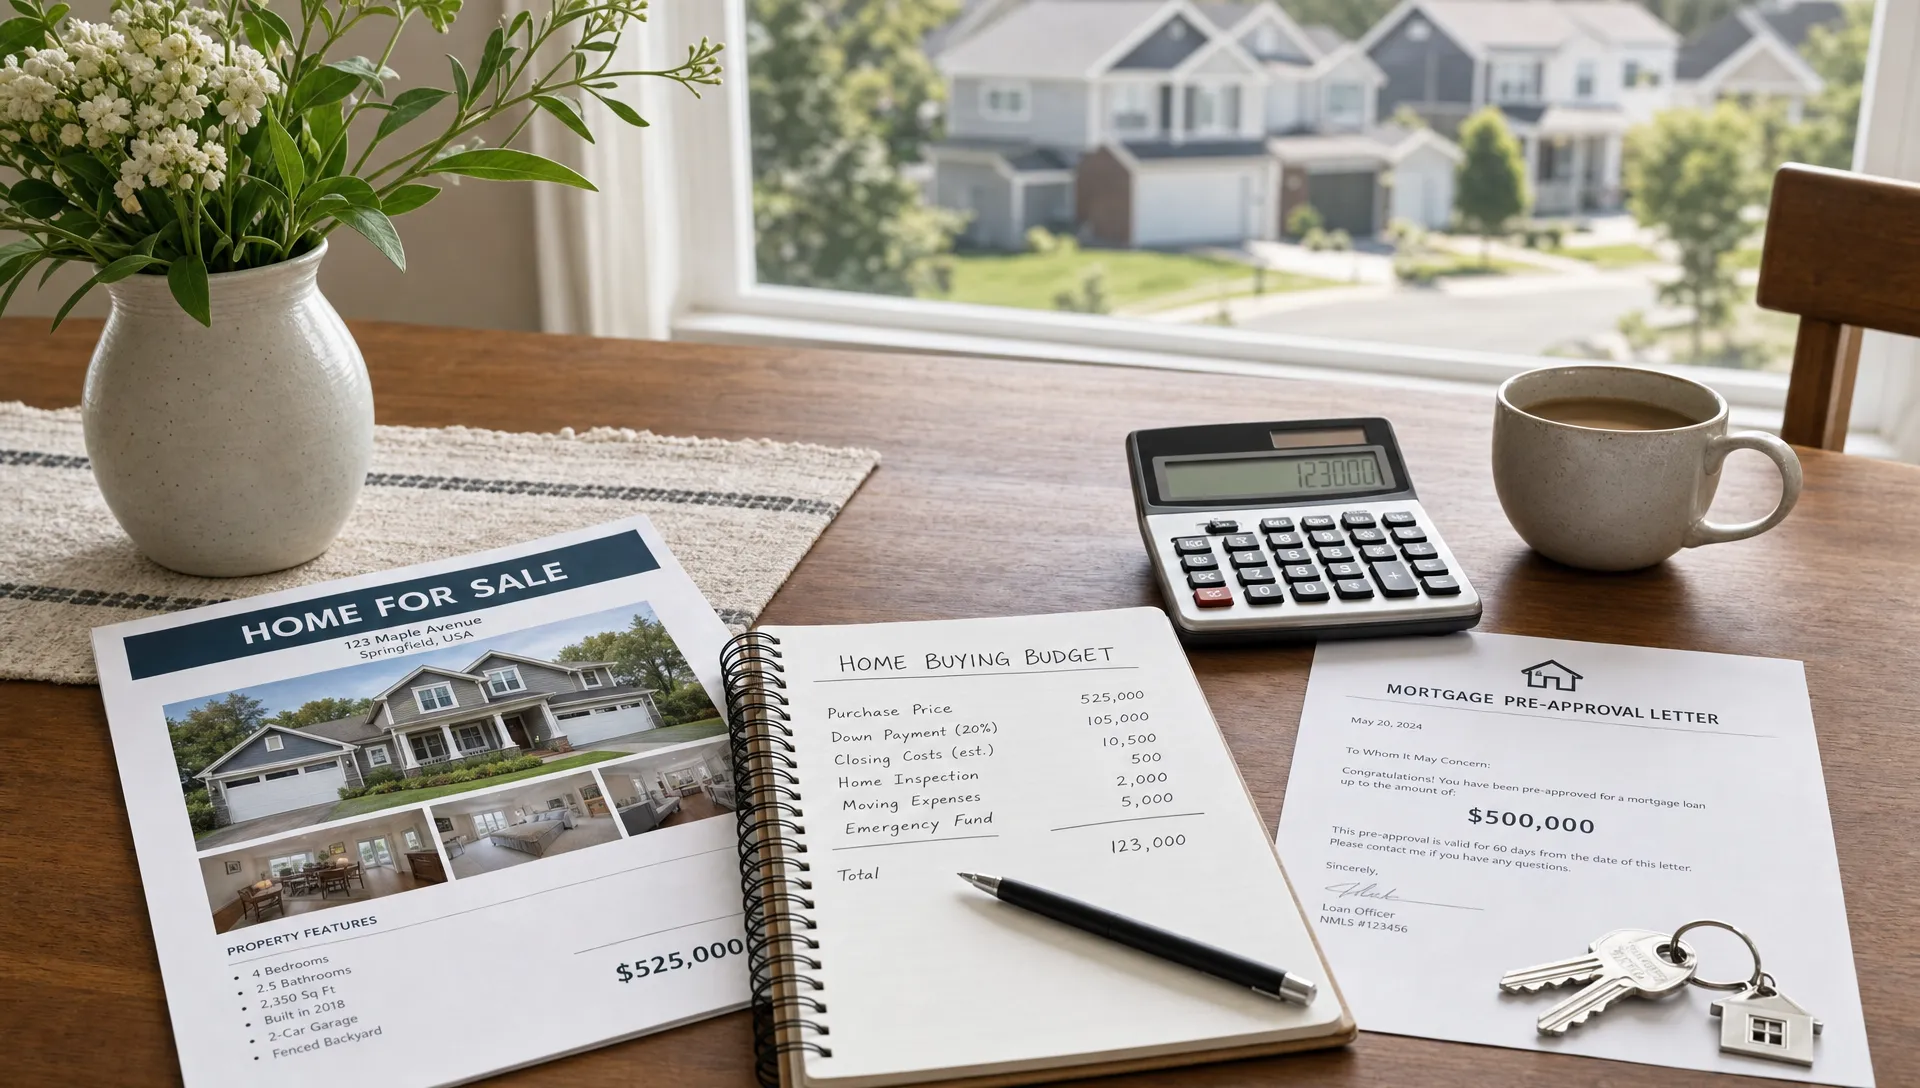
Not every borrower needs the same type of support. A first-time buyer may need more education on pre-approval, cash to close and offer strategy. A homeowner refinancing for a lower payment may need help calculating savings after closing costs. A borrower using home equity may need a clear comparison between a cash-out refinance and other equity options.
A home loan team that fits your scenario should have experience with the type of loan you are considering. If you are eligible for a VA loan, ask whether the team regularly handles veteran loan programs. If you are self-employed, ask how they review income and what documentation they expect. If the property is a condo, investment property or rural home, ask about guideline issues early.
This is not about finding someone who says they can do everything. It is about finding someone who can identify likely obstacles before you spend money on inspections, appraisals or rate locks.
Look for technology that reduces friction without removing people
Modern mortgage tools can make the process easier when they are paired with real guidance. Secure document uploads, e-signatures, clear checklists and online status updates can reduce delays and protect sensitive information. Technology is especially helpful when borrowers are busy, relocating or coordinating across different work schedules.
A modern home loan team should not hide behind automation, though. You still need people who can interpret guidelines, explain options and help you respond to underwriting conditions. The best experience combines efficient tools with human judgment.
Ask how documents are uploaded, how your information is protected and whether you can track outstanding tasks. Also ask when you should expect a live conversation. If every answer is routed through a portal and no one can explain the reasoning behind a request, the technology may be convenient for the lender but frustrating for you.
Watch for red flags before you commit
Some warning signs appear early if you know what to look for. A lender that avoids written estimates, pressures you to move before you understand costs or changes the conversation when you ask about fees may not be the right fit.
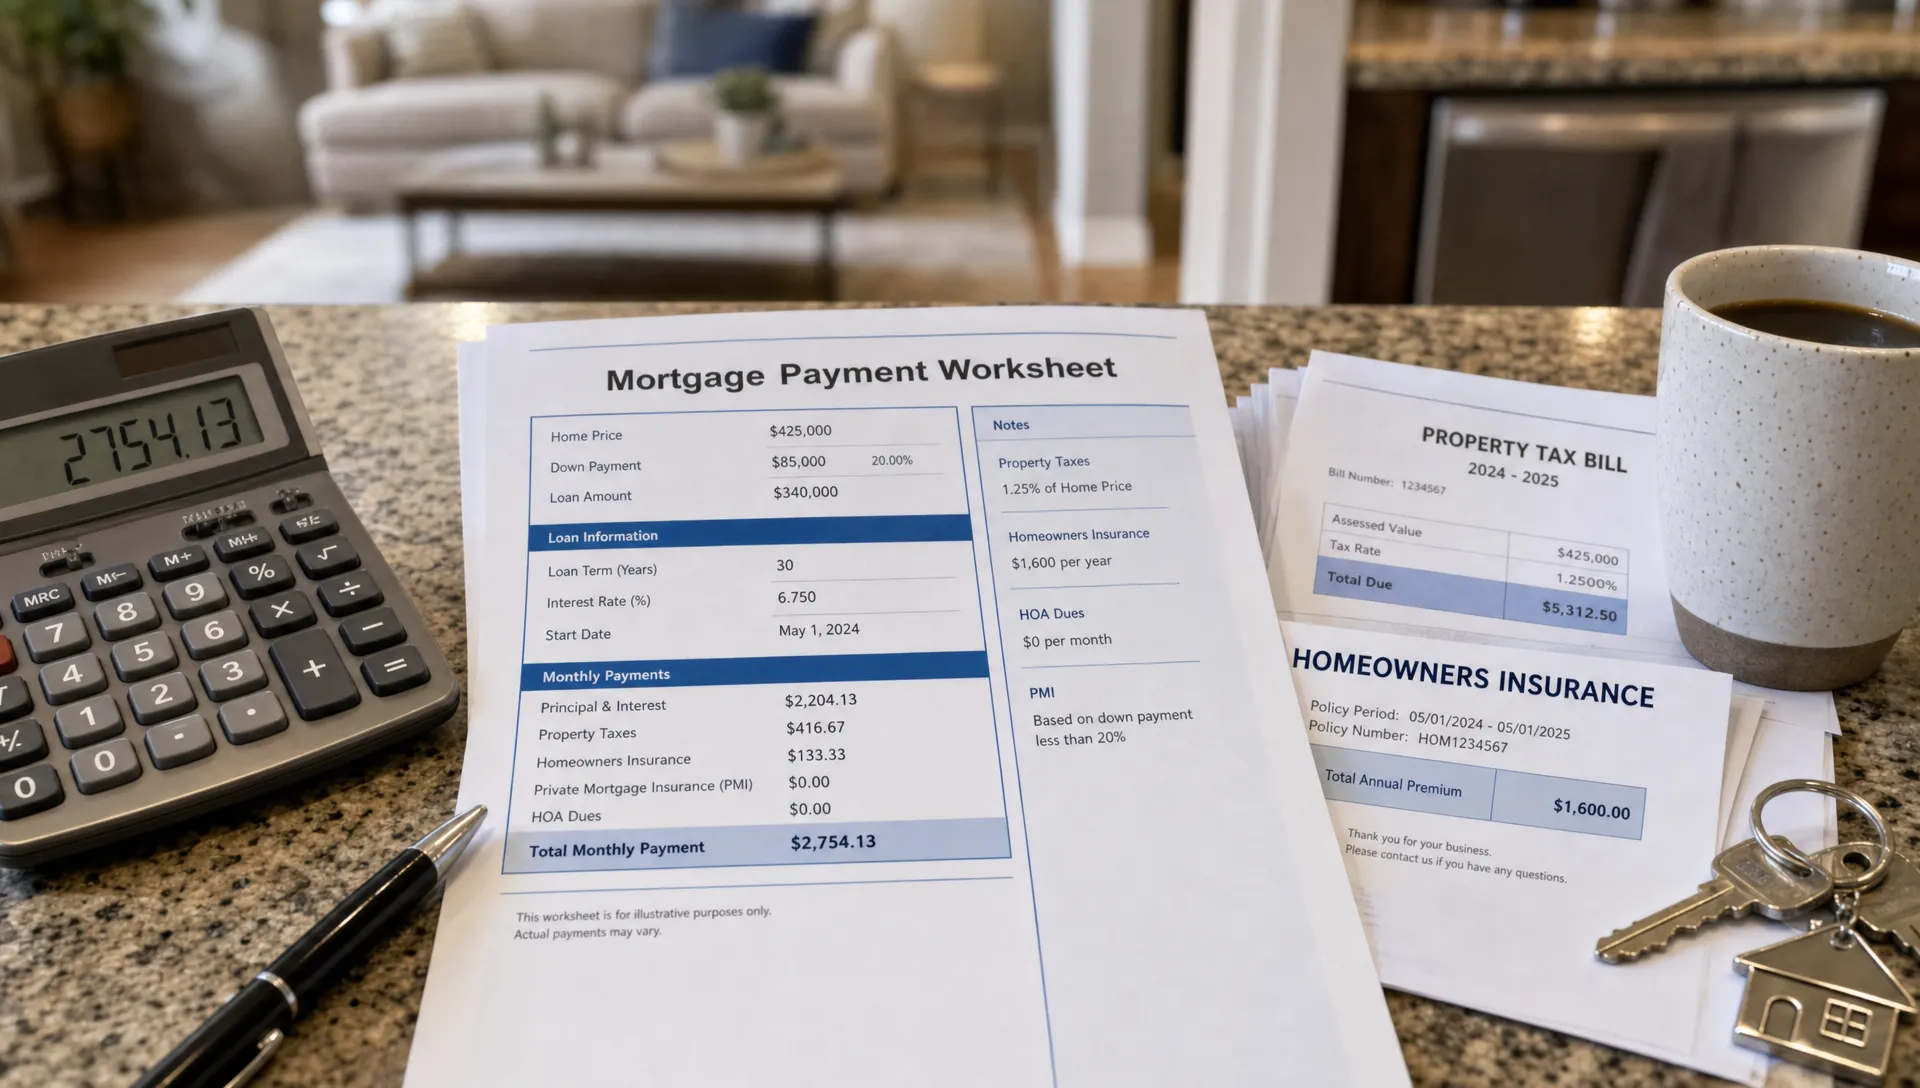
If a home loan team cannot explain why a loan is suitable for your budget, pause before moving forward. The monthly payment should be realistic, not just technically approvable. You should understand how taxes, insurance, mortgage insurance and possible HOA dues affect the full payment.
Other red flags include unclear timelines, repeated document requests for items you already provided, reluctance to discuss rate lock terms and promises that sound too absolute. No lender can control market rates or guarantee every approval. What they can do is give you a transparent process, timely updates and realistic guidance.
Questions to ask before choosing your team
A short conversation can reveal a lot about how a lender works. Bring specific questions and listen for clear, direct answers. You do not need to become a mortgage expert, but you should feel confident that the team understands your goal and can explain the path to get there.
Useful questions include:
- Which loan options fit my goal and why?
- What payment range would you consider comfortable based on my numbers?
- What documents should I gather before applying?
- How do you handle underwriting conditions?
- What fees are charged by the lender and which costs are third-party charges?
- How do you communicate with real estate agents, title companies and insurance providers?
- What could delay my closing or approval?
The answers should sound specific to you. If you hear only generic talking points, keep looking.
Frequently Asked Questions
What does a home loan team include? It usually includes a loan officer or mortgage advisor, processor, underwriter and closing support staff. You may not speak with everyone directly, but each role helps review, approve and finalize the loan.
How early should I choose a mortgage team? Ideally, before you make an offer on a home or start a refinance application. Early guidance can help you understand budget, documentation needs and potential issues before deadlines become stressful.
Should I pick the lender with the lowest rate? Not automatically. Compare the rate, APR, points, credits, fees, cash to close, lock terms and service quality. A low rate may come with higher upfront costs or assumptions that do not match your file.
How do I know if a lending team is transparent? They provide written estimates, explain costs in plain language, answer questions directly and tell you what could change. Transparency also means being honest about possible delays or documentation challenges.
Choose guidance that makes the mortgage process clearer
If you want a home loan team that combines smart mortgage tools with personal guidance, New Era Lending can help you explore purchase, refinance and equity access options with a clearer process from start to finish. The right team will not just help you apply. It will help you understand your choices, prepare with confidence and move forward with fewer surprises.
Start by sharing your goal, timeline and questions with New Era Lending, then compare your options with a team focused on making mortgage decisions simpler and more transparent.