


When to Borrow From Your Home Equity
Deciding when to borrow from your home equity is less about whether you can qualify and more about whether the new debt improves your financial position. Home equity can help pay for large, meaningful expenses, but it is not free money. Because the loan is secured by your home, the right timing depends on your purpose, repayment plan, current mortgage, cash reserves and tolerance for risk.
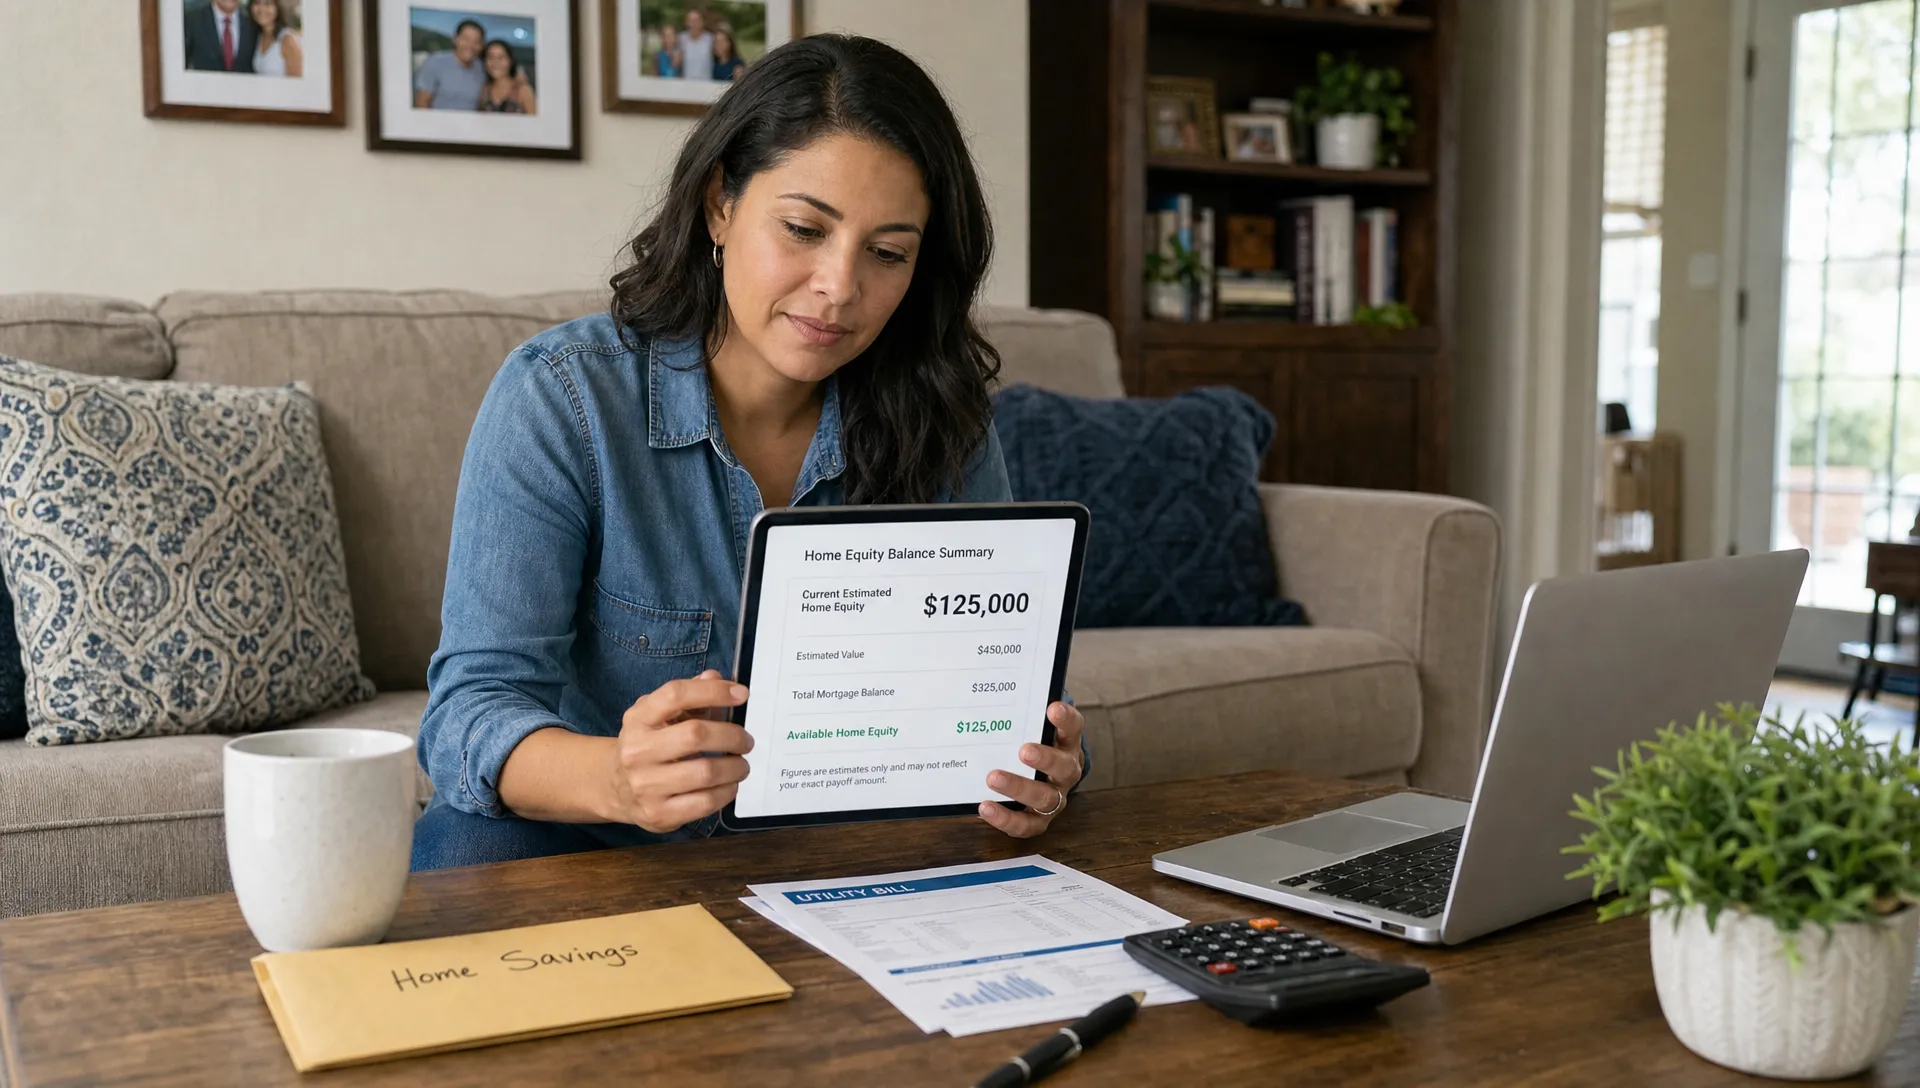
Home equity is the difference between your home's current value and the debt secured by it. If your home is worth more than you owe, you may be able to access part of that value through a home equity loan, a HELOC or a cash-out refinance. The key word is part. Lenders usually require you to keep a cushion of equity in the property, and they will also review income, credit, debt-to-income ratio and appraisal value.
When it makes sense to borrow from your home equity
The best uses for home equity usually have one thing in common: the money supports a long-term financial need rather than short-term consumption. That does not mean every use must increase your home's resale value, but it should have a clear payoff, a realistic budget and a repayment timeline you can live with.
Home improvements that protect or add value
Repairs and renovations are among the most common reasons homeowners use equity. A leaking roof, failing HVAC system, electrical update or accessibility modification can be hard to postpone. In these cases, a good time to borrow from your home equity is when delaying the work could create bigger repair costs or reduce your home's usability.
Value-adding projects can also make sense, but avoid assuming every improvement will return dollar for dollar at resale. A kitchen refresh, added bathroom or energy upgrade may improve comfort and market appeal, yet local demand, project quality and total cost matter. Before borrowing, get multiple estimates, build in a contingency and decide whether the project is essential, strategic or mostly cosmetic.
Consolidating higher-interest debt with discipline
Home equity may offer a lower rate than credit cards or unsecured personal loans, which can make debt consolidation tempting. The math can work when the new payment is lower, the repayment term is not stretched too far and you stop adding new balances to the accounts you just paid off.
You may borrow from your home equity to consolidate expensive debt, but only if you treat it as a reset with rules. Without a spending plan, you could turn unsecured debt into debt secured by your home and still run up new credit card balances. That is a worse position, even if the first monthly payment looks easier.
If your main goal is to access funds while keeping the payment manageable, New Era Lending's guide on how to access equity without hurting your budget offers a useful budgeting lens before you apply.
Major necessary expenses with limited alternatives
Some life costs are too large for a monthly budget but too important to ignore. Medical care, dental treatment, urgent family needs or education expenses may lead a homeowner to compare home equity financing with savings, payment plans or unsecured loans.
It can be reasonable to borrow from your home equity for a major necessary expense when you have exhausted safer options and understand the full cost. For medical, dental or orthodontic care, compare provider financing and payment plans first. A provider that shares transparent pricing and payment plan details can help you compare treatment financing against the risks of securing the cost with your home.
Investing in income or career stability
Equity can sometimes support a practical career move, such as licensing, training, equipment for a stable trade or a relocation that improves household income. This is not the same as borrowing for speculative investments. The stronger the link between the expense and reliable future income, the easier it is to justify.
A conservative test is simple: if the investment takes longer to pay off than expected, can you still afford the loan? If the answer is no, the timing is probably too aggressive.
Choosing the right way to use home equity
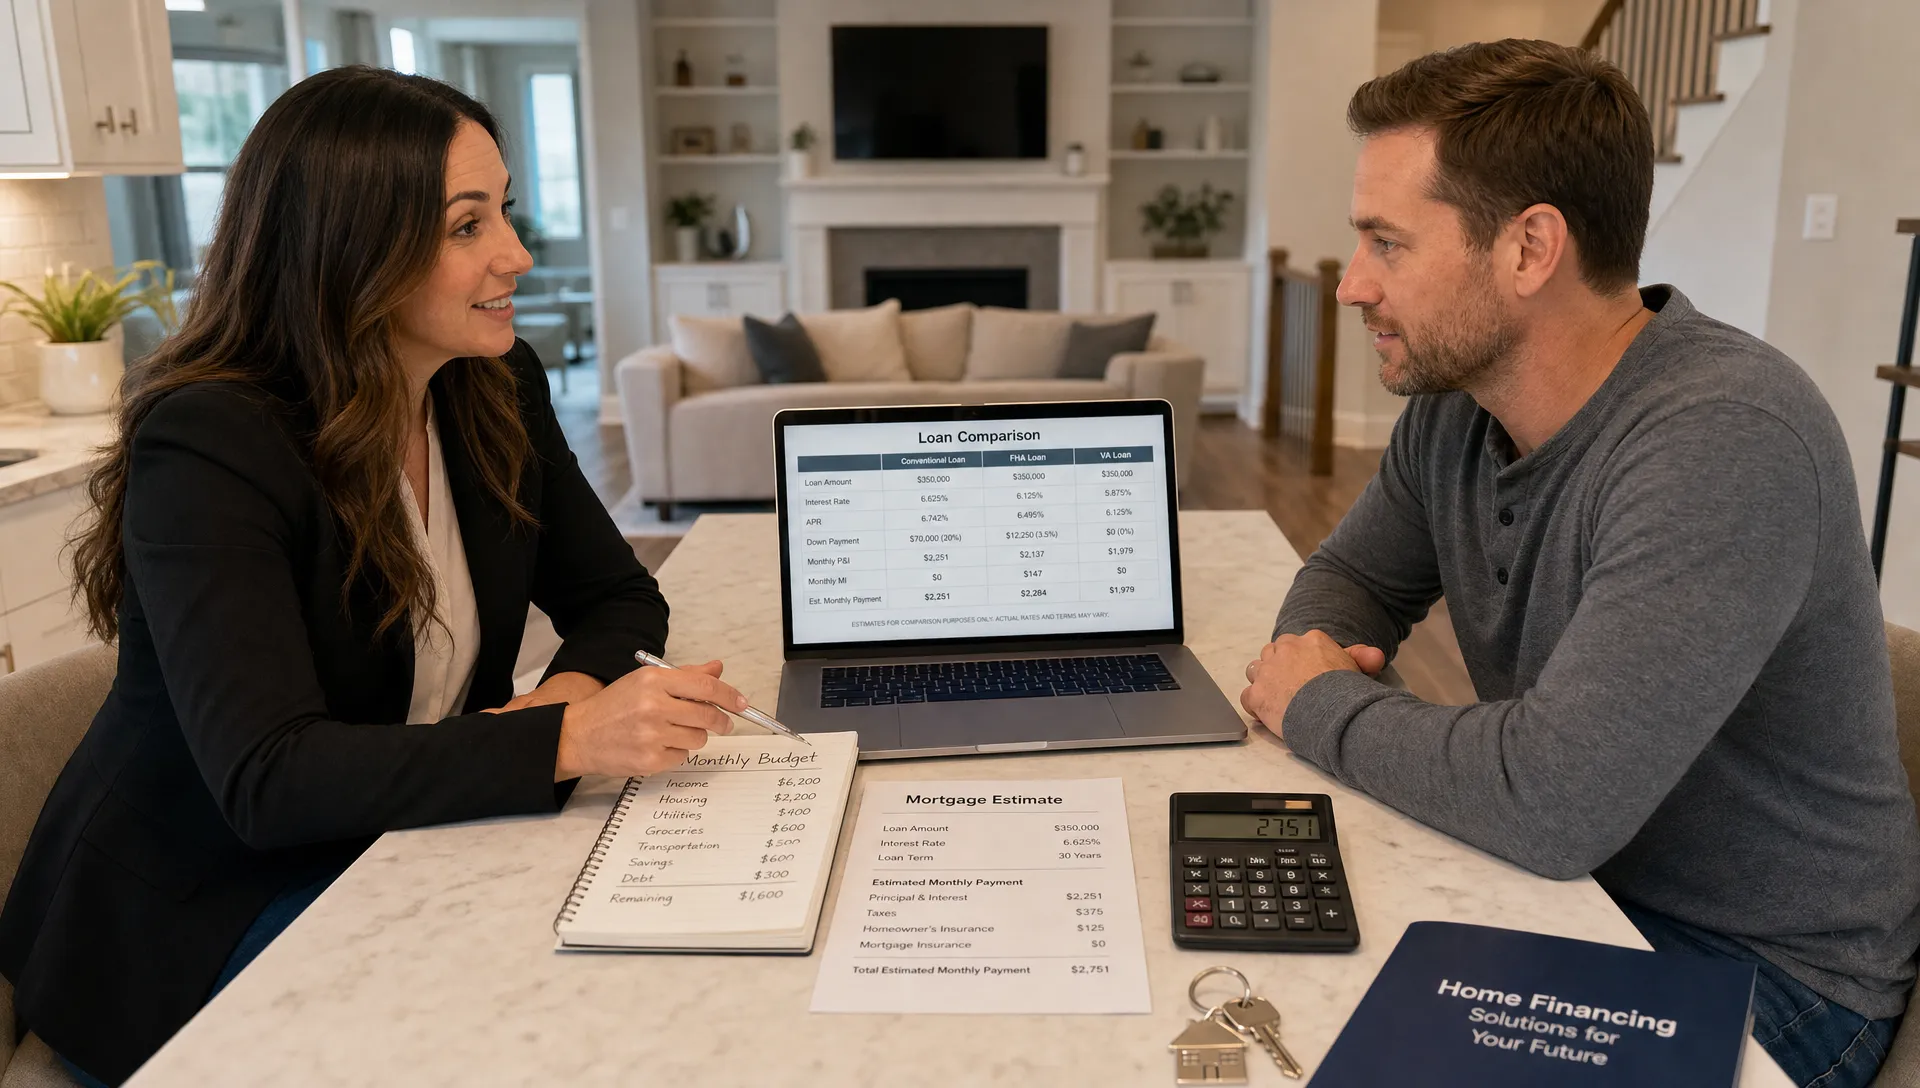
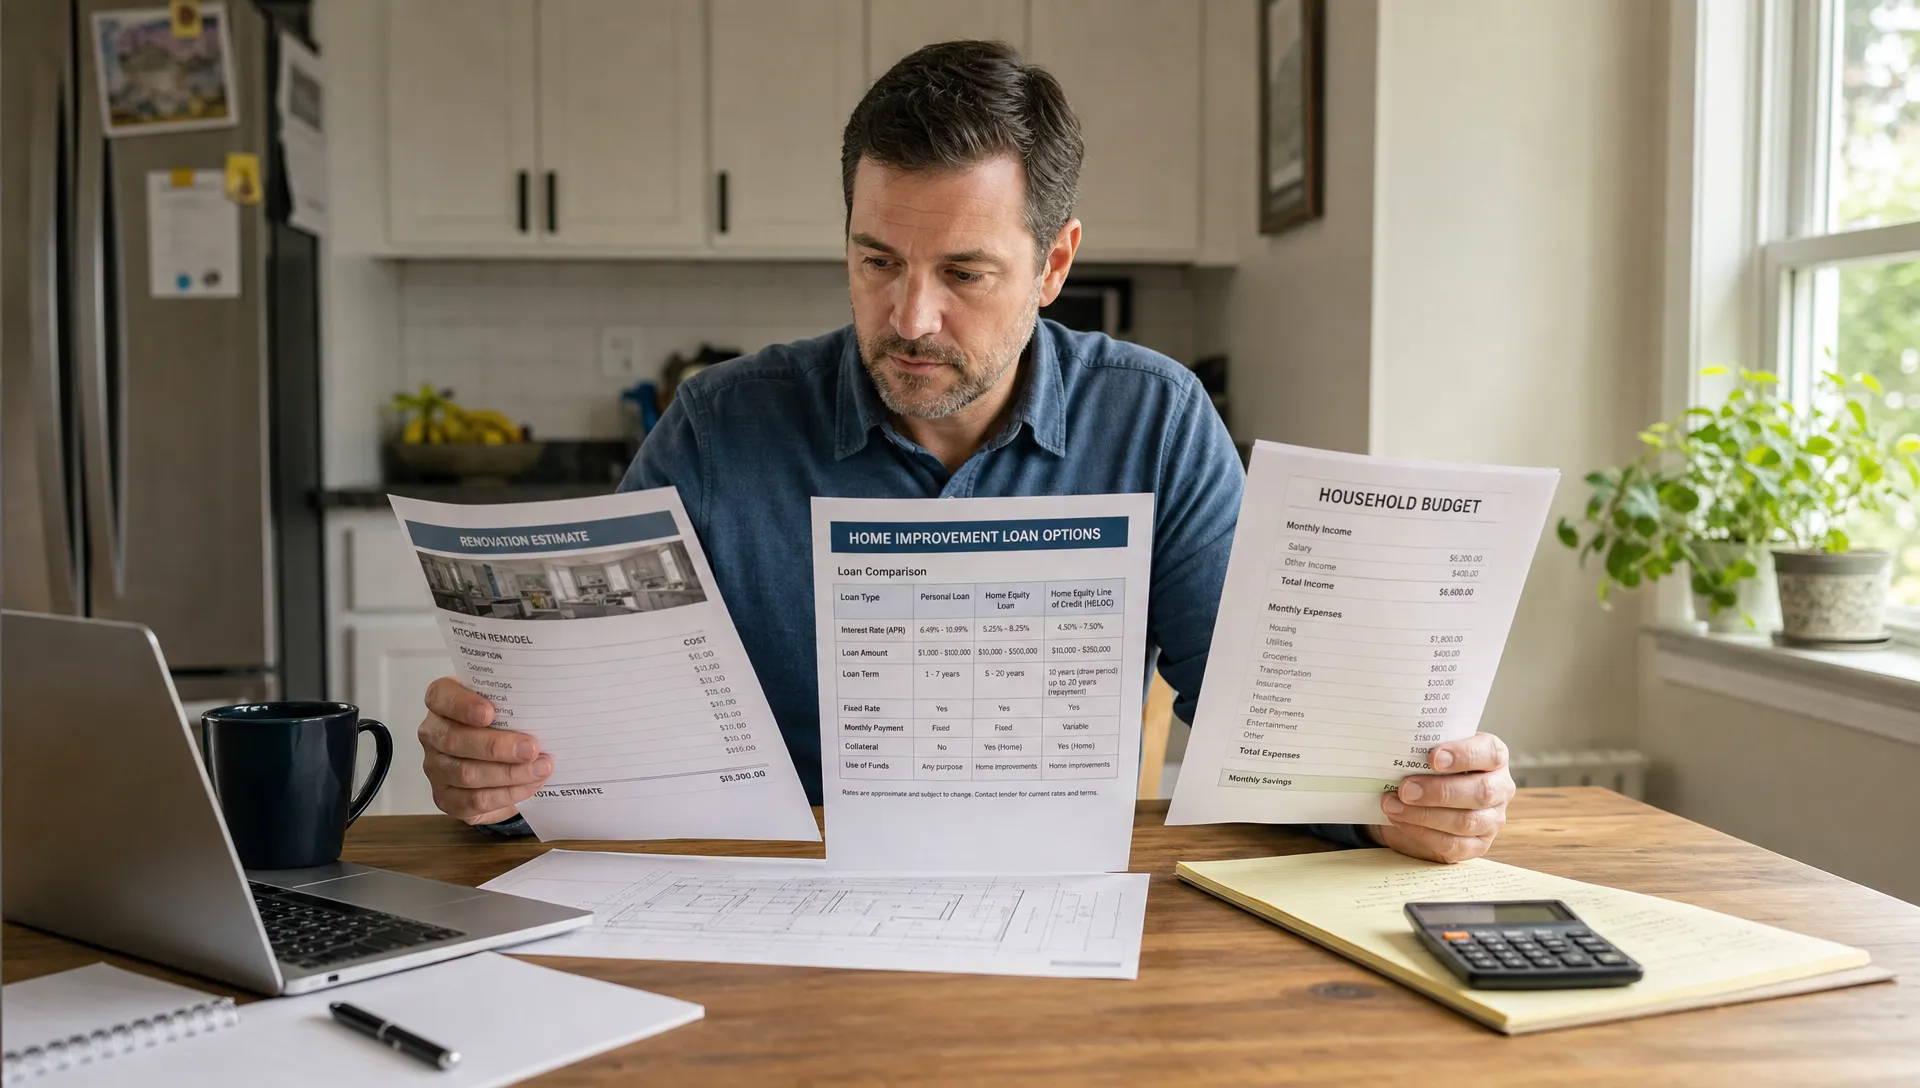
If you plan to borrow from your home equity, the loan structure matters as much as the reason. A fixed loan can be helpful when you know the exact amount you need. A line of credit can fit phased expenses. A refinance may work if replacing your current mortgage also makes sense.
| Option | Often fits best when | Main tradeoff |
|---|---|---|
| Home equity loan | You need a lump sum and want predictable payments | You borrow the full amount upfront |
| HELOC | You need flexible access over time | Payments may change if the rate is variable |
| Cash-out refinance | You want to replace your current mortgage and take cash out | You may reset the term or change your existing rate |
A home equity loan is often simpler for a one-time project with a fixed contractor estimate. A HELOC can be useful when costs will arrive in stages, such as ongoing repairs or tuition payments. A cash-out refinance deserves extra care because it changes your primary mortgage, not just the borrowed cash portion.
If you are comparing structures, the breakdown of cash-out mortgage loans versus HELOCs can help you match the product to the purpose instead of choosing based on the lowest advertised payment.
Timing signs that you are ready
Before you borrow from your home equity, look beyond the available equity number. Approval does not mean the loan is comfortable. A lender may qualify you based on guidelines, but your household budget needs its own stress test.
Strong timing usually includes a stable income, adequate emergency savings, manageable existing debt and a clear plan for the funds. You should know how much you need, why you need it, what payment you can handle and how the loan ends. If the expense is vague, the budget is unfinished or your income is uncertain, waiting may be smarter.
Use this checklist before moving forward:
- The purpose is specific and important, not impulsive.
- The monthly payment fits even if insurance, taxes or utilities rise.
- You have compared a home equity loan, HELOC, refinance, savings and unsecured financing.
- You understand closing costs, rate type, repayment term and prepayment rules.
- You are not draining all usable equity and leaving no cushion for emergencies.
Taxes are another timing issue. In the United States, home equity interest may be deductible only when the funds are used to buy, build or substantially improve the home securing the loan, subject to IRS rules and limits. If tax treatment affects your decision, ask a tax professional before borrowing.
For a deeper look at safe borrowing limits, see New Era Lending's article on how to access your home equity without overborrowing.
When not to use home equity
Do not borrow from your home equity simply because the funds are available. Using secured debt for vacations, luxury purchases, routine shopping or short-lived items can leave you paying for something long after the benefit is gone. The same caution applies to lending money to others, trying to rescue a failing business or investing in volatile assets.
The biggest risk is not just a higher payment. It is the fact that your home is collateral. If your financial situation changes and you cannot keep up, missed payments can damage your credit and may ultimately put the property at risk.
Borrowing can also backfire when your current first mortgage has unusually favorable terms. A cash-out refinance that replaces a low-rate mortgage with a higher-rate one may cost more over time than a smaller second mortgage, even if the cash-out option looks clean on paper.
Another warning sign is using equity to avoid a budget conversation. If the loan only covers a monthly shortfall without reducing expenses or increasing income, it may delay the problem rather than solve it.
A simple decision framework
The safest way to evaluate home equity borrowing is to start with the outcome, not the loan. What will be better 12, 36 or 60 months after the debt is added? If the answer is unclear, keep working on the plan.
A good decision usually passes three tests. First, the use of funds is valuable enough to justify secured debt. Second, the monthly payment remains affordable under realistic conditions. Third, the loan structure matches the expense. A one-time roof replacement, phased remodel and full mortgage refinance are different situations, so they should not automatically use the same product.
It is also worth asking what happens if home values decline or you need to sell sooner than expected. Keeping some equity untouched can give you flexibility for a future move, emergency repair or refinance opportunity.
Frequently Asked Questions
How much equity do I need before borrowing? Lenders look at your loan-to-value or combined loan-to-value ratio, along with income, credit and debt. The exact amount you can access depends on the program and your financial profile, so usable equity is usually less than total equity.
Is it better to use a HELOC or a home equity loan? A HELOC may fit flexible or phased expenses, while a home equity loan may fit a known one-time cost. The better choice depends on rate structure, payment stability, fees and how you plan to use the funds.
Can I use home equity to pay off credit cards? Yes, but it is only wise if the total cost is lower and you avoid rebuilding card balances. You are converting unsecured debt into debt secured by your home, so discipline matters.
What is the safest time to borrow from your home equity? The safest time is when your income is stable, the purpose is clear, your emergency fund is intact and the new payment fits your budget after stress testing.
Talk through your options before you borrow
If you are deciding whether to borrow from your home equity, compare the numbers before you commit. New Era Lending combines smart mortgage technology with human guidance to help homeowners review purchase, refinance and equity access options with clearer expectations around rates, terms and documentation.
You do not have to choose a loan structure on your own. A conversation with a knowledgeable mortgage professional can help you weigh a home equity loan, HELOC or cash-out refinance against your budget and long-term goals.