


How a Mortgage Rate in New Mexico Is Set
Most New Mexico borrowers first see a rate as one number, but that number is the final output of several pricing layers. If you searched for 'mortgage rate new mexico,' you are probably comparing offers for a purchase, refinance or cash-out loan and wondering why one quote differs from another. Your rate starts in national capital markets, then gets adjusted for your loan program, credit profile, property details and lock timing.
The process is not random, and it is not set by the state government. A lender cannot control the whole market, but it can price risk, costs and service differently. Understanding those layers helps you compare quotes with more confidence, especially when you are deciding whether to lock, float or ask for a revised offer.
mortgage rate new mexico: start with the national market
New Mexico mortgage rates begin in the same place as rates in every other state: the bond market. Most long-term fixed mortgage pricing is closely tied to mortgage-backed securities, which are bonds backed by pools of home loans. When investors demand higher returns for those bonds, lenders generally have to offer higher rates to borrowers. When demand improves, rates can ease.
Treasury yields matter too, especially the 10-year Treasury, because investors often compare mortgage-backed securities against government bonds. The relationship is not one-to-one, but it is a useful signal. Freddie Mac publishes the widely followed Primary Mortgage Market Survey, which tracks average weekly mortgage rates and shows how quickly national pricing can shift.
That is why a mortgage rate new mexico quote can move even when your income, credit and property have not changed. The market price of mortgage money may have changed overnight, or even during the same day if bond prices move sharply.
For broader background on this chain, New Era Lending also explains how home mortgage lending rates are set, including the path from capital markets to lender rate sheets.
How lenders turn market pricing into a rate sheet
After the market sets the baseline, each lender translates that pricing into a daily rate sheet. A rate sheet is not just a list of interest rates. It also reflects the lender's operating costs, investor relationships, servicing strategy, appetite for certain loan types and the price of delivering loans into the secondary market.
Two lenders can look at the same national market and still quote different rates. One may be more competitive on conventional loans, while another may price government-backed loans more aggressively. One may offer a lower rate with higher upfront costs, while another may offer a slightly higher rate with lender credits that reduce cash needed at closing.
This is why the lowest advertised number is not always the best deal. The real comparison is the full structure: rate, APR, discount points, lender credits, fees, lock period, loan program and cash to close. If you are comparing offers today, New Era Lending's guide to new mortgage rates and how to compare offers can help you look beyond the headline rate.
Your borrower profile changes the final quote
By the time a mortgage rate new mexico offer reaches you, your file has been priced through borrower-level adjustments. These adjustments do not mean a lender is guessing. They reflect how investors and loan programs evaluate the risk and structure of the loan.
The biggest personal factors usually include credit score, down payment or available equity, debt-to-income ratio, loan purpose and occupancy. A purchase loan may price differently from a rate-and-term refinance. A cash-out refinance often carries different pricing because the borrower is increasing the loan balance or drawing equity from the home.
| Factor | Why it matters for pricing | What borrowers can review |
|---|---|---|
| Credit score | Higher scores often qualify for more favorable pricing tiers | Check reports early and resolve errors before applying |
| Down payment or equity | More equity can reduce lender risk | Compare scenarios with different down payments if possible |
| Debt-to-income ratio | Lower monthly obligations can strengthen the file | Pay attention to installment loans, cards and proposed housing payment |
| Loan purpose | Purchase, refinance and cash-out loans can price differently | Ask for quotes based on the exact loan purpose |
| Occupancy | Primary residences, second homes and investment properties are priced differently | Be clear about how the property will be used |
| Loan program | Conventional, FHA, VA and USDA loans follow different rules | Compare program costs, not just the rate |
A stronger file does not guarantee the lowest rate in the market, but it can improve the range of options available to you. Small changes, such as lowering card balances before a credit refresh or choosing a different loan structure, may affect the final offer.
New Mexico property details that can affect pricing and approval
A mortgage rate new mexico lender quotes is not higher or lower simply because the property is in the state. The location matters because it can influence eligibility, property type, escrow costs and underwriting details.
For example, an Albuquerque single-family home, a Santa Fe second home, a rural property outside a metro area and a manufactured home can each raise different questions for a lender. Some rural properties may be worth checking for USDA eligibility, while eligible service members and veterans may compare VA loan options. Condominiums, multi-unit homes and properties with acreage can also require extra review.
Property taxes and homeowner's insurance usually do not directly set the note rate, but they affect the monthly payment. That matters because the total payment feeds into the debt-to-income ratio. In parts of New Mexico where insurance, flood considerations or wildfire risk are more relevant, the escrow estimate can become a meaningful part of affordability.
Points, APR and lender credits change what the rate really costs
A quoted interest rate only tells you the cost of borrowing the principal balance over time. It does not tell you whether you paid extra upfront to get that rate, whether the lender is giving you a credit or how the full cost compares to another offer.
Discount points are prepaid interest. In many cases, paying points can lower the rate, but it increases cash due at closing. Lender credits work in the opposite direction. You may accept a higher rate in exchange for help covering closing costs. Neither structure is automatically better. The right choice depends on cash flow, time horizon and how long you expect to keep the loan.
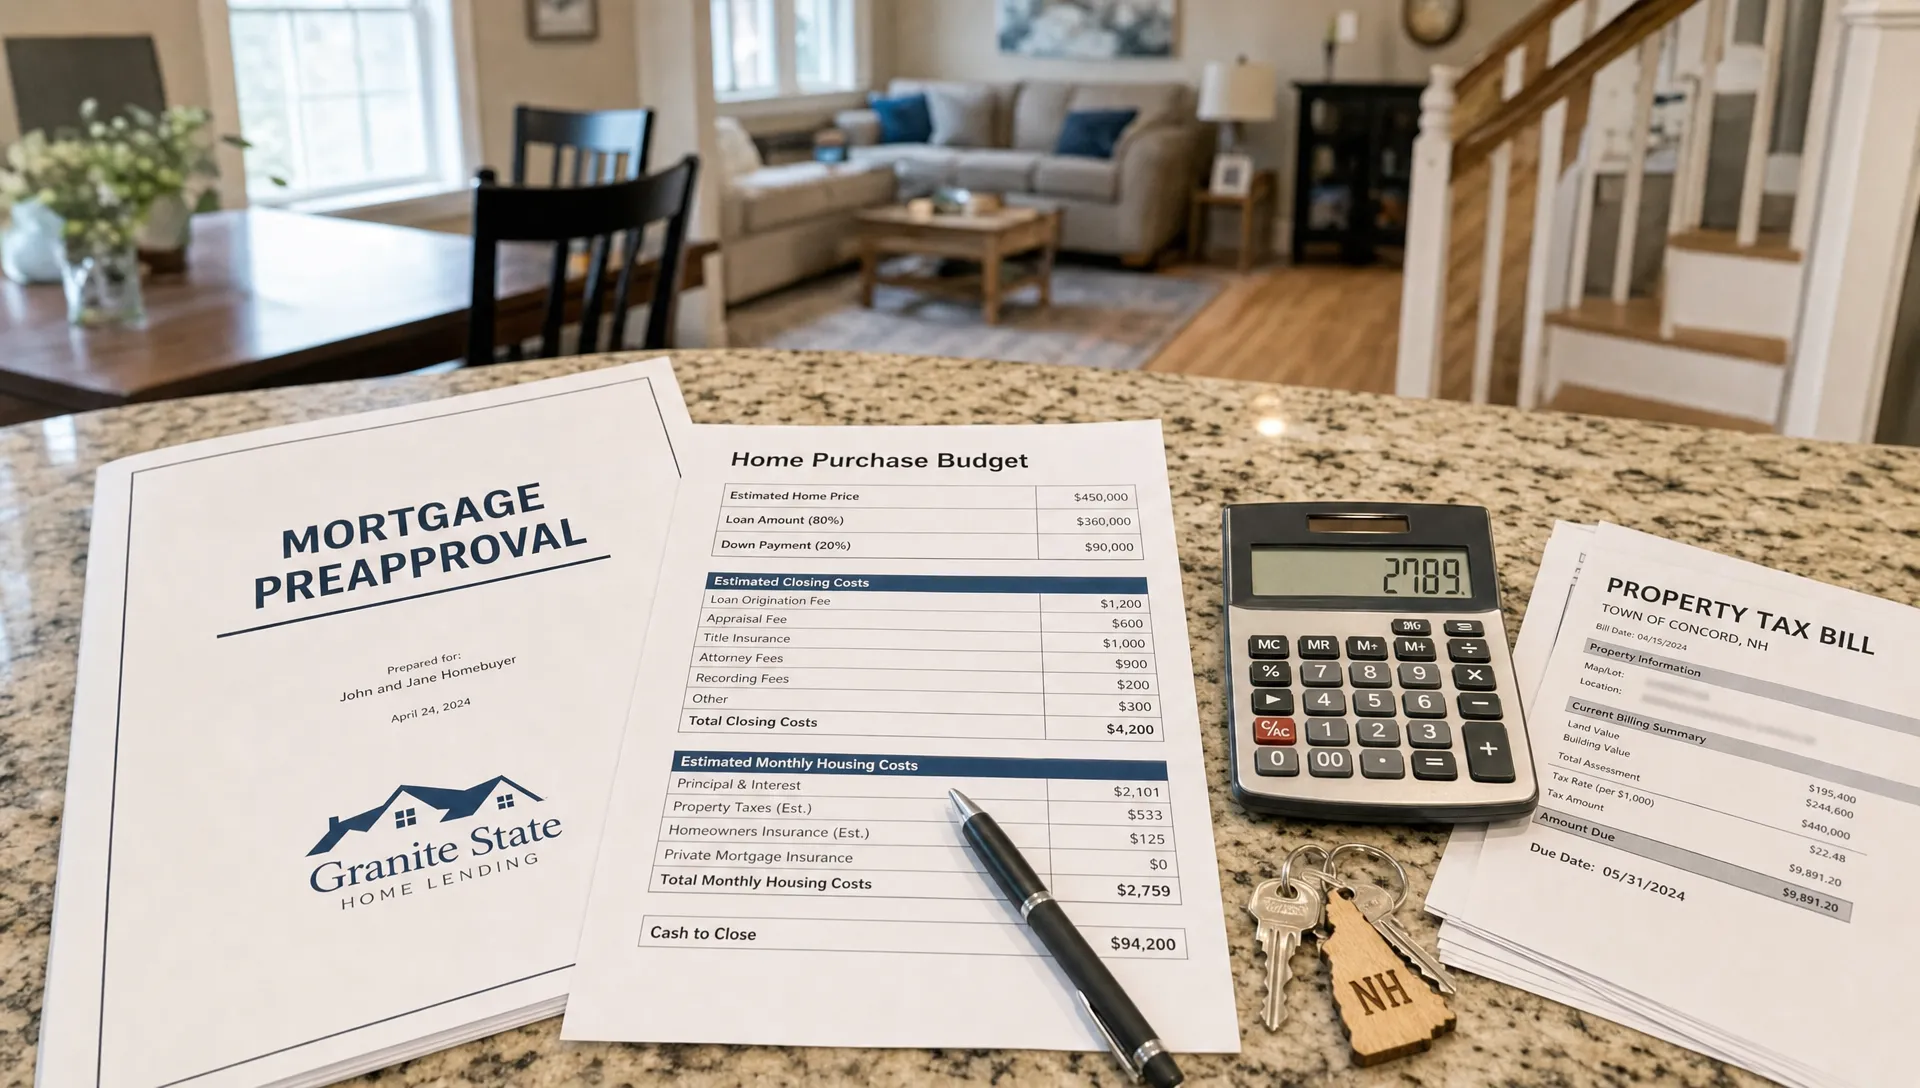
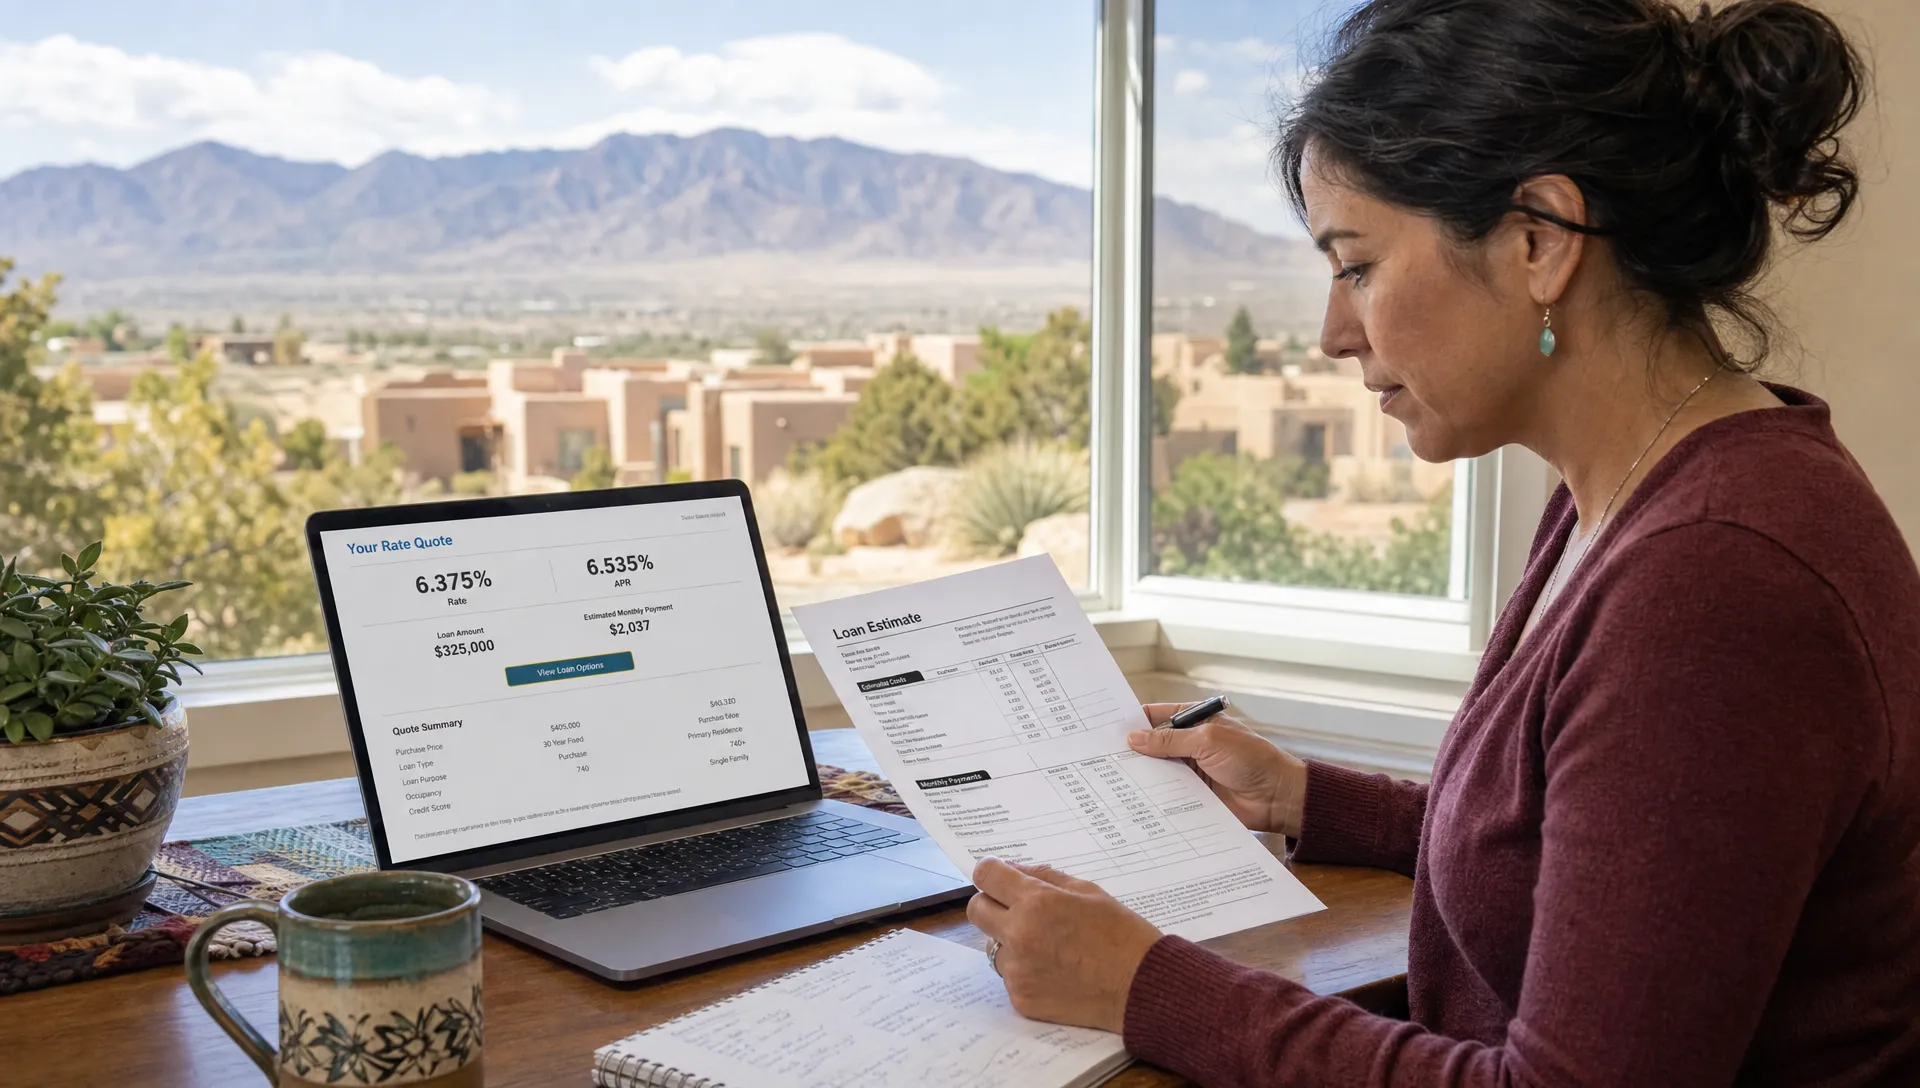
The cleanest way to evaluate a mortgage rate new mexico offer is to read it with the APR, points and cash to close on the same Loan Estimate. The Consumer Financial Protection Bureau explains the Loan Estimate as the standardized form lenders provide after application, making it easier to compare key costs across offers.
A simple rule helps: compare the same loan amount, program, term, lock period and closing date. If one quote has points and the other does not, you are not comparing equal offers yet.
Why timing and rate locks matter
Mortgage pricing can change between preapproval and closing. If you are under contract, your closing timeline matters because lenders offer different lock periods, such as shorter locks for faster closings or longer locks when more time is needed. Longer locks can cost more because the lender is taking on more market risk.
A mortgage rate new mexico lock matters because the market can move while your loan is being processed, appraised and underwritten. Locking protects you from increases during the lock period, but it can also mean you do not automatically benefit if rates fall after you lock unless your lender offers a specific float-down option. Float-down policies vary, so ask before assuming one is available.
Purchase buyers usually think about locking once they have a signed contract and a realistic closing date. Refinance borrowers may have more flexibility, but they still need to consider appraisal timing, document collection and how long the quoted pricing will be available. New Era Lending's article on when to lock your rate explains the tradeoff between locking and floating in more detail.
How to improve your mortgage quote before you apply
You cannot control bond markets, but you can control parts of your loan file. To improve a mortgage rate new mexico offer, focus on the factors that lenders can verify and price.
Start with credit. Review your reports before applying, avoid opening new debt during the mortgage process and keep card balances manageable relative to limits. Next, look at the payment side of the file. A lower debt-to-income ratio may help your approval strength, even if it does not change every pricing tier.
Down payment strategy also matters. Sometimes a slightly larger down payment changes pricing or mortgage insurance. Other times, keeping more reserves is the smarter move. Ask your loan professional to compare scenarios instead of assuming one option is best.
You can also request side-by-side quotes with and without points. This is especially useful if you may sell, refinance or pay off the loan within a few years. A lower rate only wins if the upfront cost makes sense over your expected ownership timeline.
Frequently Asked Questions
Who sets mortgage rates in New Mexico? No single state agency sets mortgage rates in New Mexico. Rates are shaped by national bond markets, mortgage-backed securities, lender pricing and your borrower profile.
Why did my New Mexico mortgage quote change from yesterday? Your quote may change because the bond market moved, the lender repriced its rate sheet or details in your file changed. Credit, loan amount, property type, lock period and points can all affect the final offer.
Is APR more important than the interest rate? APR is useful because it includes certain loan costs, not just the interest rate. You should compare both, along with points, lender credits, fees and cash to close.
Can a VA, FHA or USDA loan have a different rate than a conventional loan? Yes. Each loan program has its own rules, investor pricing and cost structure. A lower interest rate may come with other costs, such as mortgage insurance or a funding fee, so compare the full payment and closing costs.
When should I lock my rate? Many buyers lock after they are under contract and have a clear closing timeline. Refinance borrowers may have more flexibility, but the decision still depends on market movement, processing time and lock cost.
Get a clearer New Mexico mortgage quote
A mortgage rate is not just a number pulled from a chart. It is the result of market pricing, lender strategy, your loan profile, property details and timing. Once you understand those layers, it becomes easier to ask the right questions and compare offers on equal terms.
If you are buying, refinancing or accessing home equity, New Era Lending combines smart mortgage technology with personalized human guidance to help make the process clearer. You can review options, upload documents securely and work with a team that explains the tradeoffs behind the rate instead of leaving you to decode the quote alone.