


Home Ownership Loans: Which Programs May Fit Your Goals?
Choosing home ownership loans starts with a question that a rate quote cannot answer: what do you need financing to help you accomplish? You might want to buy without draining your savings, use earned military benefits or secure a payment that remains manageable for years. Different mortgage programs support those goals in different ways, and an attractive benefit can come with costs or restrictions elsewhere.
The useful comparison is not simply which program lets you qualify. It is which program addresses your biggest obstacle while supporting the kind of homeowner you want to be.
Define what successful ownership looks like for you
Before comparing programs, identify your primary goal and the constraint most likely to get in the way. A buyer with steady income but limited savings faces a different decision from someone with substantial savings and a challenging credit history.
Make your goal specific. “Buy soon” is less useful than “buy while keeping three months of essential expenses in reserve.” Likewise, “get the lowest payment” should include whether you need predictable payments, expect to move soon or want to pay off the mortgage faster.
Separate preferences from requirements. A smaller down payment may be convenient, but keeping enough cash for an unavoidable repair may be essential. That distinction helps you evaluate benefits without overlooking their consequences.
Compare home ownership loans by the goal they support
The following programs are starting points for a conversation, not guarantees of eligibility or availability through every lender.
| Your main goal | Programs worth discussing | Tradeoff to investigate |
|---|---|---|
| Buy with limited upfront savings | Low-down-payment conventional, FHA or assistance programs | Mortgage insurance, closing costs and assistance repayment rules |
| Use eligible military benefits | VA purchase loans | Entitlement, funding fee status and property requirements |
| Buy in an eligible rural or suburban area | USDA guaranteed loans | Household income limits, location eligibility and guarantee fees |
| Benefit from stronger credit | Conventional mortgages | Pricing, down payment options and mortgage insurance cancellation |
| Purchase above conforming loan limits | Jumbo financing | Lender-specific reserve, credit and down payment requirements |
| Preserve flexibility after buying | A loan with manageable costs and limited assistance restrictions | Sale, refinance and repayment conditions |
Several options may fit the same buyer. When comparing home ownership loans, ask what each program makes easier and what it asks you to accept in return. A low-down-payment option can help you buy sooner without necessarily offering the lowest long-term cost.
Goal: Buy without using all your savings
Eligible buyers may qualify for some conventional mortgages with as little as 3% down. FHA financing can allow a down payment as low as 3.5% for qualifying borrowers, according to HUD’s FHA loan overview. Neither figure represents the entire amount needed to close.
Closing costs, prepaid expenses and the initial escrow deposit can add to your upfront needs. You also need money available after closing for moving, maintenance and unexpected expenses. Ask for an estimated cash-to-close figure rather than planning around the down payment alone.
Down payment assistance may help bridge that gap, but “assistance” does not always mean a grant. It can take the form of a repayable second mortgage, a deferred-payment loan or assistance that becomes forgivable after specific conditions are met.
Before relying on it, ask when repayment becomes due, whether interest accrues and what happens if you sell, refinance or stop occupying the property. Availability, funding and eligibility vary by program.
If preserving savings is your priority, evaluate home ownership loans alongside the obligations of any assistance you would receive. Keeping cash today is valuable, but a repayment requirement tied to a future move could limit your options later.
Goal: Turn stronger credit into better long-term value
Conventional financing deserves a close look when your credit profile is strong. It may offer favorable pricing, and private mortgage insurance, or PMI, can often be removed once applicable equity and other requirements are met.
That does not mean conventional financing automatically beats FHA. Compare actual offers using the same purchase price, down payment and loan term. A lower interest rate may be offset by higher mortgage insurance costs or fees.
FHA loans generally include both upfront and annual mortgage insurance. On many FHA loans, annual mortgage insurance remains for the loan term, so reaching 20% equity does not necessarily remove it. Conventional PMI follows different cancellation rules.
For someone expecting to keep the mortgage for many years, that distinction can matter more than a small difference in the initial payment. Compare home ownership loans over the period you realistically expect to hold the loan, rather than assuming future refinancing will eliminate costs. Refinancing requires a new approval and can involve additional expenses.
Goal: Use your military benefits effectively
Eligible veterans, service members and certain surviving spouses may qualify for VA purchase financing. The VA’s purchase-loan guidance explains that qualifying loans can offer no down payment and no monthly mortgage insurance.
A Certificate of Eligibility establishes benefit eligibility, but it does not replace the lender’s credit, income and underwriting review. A down payment can also be necessary in some circumstances, including when the purchase price exceeds the appraised value.
Some borrowers owe a VA funding fee, while others qualify for an exemption. If the fee is financed, it increases the loan balance even though it reduces the cash needed upfront.
For eligible military buyers, compare home ownership loans using both the benefits and the complete cost picture. A VA loan is worth evaluating, but comparing it with a conventional offer can still be useful. New Era Lending’s guide to choosing a home loan as a veteran explores that decision in more detail.
Goal: Buy in an eligible community with little upfront cash
USDA guaranteed loans can offer no-down-payment financing to eligible borrowers purchasing qualifying primary residences. The program is not limited to farms, and some communities that feel suburban may qualify.
Eligibility depends on the property location, household income and other program requirements. Check the exact address and applicable income rules rather than assuming that a town’s appearance or distance from a city determines eligibility. The USDA’s guaranteed loan program overview explains the program’s basic requirements.
USDA guaranteed loans have upfront and annual guarantee fees. No down payment also does not mean no closing costs, although permitted financing arrangements, seller contributions or assistance may help in some situations.
When location is flexible, USDA can broaden the home ownership loans worth considering. When the property location is nonnegotiable, confirm eligibility early so you do not build your purchase plan around a program that cannot finance that address.
Make sure the program fits your income and property
A program can match your financial goal yet still be unsuitable for your income documentation or the home itself.
Self-employed buyers, commission earners and borrowers with variable income should ask how qualifying income will be calculated. A recent increase in earnings does not necessarily translate into the same increase in mortgage eligibility. Documentation, business expenses and the consistency of income can affect the result.
Property requirements deserve equal attention. Condominiums, manufactured homes, multi-unit properties and homes needing substantial repairs may involve additional rules. A borrower’s preapproval does not guarantee that every property will qualify.
New Era Lending’s explanation of property financing by home type and goal can help you identify questions to raise before making an offer.
The practical shortlist of home ownership loans should therefore pass two tests: can the lender document your ability to repay, and can the chosen program finance the property you intend to buy?
Compare offers around the same ownership plan
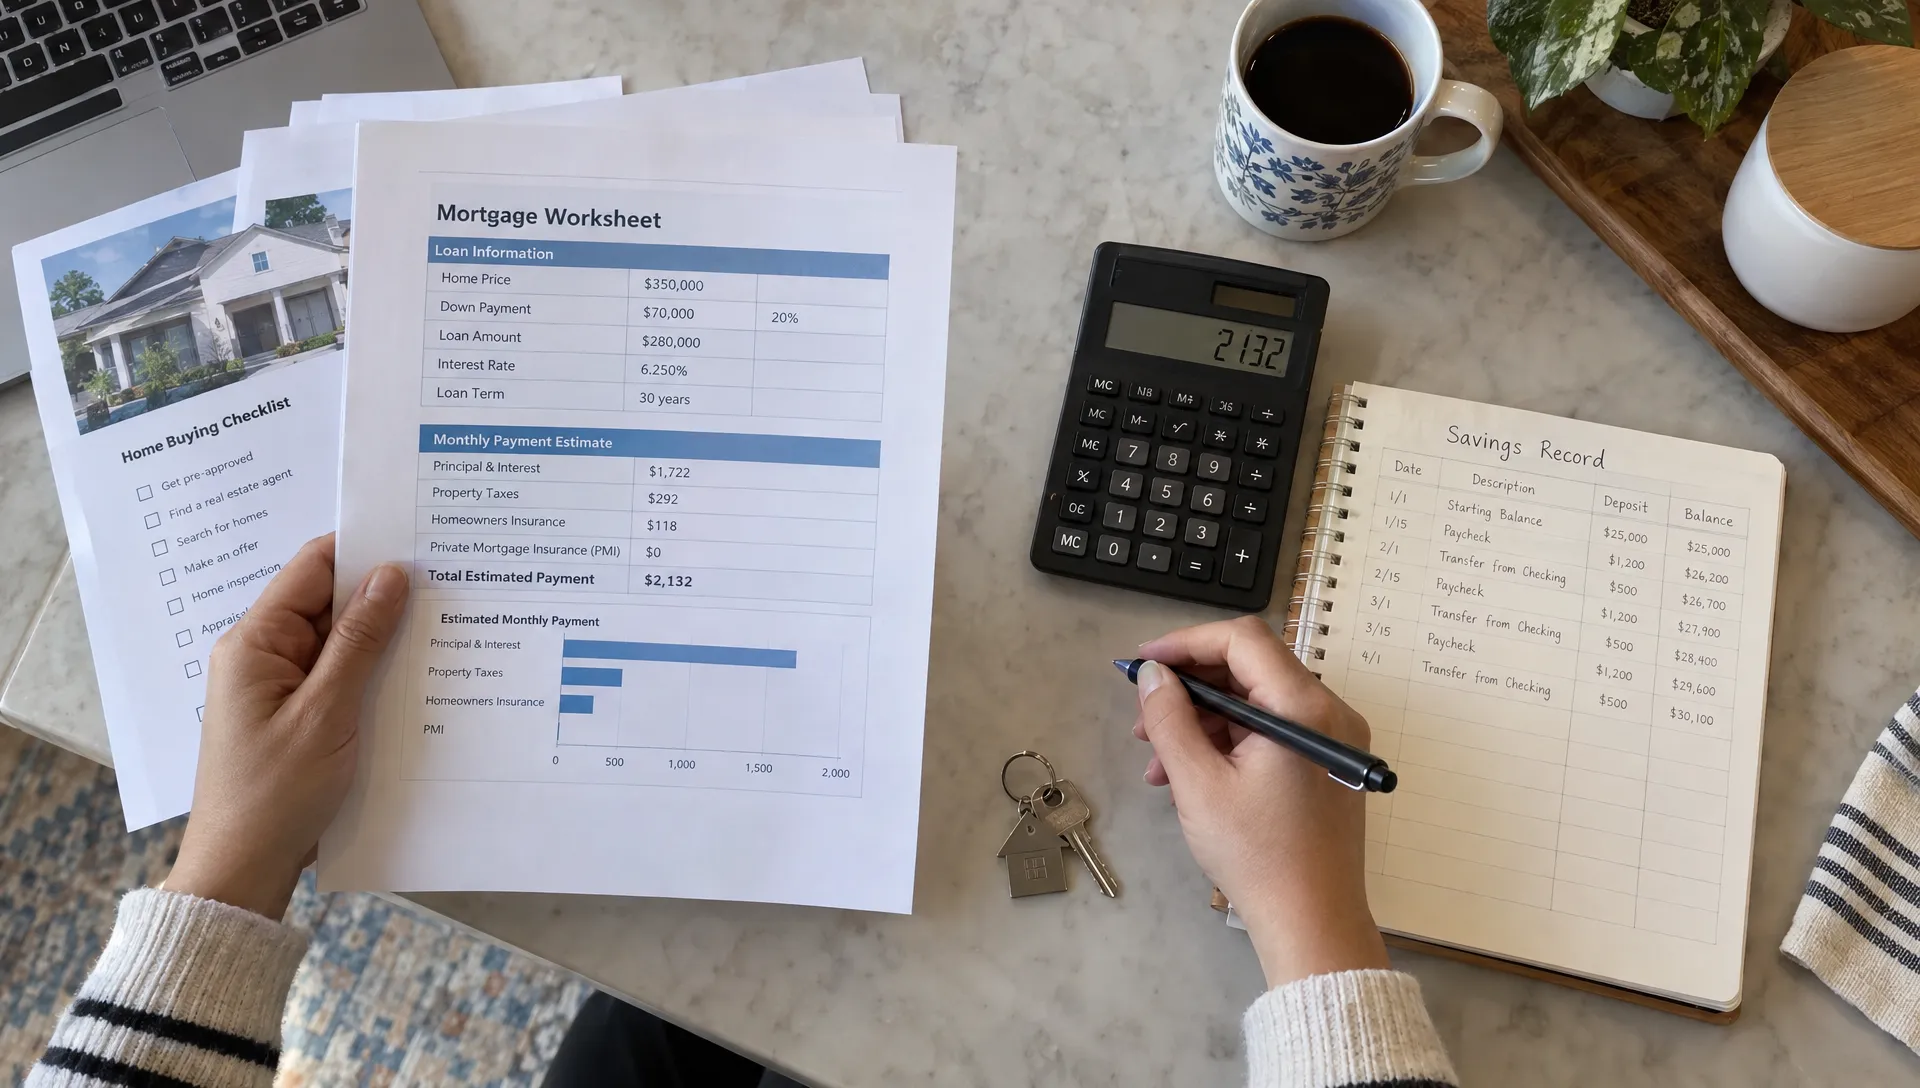
Once you have a shortlist, request comparable scenarios. An offer with a larger down payment or expensive discount points should not be presented as directly equivalent to one that preserves more cash.
Use the same purchase price, loan term and expected down payment where possible. Then compare the official Loan Estimates. The Consumer Financial Protection Bureau’s Loan Estimate explanation shows where to find the rate, payment, closing costs and other key terms.
Focus your review on four questions:
- What must I bring to closing? Compare estimated cash to close, credits and any assistance obligations.
- What will I pay each month? Include principal, interest, mortgage insurance, estimated property taxes and homeowners insurance, plus any association dues separately.
- Which costs can change? Review adjustable-rate provisions and remember that taxes and insurance can rise even with a fixed interest rate.
- What happens if I move or refinance? Check assistance repayment triggers and other relevant restrictions.
Comparing home ownership loans this way exposes differences that a headline rate can hide. If one option requires less cash but carries higher recurring costs, decide whether that exchange serves your stated goal. Do not rely on a future raise, home-price increase or refinance to make an uncomfortable payment affordable.
Protect the household budget after closing
Mortgage approval is not a complete household budget. Lender underwriting does not account for every personal priority, such as childcare, medical expenses, retirement contributions or helping family members.
Set aside a realistic maintenance allowance and decide how much emergency cash you want to retain. The right amount depends on your household, the property’s condition and the reliability of your income. A home that needs immediate repairs may call for more available cash than a newer property with fewer known issues.
Also review recurring protection costs. Comparing health and life insurance options can help you account for household premiums and consider family protection needs alongside the new housing payment. Those policies do not replace homeowners insurance, which mortgage lenders generally require.
The strongest fit among home ownership loans is one you can sustain after ordinary life expenses are included. If the payment leaves little room for essential spending or repairs, a lower purchase price or a later purchase date may serve your ownership goal better than stretching to the maximum approved amount.
Frequently asked questions
Are homeownership programs only for first-time buyers? No. FHA, VA, USDA and conventional mortgages can be available to repeat buyers who meet their requirements. Some low-down-payment products and assistance programs have first-time-buyer conditions, so check the specific program rather than assuming all options follow the same rules.
Does a no-down-payment loan mean I need no savings? No. Closing costs, prepaid expenses, moving costs and post-closing repairs may still require cash. Contributions or assistance might reduce upfront costs, but you should confirm the complete financing arrangement and retain a suitable reserve.
Is a fixed-rate mortgage payment guaranteed never to change? The principal-and-interest payment generally stays the same on a standard fixed-rate mortgage. Your total housing payment can still change because property taxes, homeowners insurance, mortgage insurance or association dues may change.
Should I choose FHA if I qualify for conventional financing too? Compare both. Credit profile, upfront costs, mortgage insurance and your expected ownership period can change which option is more attractive. Qualification alone does not establish which loan better supports your goals.
Discuss your goal before choosing a program
Bring three things to your mortgage conversation: the cash you can comfortably use, the total monthly housing cost you can sustain and your likely ownership timeline. Those details make it easier to compare home ownership loans without getting distracted by a single advertised benefit.
New Era Lending combines smart mortgage technology with personalized human guidance for purchase, refinance and equity-access needs. Ask which programs are available for your location and circumstances, then review their costs and conditions against the ownership goal you want to achieve.