


Equity Mortgage Rates: What Affects Your Offer?
Two homeowners with similar amounts of equity can receive different equity mortgage rates. The difference may come from how much they borrow, their credit profile, whether they keep their existing mortgage or how the lender structures its fees. Even two offers for the same borrower can look very different once those details are included.
The most useful comparison is not simply the lowest advertised rate. It is the cost of borrowing the amount you need while accounting for your existing mortgage, the new payment and the risks attached to the loan. Understanding the pricing inputs helps you identify what you can change and what deserves a closer question.
Start with the loan structure
“Equity mortgage” is not one standardized product name. Borrowers may use it to describe a home equity loan, a home equity line of credit (HELOC) or a cash-out refinance. Those structures expose the lender to different risks and affect different portions of your debt.
A home equity loan commonly adds a second mortgage with a lump-sum payout and scheduled payments. A HELOC provides a credit line you can draw from under the agreement’s terms. Both can leave your existing first mortgage intact.
A cash-out refinance replaces your current mortgage with a larger one. Its new rate applies to the replacement mortgage balance, not just the extra cash you receive.
That distinction matters when comparing equity mortgage rates: a lower rate on a much larger replacement loan can cost more than a higher rate on a smaller second mortgage.
If you are still choosing between a lump sum and a credit line, our comparison of an equity mortgage loan and a HELOC explains their payment and borrowing differences. Establish the structure first, then compare pricing within that category.
How your borrowing profile changes the offer
Combined loan-to-value measures the lender’s equity cushion
For financing that sits behind an existing mortgage, lenders commonly examine the combined loan-to-value ratio, or CLTV. This compares the debt secured by the property with its appraised value.
CLTV = total debt secured by the property ÷ property value × 100
Suppose your home is valued at $500,000, your first mortgage balance is $300,000 and you request a $75,000 home equity loan. The resulting CLTV is 75%.
If the appraisal instead comes in at $450,000, the same debt produces a CLTV of approximately 83.3%. Nothing changed about your credit, but the lender now has a smaller equity cushion.
Higher CLTV can affect equity mortgage rates, eligibility or the amount a lender will approve. Ask whether a smaller request would move your application into a different pricing tier. Thresholds vary by lender and product, so a modest reduction does not automatically earn a better rate.
For a HELOC, also ask whether the lender uses the full credit limit rather than your planned initial draw when calculating its exposure.
Credit and income affect different parts of the decision
Credit history helps the lender assess repayment risk. Recent late payments, high revolving balances or other negative information may affect pricing or eligibility. The score used for a mortgage application may also differ from the score displayed in a consumer app.
Income and debt-to-income ratio address whether the payment fits your finances. A lender may consider your existing mortgage payment, other recurring debts and the proposed equity-loan obligation. HELOC qualifying-payment methods can differ from the payment you initially expect to make.
For equity mortgage rates, stronger credit can improve pricing, but additional income may primarily improve qualification rather than directly lower the quoted rate. Ask which factor is actually limiting your offer before deciding what to fix.
Paying down a credit card could help both credit utilization and monthly obligations. Paying down another debt might mainly improve debt-to-income ratio. Neither action guarantees a particular rate reduction, and updated balances may need to be reflected in the lender’s credit information.
Occupancy and property characteristics also matter
A primary residence, vacation home and investment property may have different financing rules. Property type, number of units and acceptable collateral can also affect available programs. Some lenders do not offer every equity product for every occupancy type.
If you rent out the property, ask how the lender treats rental income, vacancies and expenses. Gross rent is not necessarily the amount counted as qualifying income.
A related issue arises for self-employed property managers borrowing to expand their business. Property management marketing services may be part of an expansion budget, but expected leads or future contracts are not a substitute for documented qualifying earnings. Ask how the lender calculates your business income, and evaluate expansion risk separately: debt secured by your home still needs to be repaid if the business plan underperforms.
Why equity mortgage rates move with markets and lender pricing
Your financial profile can remain unchanged while available pricing moves. Fixed-rate loans reflect funding costs, market conditions and lender pricing decisions. Variable-rate HELOCs commonly use an index, such as the prime rate, plus a lender-set margin.
For a variable offer, identify both components. An introductory rate can temporarily obscure the rate that applies afterward. Also check adjustment timing, any minimum rate and contractual caps.
The Consumer Financial Protection Bureau’s explanation of how a HELOC works provides useful background on variable rates and the difference between draw and repayment periods.
Lenders also differ in operating costs, product availability and appetite for particular loans. That is why the same application can receive different offers on the same day.
Ask whether the quote is preliminary, what assumptions it uses and whether its pricing can be locked. A quote based on an estimated property value or unverified credit information is not the same as an approved offer based on completed underwriting.
Separate the interest rate from the complete price
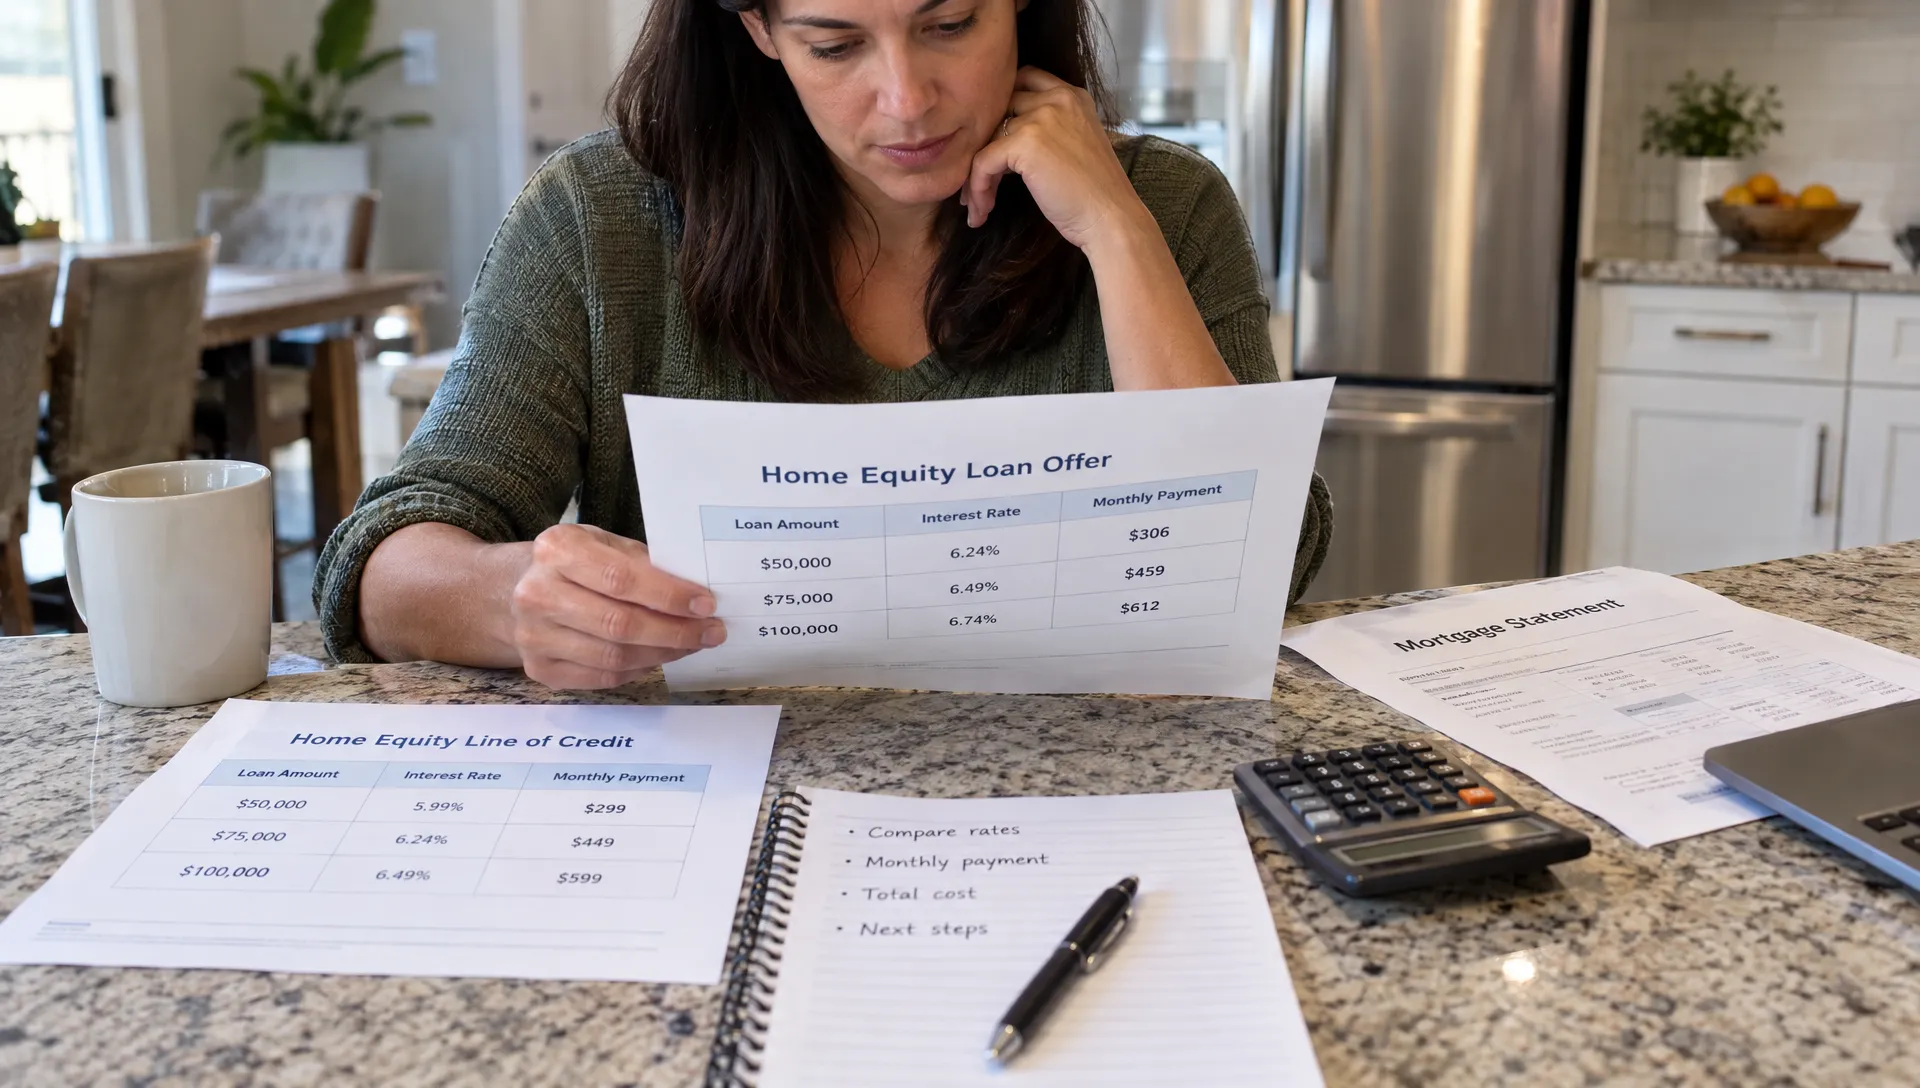
Equity mortgage rates tell you what interest costs, but they do not tell you everything you will pay. Origination charges, appraisal costs, closing fees and discount points can change the economics of an offer.
On closed-end loans, annual percentage rate (APR) includes interest and certain finance charges. It is useful alongside the note rate, but it is not a universal shortcut across different products. A HELOC’s disclosed APR generally reflects interest rather than capturing fees in the same way as a closed-end loan’s APR.
Review annual fees, early-closure provisions and any introductory-rate conditions separately. If an offer includes points, request a comparable no-point option. Paying upfront for a lower rate only helps if the interest savings justify that expense over the time you keep the loan.
For a cash-out refinance, examine the standardized Loan Estimate. Home equity products may use different disclosures, so ask the lender to identify where the rate, finance charges and repayment terms appear.
You can also use our guide to comparing mortgage offers beyond the headline rate when organizing competing quotes.
Account for the mortgage you already have
A second mortgage often carries a higher rate than a first mortgage because it has a lower-priority claim on the property. If foreclosure proceeds are insufficient, the junior lienholder faces greater loss exposure.
That higher rate does not automatically make it the more expensive choice for your household. Keeping a low-rate first mortgage can outweigh paying a higher rate on a smaller equity loan.
Consider this illustrative example, not a current rate quote or lending offer:
| Financing approach | Assumed balance, rate and term | Approximate monthly principal and interest |
|---|---|---|
| Keep the existing first mortgage | $300,000 at 3.5%, with 25 years remaining | $1,502 |
| Add a home equity loan | $50,000 at 9.5%, repaid over 10 years | $647 |
| Combined payment for those two loans | Existing first mortgage plus equity loan | $2,149 |
| Replace both with a cash-out refinance | $350,000 at 6.5%, repaid over 25 years | $2,363 |
The calculations exclude closing costs, taxes and insurance and assume fixed rates and fully amortizing payments. Actual offers will differ.
Although the refinance rate is lower than the assumed equity-loan rate, it reprices the entire $350,000 balance. The equity portion also stretches over 25 years rather than 10.
When evaluating equity mortgage rates, compare the combined payment and repayment timeline, not just the rate attached to the new cash. Your expected payoff date, fees and need for payment flexibility can change which approach fits best.
Questions that make a quote easier to evaluate
A productive lender conversation should identify the cause of the price, not simply ask whether a lower number is available. Request written terms and ask:
- What property value and CLTV does this quote assume? Confirm whether appraisal results could change pricing.
- Would a smaller loan amount change the rate or fees? Ask about actual pricing tiers rather than assuming less borrowing always earns a discount.
- Does the quoted rate require points, automatic payments or another condition? Identify the cost and consequence of not meeting that condition.
- For a HELOC, what are the index, margin and post-introductory terms? Include repayment-period payment rules in the discussion.
- What can still change before closing? Clarify verification requirements, pricing expiration and any available rate-lock terms.
To compare equity mortgage rates fairly, give each lender the same requested amount, property use and preferred repayment structure. Quotes based on different assumptions cannot show you which lender actually offers the better deal.
Frequently asked questions
Does having more equity guarantee a lower rate? No. More equity may improve CLTV and open additional options, but credit, lien position, loan structure and lender pricing still matter. Ask whether your application falls near a pricing threshold where reducing the requested amount would make a difference.
Are home equity loan rates usually higher than first-mortgage rates? Second-lien loans often carry higher rates because the lender has a lower-priority claim on the property. That is a general relationship, not a rule that every available quote will follow.
Can equity mortgage rates change after I receive a quote? Yes. Preliminary quotes may change with market pricing, verified credit information, appraisal results or changes to the requested loan. If pricing is locked, ask which conditions remain subject to verification and what happens if the lock expires.
Is a fixed rate always better than a variable rate? No. A fixed rate provides interest-rate stability, while a variable rate creates payment uncertainty. Compare the borrowing period, repayment terms and your ability to handle increases. A low introductory HELOC rate should not be the only basis for choosing the loan.
Get an offer built around your actual situation
Before requesting financing, gather your mortgage statement, income records and a clear estimate of the cash you need. Then ask for an explanation of the assumptions behind the quote.
New Era Lending combines smart mortgage tools with personalized human guidance for home purchase, refinancing and equity access. Discuss your existing mortgage, borrowing goals and available options so you can evaluate the complete offer, not just its advertised rate.