


What a New Construction Loan in New Jersey Can Cost
If you searched “loan new jersey” to find financing for a house you plan to build, focus on the full project budget, not just the advertised rate. A construction loan can involve interest on money released during the build, lender fees, inspections and the cost of converting to a permanent mortgage. Land, permits, site work and delays add another layer.
Your actual cost depends on how much you borrow, when funds are released and what the loan agreement charges. There is no single statewide construction loan price. The worked example below uses a $750,000 project budget to show how those pieces fit together. Its figures are illustrations, not current rates, market averages or an offer of financing.
First, identify which financing arrangement you need
Buying a completed home from a builder is different from borrowing to build on your own lot. With a completed-home purchase, the builder generally finances construction and you obtain a purchase mortgage when the home is ready. Deposits and rate-lock timing still matter, but you may not need a construction loan yourself.
For a borrower-managed building project, these are the main structures to discuss:
| Financing structure | How it works | Cost question to ask |
|---|---|---|
| Construction-to-permanent loan | Construction financing transitions into a long-term mortgage under the program’s terms | Is there one closing, and what conversion or modification charges remain? |
| Standalone construction loan | A short-term construction loan is paid off with separate permanent financing | What will a second closing cost, and must you qualify again? |
| Purchase mortgage for a finished new home | Mortgage funds are generally provided when the completed property closes | Who bears delays, and what happens if the rate lock expires? |
A construction loan in New Jersey should be evaluated around the actual transaction, including who owns the land and who is responsible for building. Do not assume that every lender offering mortgages also offers borrower-funded construction financing.
From “loan new jersey” searches to a complete project budget
Land, site work and the builder’s contract
The builder’s quoted price is not necessarily the cost of delivering a move-in-ready home. Review whether it includes excavation, grading, drainage, utility connections, landscaping and driveway work. A contract allowance for cabinets or fixtures may also be lower than the products you eventually choose.
For a New Jersey lot, investigate municipal zoning, utility availability and any applicable flood hazard, wetlands or coastal requirements before treating the land price as final. A relatively inexpensive parcel can require substantial site preparation.
Ask for a written scope with allowances and exclusions. If engineering or soil conditions remain unresolved, identify who pays when the final requirements differ from the estimate.
Lender charges and third-party services
Construction financing may include origination charges, discount points, an appraisal based on plans and specifications, title services, recording charges and draw administration. Inspections or title updates may be required before funds are released.
One discount point equals 1% of the loan amount. On a $600,000 loan, one point costs $6,000. Compare any rate reduction against that upfront expense, particularly if the construction financing will only remain outstanding briefly.
Use the Consumer Financial Protection Bureau’s Loan Estimate guide to understand standardized mortgage disclosures when they apply. Request a separate construction fee schedule, too, so you can see charges tied to inspections, draws, extensions and conversion.
Interest, insurance and overlapping housing expenses
Many construction loans require interest-only payments during the building period, often calculated on funds already advanced rather than the entire approved commitment. The exact calculation comes from your agreement.
You may also need construction-related insurance, property insurance or other coverage required by the lender. Confirm who obtains each policy and what the builder’s insurance does not cover.
When budgeting for a construction loan in New Jersey, include rent or an existing mortgage you will carry during the build. Those payments can create a cash shortage even when construction itself stays within budget. Our guide to New Jersey mortgage expenses beyond the down payment explains the broader distinction between closing cash, monthly expenses and reserves.
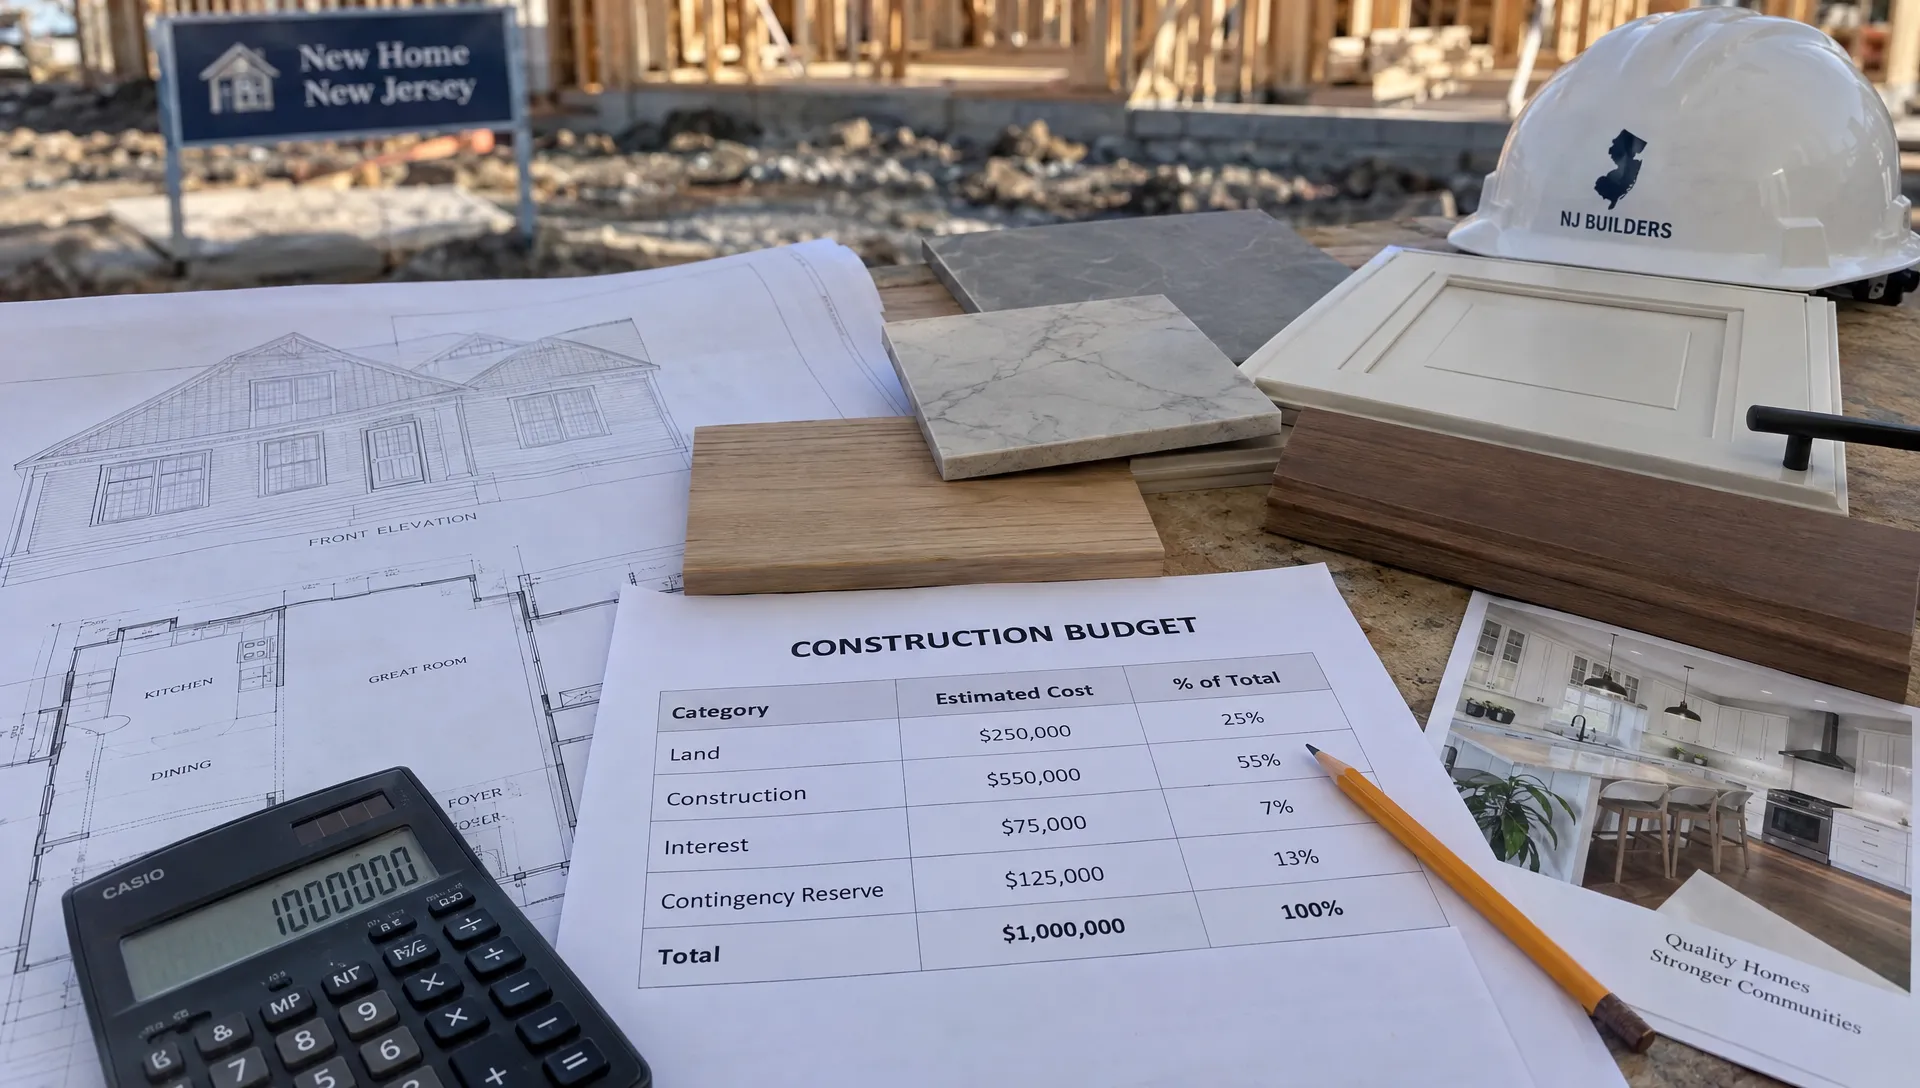
A worked construction budget
The following hypothetical project separates construction expenses from financing costs. It excludes ongoing property taxes, insurance and temporary housing, which must be budgeted separately.
| Budget item | Illustrative amount |
|---|---|
| Land purchase | $150,000 |
| Builder’s construction contract | $480,000 |
| Site work, design, permits and utility connections outside the contract | $45,000 |
| Construction contingency | $45,000 |
| Construction interest and loan-related fees | $30,000 |
| Illustrative project budget | $750,000 |
Assume the lender approves $600,000 toward eligible project costs. The remaining $150,000 must come from accepted borrower equity or cash, before expenses outside this budget. That is not automatically the amount due at closing. Timing, existing land ownership and which costs the lender allows you to finance all affect the cash requirement.
The $30,000 financing allowance could, for example, consist of $22,500 in construction interest and $7,500 in fees. Both are assumptions, not fee estimates for New Era Lending or any other lender.
A construction loan in New Jersey may also be limited by the completed-home appraisal. If an illustrative program caps lending at 80% of appraised value and the appraisal comes in at $700,000, that cap would be $560,000. Compared with the assumed $600,000 loan, the borrower would need to address a $40,000 funding gap, subject to the program’s other rules.
How construction interest changes as the home progresses
A useful planning formula is:
Approximate monthly interest = outstanding loan balance × annual interest rate ÷ 12.
Actual billing may use daily balances and a contractual day-count method. At a purely illustrative 7.5% annual rate, the simplified calculation looks like this:
| Outstanding balance | Approximate monthly interest |
|---|---|
| $100,000 | $625 |
| $300,000 | $1,875 |
| $500,000 | $3,125 |
| $600,000 | $3,750 |
If the average outstanding balance were $300,000 over a 12-month build at that assumed rate, interest would total approximately $22,500. That is the interest assumption used in the sample budget.
Two projects with the same final loan amount can therefore have different interest costs. An early land advance or large initial draw keeps more money outstanding for longer. A slower draw schedule may reduce interest, but the builder still needs reliable payment timing.
For a construction loan in New Jersey, ask whether interest is paid from your monthly income or from an approved interest reserve. A financed reserve is borrowed money, not free interest, and it can run short if construction takes longer than expected.
New Jersey costs that deserve a separate check
Property taxes after construction
Do not use the tax bill on vacant land as the expected tax bill for the completed home. New construction can trigger an added assessment, and an initial escrow estimate may not reflect the eventual obligation.
Ask the municipal tax assessor how the completed property is likely to be assessed and how added assessments are handled. The state’s local property tax resources provide background, but a parcel-specific estimate requires local information.
A construction loan in New Jersey can look affordable during its interest-only period while the completed home’s full payment is substantially higher. Build your long-term budget using principal and interest, expected property taxes, insurance and any applicable association charges or mortgage insurance.
Permits, utilities and property conditions
Permit and connection costs vary by municipality, property and scope of work. Ask whether the budget includes construction permits, inspections, water and sewer connections or well and septic requirements where applicable.
Check flood exposure early because it can affect design, insurance and financing. FEMA’s Flood Map Service Center is a starting point, not a substitute for a survey, professional site review or insurance quote.
Before closing, reconcile the builder’s scope with the lender’s approved budget. An item excluded by both is still your expense, even if each party assumed someone else had included it.
What delays and change orders can add
A delay can increase interest, housing overlap, insurance expenses and loan extension charges at the same time. At the illustrative 7.5% rate, holding a $500,000 balance for three additional months adds approximately $9,375 in interest alone, using a simplified monthly calculation.
An extension may require approval, a fee or updated documentation. Ask what happens if construction exceeds the loan’s maturity date and whether the permanent mortgage rate lock has a separate expiration.
For a construction loan in New Jersey, test the budget against a longer schedule and a meaningful overrun before committing. Keep contingency funds available for project problems rather than treating them as an upgrade allowance.
Personal spending needs a separate boundary. If you have a vacation planned during construction, flights, lodging and extras such as electric cart rentals in Les Saintes belong in the travel budget, not the reserve protecting your home build.
Compare written offers using the same assumptions
A lower advertised rate does not necessarily produce the lowest total cost. Ask competing lenders to price the same loan amount, build duration, draw assumptions and permanent financing structure.
For each construction loan in New Jersey you consider, get written answers to these questions:
- Equity requirement: How much cash or accepted land equity is required, and how is that equity valued?
- Interest calculation: Is the rate fixed or variable, what balance accrues interest and how are payments collected?
- Draw charges: What inspection, administration or title-update fees apply, and how quickly are approved draws funded?
- Completion requirements: What documentation, inspections and occupancy approvals are required before conversion or payoff?
- Delay exposure: What are the extension charges, maturity rules and rate-lock expiration terms?
- Permanent financing: Is another closing or qualification review required, and which future costs remain uncertain?
The land-equity answer matters if you already own the lot. Accepted equity may satisfy part of your contribution, but it does not necessarily provide cash to pay deposits, fees or overruns.
Our guide to comparing mortgage offers beyond the headline rate can help with the permanent mortgage comparison. For construction, add the draw schedule and delay costs to that analysis.
Frequently asked questions
How much down payment does a construction loan require? Requirements vary by lender, program, borrower and project. Ask for the required contribution in dollars, how owned land is credited and how much liquidity must remain after closing. Do not assume a down payment advertised for a completed-home mortgage also applies to construction.
Can the loan cover land and building costs? Some construction programs can include a land purchase or pay off an existing lot loan along with eligible construction expenses. Approval depends on the program, appraisal and project budget. Confirm which costs must be paid separately.
Does a one-time-close loan eliminate all later fees? No. It may avoid a second full mortgage closing, but inspections, extensions, modifications or conversion-related charges can still apply under the agreement. Request an itemized explanation rather than relying on the phrase “one-time close.”
What happens if the project goes over budget? You may need additional cash, approved scope reductions or another lender-approved solution. Extra borrowing is not guaranteed. Notify the lender before authorizing a change order that exceeds the approved budget.
What will the payment be after construction? It depends on the permanent loan’s balance, rate and term. For illustration, a $600,000 mortgage at 7.5% over 30 years has principal and interest of about $4,195 per month, before taxes, insurance and other charges. That rate is an example, not a current quote.
Get the financing scope confirmed before you commit
Before signing a building contract, gather the lot details, plans, builder proposal and a budget that includes interest and reserves. Ask New Era Lending which mortgage options are available for your New Jersey property and whether its available programs support your construction scenario.
The goal is a written financing plan that identifies what is covered, what remains your responsibility and how much cash you need if the project takes longer or costs more than expected.