


What Lending Access Means for Buyers With Limited Credit History
For a homebuyer with little borrowing history, lending access means having a realistic path to mortgage financing, even when a traditional credit score tells an incomplete story. A short credit history does not automatically disqualify you. It does mean the lender may need different evidence, a different underwriting approach or a loan program that accommodates your situation.
The useful question is not simply, “Can I get approved?” It is, “Which lenders can evaluate my financial history, what documentation will they accept and what will the loan actually cost?” Those answers can help you prepare without taking on unnecessary debt.
Limited credit is different from damaged credit
Credit history measures your experience with reported borrowing, not your entire financial life. Someone who pays rent reliably, avoids loans and saves regularly may still have a thin credit file.
These situations require different conversations:
| Credit situation | What it means | What to discuss with a lender |
|---|---|---|
| Short credit history | You have relatively little history on reported accounts | Whether the available history supports the proposed loan |
| No usable credit score | Your file does not meet a scoring model’s requirements | Whether a no-score or nontraditional-credit pathway is available |
| Negative credit history | Your report contains late payments, collections or other adverse information | How those events affect eligibility and whether waiting would help |
A missing score is not the same as a low score. However, neither situation guarantees a particular outcome. Lenders still need to establish that you can afford the mortgage and meet the applicable loan requirements.
Before applying, review your credit reports for unfamiliar accounts, incorrect late payments and missing information. A consumer credit app also may not show the same score a mortgage lender uses.
How lenders evaluate lending access with a thin credit file
A mortgage decision involves more than the number attached to your credit report. When the file is limited, other parts of the application become especially important.
Income and employment help establish whether your earnings are stable and likely to continue. The documentation depends on how you earn money. A salaried employee, self-employed buyer and seasonal worker may need different records.
Debt-to-income ratio, or DTI, compares qualifying monthly debt payments with qualifying gross monthly income. Having little credit history does not eliminate this calculation. Student loans, auto payments and other obligations can still affect the amount you qualify to borrow.
Savings and documented funds show where your down payment and closing money come from. Some applications also require reserves, meaning eligible funds left after closing. A larger balance helps only when its source and availability meet the loan’s rules.
Payment history outside traditional credit accounts may provide additional evidence when the program permits it. Rent, utilities or other recurring obligations can matter, but the lender decides what counts and how it must be verified.
The property must qualify, too. Strong finances cannot overcome every issue involving an appraisal, property condition or program eligibility.
Compare mortgage pathways, not just advertised minimum scores
The right program can improve lending access, but published program rules and an individual lender’s approval standards are not always identical. Additional lender requirements are often called overlays.
| Mortgage pathway | Why it may be worth discussing | What to verify |
|---|---|---|
| Conventional financing | Certain pathways accommodate borrowers without traditional credit scores | Transaction eligibility, underwriting method and acceptable credit evidence |
| FHA financing | Nontraditional credit can be considered in qualifying cases | Lender participation, documentation requirements and mortgage insurance costs |
| VA financing | Eligible veterans, service members and certain surviving spouses may qualify | Eligibility, lender credit standards and residual-income requirements |
| USDA financing | Eligible buyers and properties may have another government-backed option | Income limits, location eligibility and treatment of limited credit |
Fannie Mae’s Selling Guide includes requirements for nontraditional credit, illustrating why “conventional” does not always mean a long credit history is mandatory. The details depend on the transaction and underwriting route.
Manual underwriting means a human underwriter evaluates the application under the program’s applicable rules rather than relying solely on an automated recommendation. It is not a waiver of credit standards, and it is not necessary or available in every no-score case.
New Era Lending’s overview of mortgage options for homebuyers provides broader context. For a thin-file buyer, the next step is narrowing those options to lenders that can actually evaluate the available evidence.
Assemble evidence before submitting an application
When lending access depends on nontraditional credit, organized records can reduce avoidable follow-up requests. Ask the lender which documents qualify before paying for a reporting service or assembling months of unrelated statements.
A useful starting file may include:
- Housing-payment records: Your lease, landlord contact information and bank records showing rent payments, if requested.
- Other payment records: Statements or verification for eligible recurring obligations that the lender agrees to consider.
- Income documents: Pay statements, tax documents or business records appropriate to your employment situation.
- Asset statements: Complete statements showing savings, transfers and funds intended for closing.
- Explanations for unusual activity: Supporting records for large deposits, employment gaps or other items the lender identifies.
Cash rent payments can be harder to document than payments with a bank trail. A lease establishes the obligation, but it does not necessarily prove that every payment arrived on time. Ask what verification is acceptable rather than assuming a landlord letter will be sufficient.
Likewise, rent reporting and mortgage underwriting are not interchangeable. A service might report rent to a credit bureau without making that history usable for every mortgage product or scoring model.
Use the lender’s approved secure upload method for sensitive records. Keep original documents intact and ask before redacting information, because incomplete statements can create additional verification work.
Protect your cash before trying to build credit quickly
Improving lending access should not require borrowing money you do not need. Opening several accounts shortly before applying can create inquiries, new payment obligations and uncertainty about your finances.
A secured card or credit-builder account may be useful when you have enough preparation time, but it is not an instant mortgage solution. Ask a loan professional whether establishing more reported history would help your specific application and what timeline makes sense. Avoid carrying interest-bearing balances merely to demonstrate credit use.
Cash deserves equal attention. Separate the money needed for closing from emergency savings and the expenses of moving into the home. Do not assume that every dollar in your account should become a down payment.
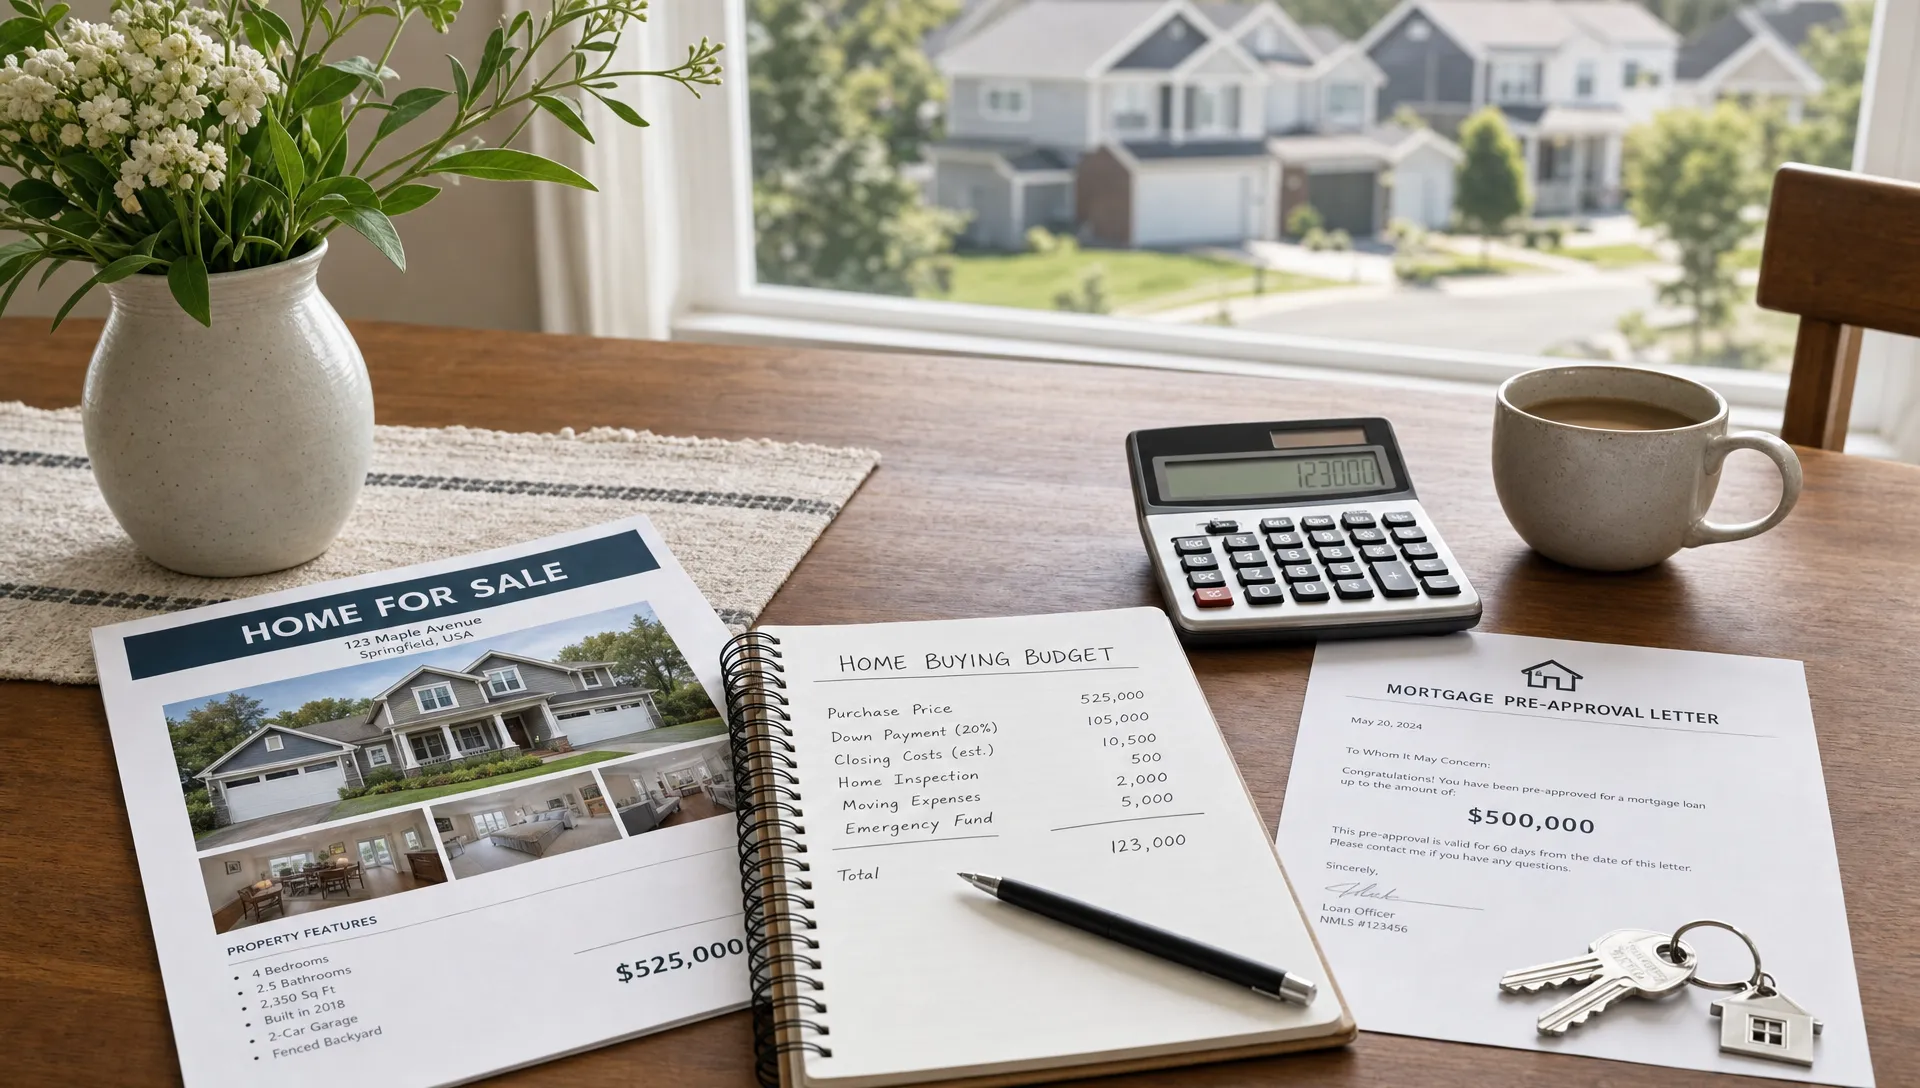
Your personal budget should also go beyond the lender’s DTI calculation. Groceries, childcare, maintenance and ordinary discretionary spending still affect whether a payment feels manageable. Even hobby purchases, such as ant farm kits and supplies, belong in that budget rather than coming out of funds reserved for closing.
Before moving money, accepting a gift or financing a major purchase, check with your lender. A well-intended financial change can require new documentation or alter qualification.

Ask how the lender will evaluate your application
Before paying application-related costs, ask whether the lender handles your particular situation: a short history with a score, no usable score or limited history alongside negative information. Those are not interchangeable scenarios.
Get clear answers about the proposed underwriting route, acceptable payment references and any requirements beyond the loan program’s baseline standards. Ask whether the initial discussion involves a credit inquiry and whether the lender has reviewed enough documentation to identify likely obstacles.
Any preapproval should be understood in terms of its remaining conditions. Property review, updated financial documents and final underwriting can still affect the outcome. An encouraging conversation is not a commitment to fund a loan.
Cost comparisons matter just as much as eligibility. Review the interest rate, annual percentage rate, mortgage insurance, lender fees and estimated cash to close. The Consumer Financial Protection Bureau’s Loan Estimate guidance explains the standardized form used to present key mortgage terms.
Better lending access should give you a clearer choice, not pressure you into accepting the first available offer. As New Era Lending explains in its discussion of transparent mortgage lending, understanding terms and costs is part of making an informed decision.
A practical example: a renter with no usable score
Consider a hypothetical buyer who has rented for several years, earns a steady salary and has savings but has never used a credit card or installment loan.
The first step is to confirm the actual credit situation. An apparently empty file might contain an old account, an error or enough information to generate a score under one model but not another.
Next, the lender would assess income, debts, available funds and the proposed purchase. If an eligible no-score pathway exists, the buyer could then provide the specific payment evidence required. Rent records may help, but they would not substitute for income qualification or property approval.
If that lender does not offer a suitable pathway, the buyer can ask whether the obstacle is a program requirement or the lender’s own policy. Another lender may evaluate the file differently, although approval is never assured.
This is what lending access looks like in practice: identifying a workable evaluation process rather than treating the absence of a score as either an automatic rejection or an automatic exception.
Frequently asked questions
Can I get a mortgage without a credit score? Some mortgage pathways allow qualifying borrowers without a traditional credit score. Availability depends on the program, lender, transaction and supporting documentation. Income, debt, funds and property requirements still apply.
Will adding a co-borrower solve a limited-credit problem? Not necessarily. A co-borrower’s income and credit may help, but their debts also become part of the evaluation. The program’s rules determine how each borrower’s credit profile is treated. A co-borrower also takes on legal responsibility for repayment.
Does paying rent on time automatically count toward mortgage approval? No. Rent must be verified through an acceptable method, and its treatment depends on the underwriting process. Keep reliable records and ask which forms of evidence the lender accepts before purchasing a rent-reporting service.
Should I wait to apply until I have built more credit? Start with an eligibility conversation rather than assuming you must wait. You may already have a viable route, or additional preparation may improve your options. The best next step for lending access depends on what your current file supports and how soon you plan to buy.
Start with a review of your actual situation
You do not need to manufacture a borrowing history before asking about a mortgage. Start by gathering your income records, savings information and housing-payment history, then explain what is missing from your credit file.
New Era Lending combines mortgage technology with personalized human guidance. Ask which available options can accommodate your credit profile, what evidence would be required and whether applying now or preparing longer would better support your purchase.