


How to Verify a Mortgage Solutions Payment Phone Number
If you’re searching for a mortgage solutions payment phone number, verify the company and its role before you call. Similar business names, outdated listings and sponsored search results can send you to the wrong place. The lender that originated your mortgage may not be the company collecting your payments today.
Start with your latest mortgage statement or an established, authenticated servicing portal. Compare the contact information there with any number you found elsewhere. Don’t send money or disclose sensitive information merely because a search result, text message or caller claims to represent your mortgage company.
Identify the company responsible for your payments
Your mortgage servicer is the company that manages your loan account, collects payments and typically handles escrow questions. Your original lender, mortgage broker and current servicer may be different businesses.
That distinction determines whom to contact. A loan officer may help with a purchase or refinance application but may not have access to your current payment history. Our guide to how lenders, brokers and servicers differ explains those responsibilities in more detail.
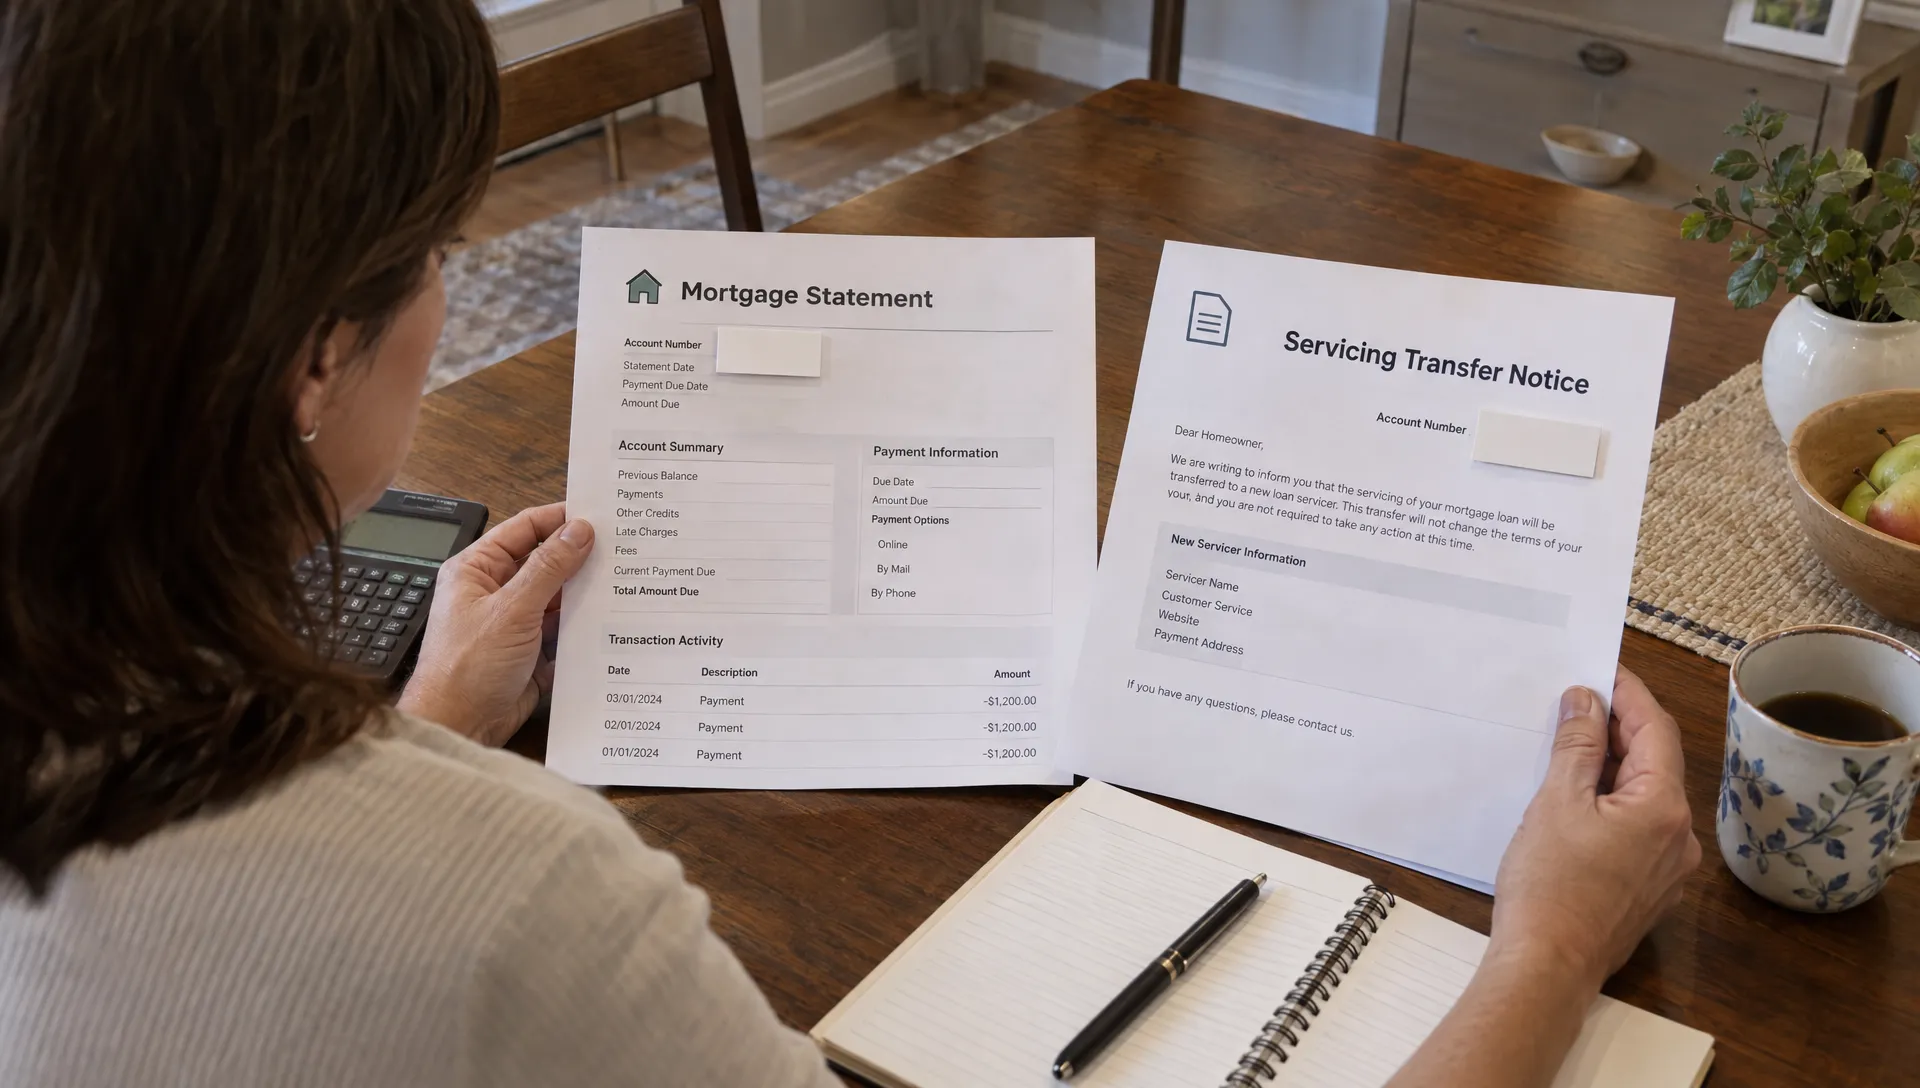
Look for the servicer’s full legal name on your most recent statement. Match more than the words “Mortgage Solutions”: check the company name, mailing address and website domain. If you recently received a servicing-transfer notice, the company collecting your payments may have changed.
How to verify a mortgage solutions payment phone number
Start with records you already trust
Use your latest statement, a previously established servicing portal or confirmed correspondence from your servicer. A saved bookmark that you have used successfully is generally a better starting point than a new search advertisement.
If you receive electronic statements, access them through your established account rather than following an unexpected email link. Check the statement date, since an older document may identify a previous servicer.
Compare the customer-service or payment number with the contact information inside the authenticated portal. Different departments can legitimately have different numbers, so a mismatch needs clarification rather than an automatic assumption of fraud.
If you have never made a payment on the loan, review your closing documents and any subsequent servicing notices. Your original lender or closing agent can help identify the designated servicer through contact information you already have on file. Don’t rely on a replacement number supplied by the same unexpected message you are trying to verify.
Check the website’s identity and purpose
When checking a mortgage solutions payment phone number, inspect the website address itself. A familiar logo, company name in a page title or padlock icon does not establish that a site belongs to your servicer. HTTPS encrypts a connection; it does not guarantee that the business behind it is the right one.
Watch for misspelled domains, extra words and addresses that differ from your statement. Search snippets and business-directory listings can be useful leads, but they are not proof of ownership or current payment instructions.
Also confirm that the page actually concerns mortgage servicing. An unrelated business can be legitimate without being relevant: MTS Productions’ NYC event listings, for example, concern nightlife experiences and reservations, not home-loan payments. The point is to match the website’s purpose to your task, not simply confirm that the website exists.
Once you identify the correct domain, navigate to its payment or servicing section yourself instead of trusting an unsolicited deep link.
Reconcile any servicing-transfer notices
A transfer can change where you send payments without changing the underlying loan terms. Review the effective date, the new servicer’s name and the instructions in your notices. If the notices conflict, call your existing servicer using a previously verified number to confirm the transfer.
Under federal mortgage-servicing transfer rules, during the 60-day period beginning on the transfer’s effective date, a timely payment received by the old servicer generally cannot be treated as late by the new servicer or trigger a late fee.
Before using a mortgage solutions payment phone number from an older statement, check whether that protection period or a recent transfer explains the discrepancy. The protection does not eliminate your payment obligation or mean that old instructions remain appropriate indefinitely.
Confirm whether automatic payments will continue or require new enrollment. Keep the notices and payment confirmations together until the new account reflects your payment correctly.
What to confirm before authorizing a phone payment
Once you have independently reached the servicer, normal identity verification may be necessary to discuss the account. That does not mean you should provide online banking passwords, approve unexpected bank-login prompts or disclose codes that authorize account access or transfers.
Ask the representative to explain the payment process before you authorize a withdrawal. The following questions help prevent avoidable errors:
| Question | What it helps you verify |
|---|---|
| Are you handling payments for my current loan account? | You reached servicing rather than sales or another company |
| What amount will be withdrawn, and on what date? | The authorization matches your intended payment |
| Is there a fee, and is a no-fee payment method available? | You understand any payment-channel costs |
| What cutoff time and time zone apply? | You know when the payment will be credited |
| Is an automatic or pending payment already scheduled? | You reduce the risk of paying twice |
| What confirmation will I receive? | You have a record to check against your account |
After you verify a mortgage solutions payment phone number, use the call to confirm these details rather than assuming every payment method works the same way. A confirmation number may show that a request was accepted, not that funds have cleared.
If you plan to automate future payments, review how to set up autopay without missed or duplicate payments before changing an existing arrangement.
Recognize suspicious calls and payment instructions
Caller ID can be spoofed. A familiar business name or local area code does not authenticate the person calling. If an incoming caller requests payment or sensitive information, end the call and contact the servicer through an independently verified channel.
Warning signs include:
- Unusual payment demands: Instructions to pay with gift cards, cryptocurrency or a transfer to an individual.
- Sudden changes: A new payment destination or wire instruction delivered only by text or email.
- Pressure and secrecy: Demands to act immediately, avoid contacting your servicer or ignore your statement.
- Account-access requests: Instructions to disclose a banking password, approve a login prompt or install remote-access software.
Don’t trust a mortgage solutions payment phone number just because it appears on caller ID. Even accurate details about your property or loan do not prove the caller is authorized to collect a payment.
If someone threatens foreclosure, verify the claim promptly through established servicing channels. Don’t ignore formal notices, but don’t let an urgent demand replace independent verification. If a due date is approaching, use a payment method you have already verified and document any difficulty reaching the servicer.
What to do if you already called or paid
Act quickly if you disclosed sensitive information or sent money to a questionable destination. Contact your bank or payment provider through its official app, a number on your card or another established channel. Explain what happened and ask whether a payment can be stopped, recalled or disputed. Recovery depends on the payment method and timing; it is not guaranteed.
Next, reach your actual servicer through your authenticated account or trusted statement. Ask whether the payment appears on your loan and how to address any upcoming deadline. A withdrawal from your bank account does not, by itself, prove that your mortgage was credited.
If you called an unverified mortgage solutions payment phone number, preserve the number, messages, receipts and any instructions you received. Change affected passwords if you disclosed credentials and tell your bank about any exposed account information. Report suspected fraud to the Federal Trade Commission.
For a servicing error, ask about the servicer’s formal written notice-of-error process and designated mailing address. Keep copies of your correspondence. You can also submit an unresolved mortgage-servicing issue through the Consumer Financial Protection Bureau’s complaint process.
Frequently asked questions
Who should I contact about mortgage payment questions? Contact your current mortgage servicer for payment posting, account balances, escrow questions and existing-loan assistance. Start with your latest statement or authenticated portal. Your original loan officer may help identify the servicer but may not manage the account.
Is a business called Mortgage Solutions necessarily a broker? No. A business name alone does not establish whether it acts as a broker, lender or servicer. Identify the exact legal entity and confirm its role in your loan. A company that helped arrange financing is not automatically the company authorized to collect monthly payments.
Can a search result verify a mortgage solutions payment phone number? Not by itself. Treat search results, advertisements and directory entries as leads that require confirmation. Compare the number with trusted loan records and the established servicing portal before sharing account information or authorizing a payment.
How do I request a mortgage payoff? Request an official payoff statement from your current servicer through a verified channel. A payoff amount can differ from the principal balance because it may include interest through a specified date and applicable charges. Confirm the good-through date and delivery instructions. Independently verify wire instructions with the servicer and any closing professional involved, especially if instructions change unexpectedly.
What if the verified number does not work? Use the secure messaging or contact options inside your established servicing portal. You can also review confirmed transfer notices or ask your original lender to help identify the current servicer. Avoid replacing a disconnected number with the first unverified search result.
Get guidance for your next mortgage decision
Payment verification starts with your current servicer. For a new home purchase, refinance or equity-access loan, New Era Lending offers personalized mortgage guidance supported by modern technology. Keep those roles separate: confirm existing payment instructions with the company servicing your loan, and discuss new financing goals with a lending professional.