


How the Mortgage Business Works and Who Gets Paid
The mortgage business connects homebuyers with money to purchase property, but several companies may earn income from a single loan. The lender that approves your application, the broker who helps arrange financing and the servicer that collects your payments can all have different roles and compensation.
Understanding those roles helps you compare offers more effectively. A closing charge is not always lender profit, a lower rate may require an upfront payment and the company collecting your monthly payment may not own your loan.
Follow three separate streams of money
A home loan involves three money streams: funding, transaction costs and ongoing payments.
Funding is the money advanced to complete your purchase or refinance. Transaction costs pay for arranging the loan, evaluating the property and completing the closing. Ongoing payments repay the debt and may also fund an escrow account for property taxes and insurance.
These streams overlap, but they are not interchangeable. Your down payment is not a lender fee. Money deposited into escrow is not lender profit. And the interest you pay does not necessarily stay with the company whose name appeared on your original application.
Who gets paid in the mortgage business?
One organization may perform several functions, while another handles only one. Here is how the main participants fit together.
| Participant | Main responsibility | How it may be paid |
|---|---|---|
| Mortgage lender | Underwrites and funds the loan | Origination charges, interest income, loan-sale proceeds or servicing income |
| Mortgage broker | Helps arrange financing through lenders it works with | Broker compensation paid by the borrower or lender, subject to applicable rules |
| Loan officer | Guides the application and loan selection | Salary, commission or a combination paid by the employer |
| Loan investor | Owns the loan or an investment backed by mortgages | Cash flows associated with principal and interest, subject to the investment structure |
| Mortgage servicer | Collects payments, manages escrow and handles account administration | Servicing compensation and certain permitted charges |
| Third-party providers | Perform appraisal, title, settlement and other services | Charges for their individual services |
A bank can originate, own and service a mortgage. A nonbank lender can fund a loan and later sell it. A broker generally arranges financing rather than supplying the loan funds.
The names on your documents may therefore change without changing the basic agreement you signed.
How lenders earn revenue
Revenue in the mortgage business can arrive at closing, over years of repayment or when a loan is sold. These are different business models, not necessarily separate charges added to every borrower’s bill.
Origination charges and discount points
Origination charges compensate a lender for making the loan. Depending on the offer, they may appear as an origination fee, underwriting fee, processing fee or a combination. Compare the total rather than assuming that fewer line items mean a cheaper loan.
Discount points are different from ordinary processing charges. They are an upfront cost paid to obtain a lower interest rate. One point equals 1% of the loan amount, but there is no universal rate reduction associated with that point.
Lender credits generally work in the opposite direction: accepting a higher rate can provide a credit toward closing costs. Neither points nor credits are automatically better. Their value depends on the actual pricing and how long you expect to keep the loan.
Interest income and funding costs
A lender that holds a mortgage earns interest, but that interest is not all profit. The lender must account for its funding costs, operating expenses, credit risk and other obligations.
In the mortgage business, banks may use deposits and other funding sources, while nonbank lenders often use short-term warehouse credit facilities to fund loans before selling them. Those borrowing arrangements also cost money.
For the borrower, the useful comparison is the offered rate and total costs, not an assumption about which type of institution must have lower overhead.
Loan sales and servicing rights
A lender may sell a completed mortgage to an investor, sometimes through channels connected to mortgage-backed securities. The sale price relative to the lender’s investment and expenses affects whether the transaction produces a gain or loss.
Servicing rights can also have value. A company may retain the right to administer a loan after selling ownership, or transfer that responsibility to another servicer.
Selling a loan does not automatically create a new borrower fee or allow the buyer to rewrite a fixed interest rate.
An example: which closing dollars are revenue?
The distinction between charges and deposits matters throughout the mortgage business. Consider this simplified example for a $300,000 loan. These amounts are hypothetical, not a quote or a complete closing-cost estimate.
| Illustrative item | Amount | What the payment represents |
|---|---|---|
| Lender origination charge | $3,000 | Gross lender revenue before related business expenses |
| Discount points | $1,500 | Upfront payment for the quoted lower-rate option |
| Appraisal fee | $650 | Payment for property valuation services |
| Prepaid interest | $600 | Interest covering a specified period around closing |
| Initial escrow deposit | $1,800 | Funds held for future property tax and insurance bills |
The $1,500 in points equals 0.5% of the loan amount. Whether paying it makes sense depends on the payment savings compared with an otherwise comparable offer without those points.
The appraisal payment is not automatically lender income simply because it appears in the closing paperwork. Similarly, the escrow deposit is money held for designated bills, not a fee for approving the mortgage.
For more detail on how escrow and repayment fit together, see our explanation of how mortgage payments are built and why they change.
How brokers and loan officers are compensated
Compensation rules in the mortgage business are designed to limit incentives that could steer borrowers toward unfavorable loan terms.
For covered transactions, federal rules generally prohibit loan-originator compensation based on the interest rate or other transaction terms, apart from permitted measures such as loan amount. They also generally prohibit a loan originator from receiving compensation from both the consumer and another person on the same transaction. The details appear in the CFPB’s loan-originator compensation rule.
A broker paid by the lender is not necessarily providing an economically cost-free service. That compensation is part of the lender’s economics and can affect the pricing available to the borrower. A borrower-paid arrangement makes the broker’s charge more explicit, but it does not automatically produce the lowest total cost.
Ask whether broker compensation is borrower-paid or lender-paid, where it is disclosed and whether it is already included in the figures you are comparing. Also ask which lenders the broker can access. A broker’s lender network is not necessarily the entire market.
Separately, federal RESPA rules generally prohibit payments for settlement-service referrals involving federally related mortgage loans. The CFPB’s explanation of prohibited referral fees distinguishes these arrangements from permitted payments for actual services.
Where a mortgage company’s revenue goes
Gross revenue is not the same as net profit in the mortgage business. Companies must pay employees, maintain technology, protect customer information, meet compliance obligations and cover funding expenses.
Processing and underwriting require work even when an application does not close. Lenders also face costs associated with quality control, fraud prevention and, in some circumstances, obligations to repurchase loans that fail to meet sale requirements.
Marketing is another expense. Digital presentation can be elaborate: outside lending, The New Face’s immersive brand experiences illustrate how fashion and luxury brands use navigable 3D environments and product configurators. For mortgage shoppers, however, visual sophistication is not evidence of competitive pricing, licensing or reliable service.
A useful mortgage website should help you understand costs, identify the company and communicate securely. Judge the financing itself through written disclosures rather than branding alone.
These operating expenses explain why a company needs revenue, but they do not make every charge competitive. You can still compare offers and ask whether particular lender-controlled charges can be reduced.
What happens when your mortgage is sold?
Ownership and servicing transfers are routine parts of the mortgage business, but they describe different changes.
An ownership transfer changes who owns the debt. A servicing transfer changes the company responsible for collecting payments and administering the account. Either can occur without the other.
For a typical fixed-rate mortgage, a transfer does not itself change the contractual interest rate or remaining repayment term. Your total monthly bill can still change for reasons already allowed under the loan, such as an escrow adjustment. Adjustable-rate loans continue to follow their contractual adjustment rules.
If servicing changes, review the transfer notices, verify the new payment instructions independently and update automatic payments as directed. Do not rely on an unexpected email requesting a wire transfer or a new bank account without confirming it through a trusted contact channel.
Keep copies of statements and payment confirmations, particularly during the transition.
How to compare offers without confusing price and presentation
Understanding the mortgage business is most useful when it changes how you shop. Focus on comparable written offers, transparent compensation and a company you can verify.
Request comparable Loan Estimates
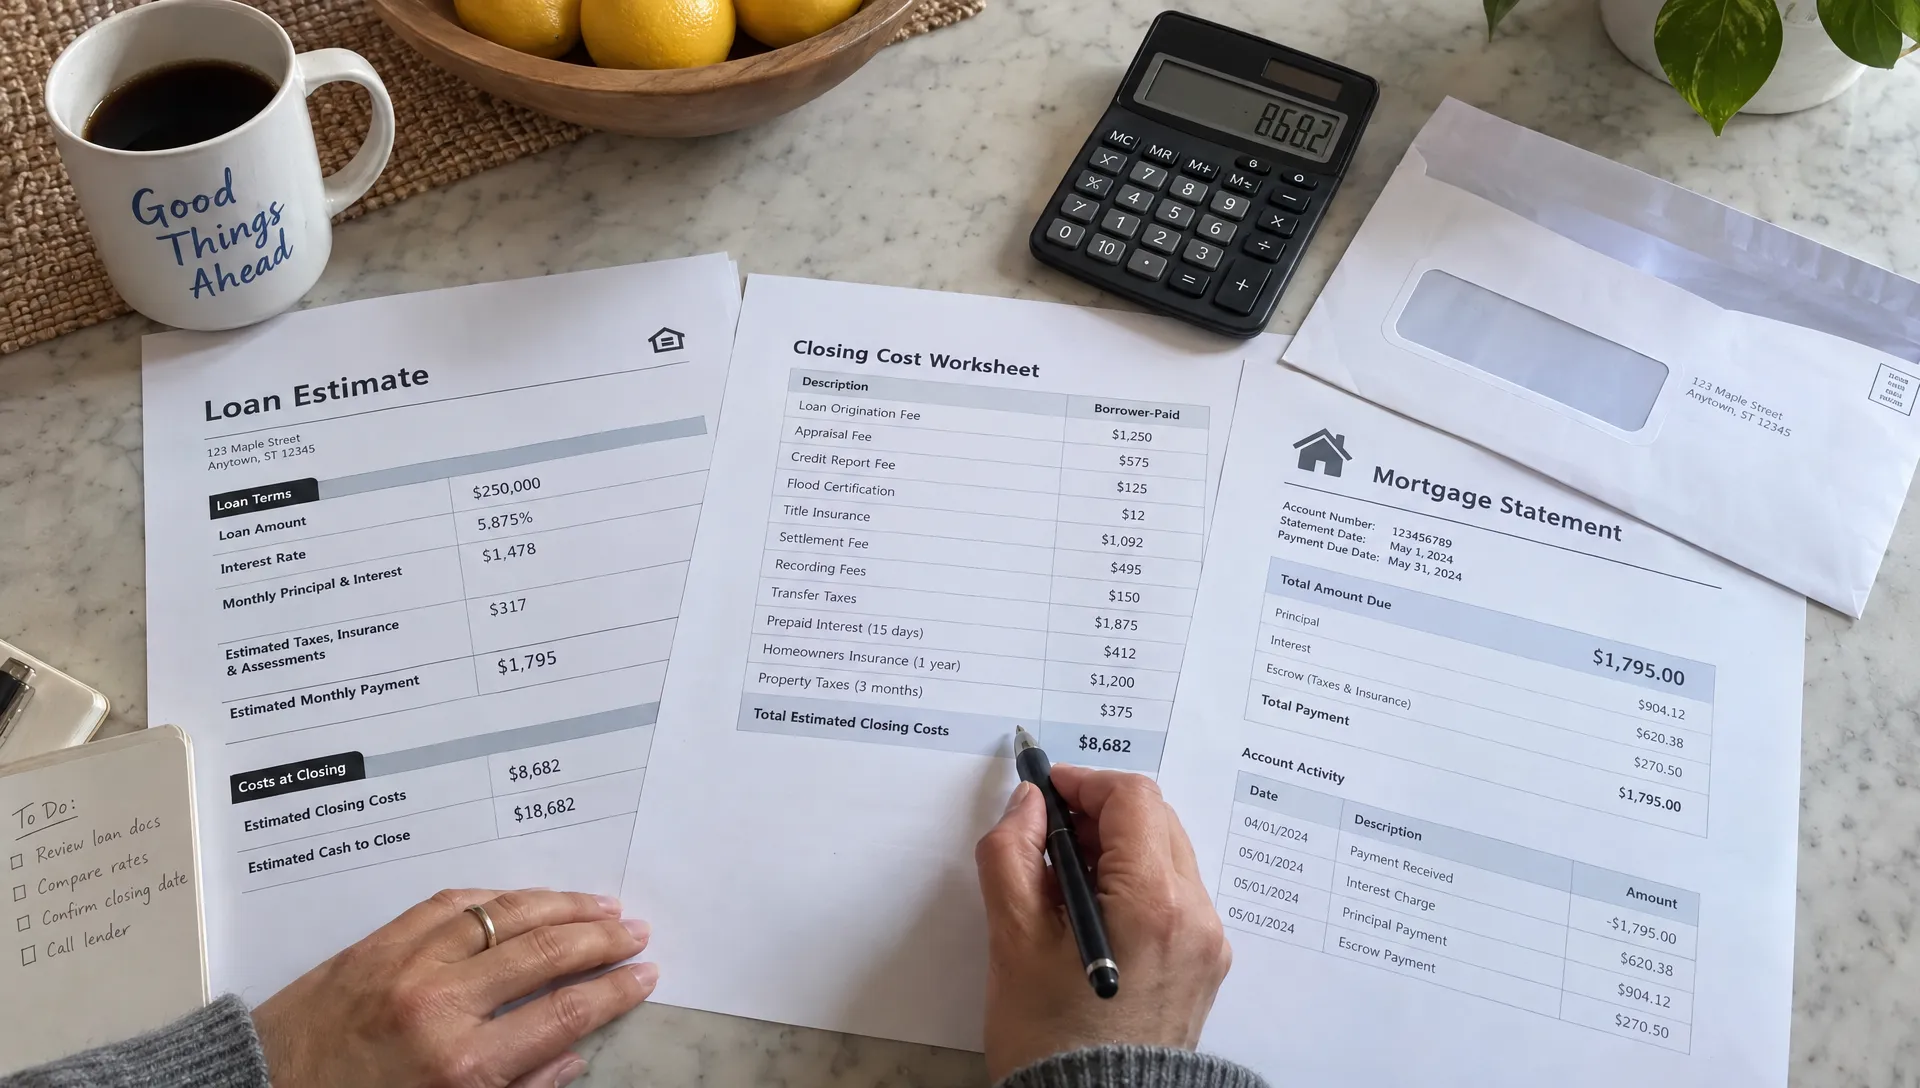
For most standard closed-end home mortgages, lenders must provide a Loan Estimate within three business days after receiving an application. The CFPB’s Loan Estimate guide explains the form and its key sections.
Compare the same loan amount, loan type, term and rate-lock assumptions. Offers prepared on different days may reflect different market pricing.
Review the interest rate alongside origination charges, points, lender credits and projected payments. APR adds useful cost information, but it is not a substitute for examining the individual charges and your expected holding period.
Separate negotiable pricing from other costs
Lender-controlled charges deserve particular attention. Property taxes and recording charges are different from a lender’s origination pricing, while some third-party services may be shoppable as indicated on the Loan Estimate.
The mortgage business includes both financing providers and settlement providers, so identify the recipient before asking what can change.
For a points decision, a simple starting calculation is the additional upfront cost divided by monthly principal-and-interest savings. If paying $1,500 saves $30 per month, the simple break-even period is 50 months. That calculation does not account for investment returns, tax effects or differences in principal reduction, but it helps frame the trade-off.
Verify the company and the person
Use NMLS Consumer Access to review available company and individual licensing or registration information. Requirements differ by institution and role: many nonbank mortgage loan originators require state licenses, while covered bank employees generally follow federal registration requirements.
Ask who will fund the loan, who will communicate underwriting conditions and how to raise a concern. If you are also assessing your readiness to apply, our guide to what you need to get a mortgage explains the borrower documents and qualifications separately from these business relationships.
Frequently asked questions
Is a mortgage company the same as a mortgage broker? No. In the mortgage business, a lender funds loans, while a broker generally helps arrange loans through other lenders. “Mortgage company” is a broad description, so ask which role the company performs in your transaction.
Does my loan officer keep my origination fee? Not necessarily. An origination charge is typically company revenue, while the loan officer is paid under an employment or compensation arrangement. The fee is not automatically the individual’s commission or take-home pay.
Does “no closing costs” mean nobody gets paid? No. Costs may be offset by lender credits associated with a higher rate, paid by another party where permitted or included in the loan balance when the program allows. Ask what mechanism covers the costs and how it changes your payment or debt.
Is a bank always cheaper than a broker or nonbank lender? No. Pricing depends on the loan, borrower profile, market conditions and provider’s offer. Compare written estimates rather than choosing solely by institution type.
Should I worry if the lender plans to sell my loan? A planned sale is not, by itself, a warning sign. Focus on the original loan terms, accurate disclosures and clear instructions if ownership or servicing changes.
Get a clear explanation of your financing options
You do not need to master the mortgage business to make a well-informed choice. You do need to understand who is arranging the loan, which costs compensate them and how the offer fits your plans.
New Era Lending combines technology-driven mortgage tools with personalized human guidance for purchase, refinance and equity-access needs. Ask for an explanation of the available options, applicable charges and trade-offs before deciding.