


Biweekly vs. Monthly Mortgage Payment Plans Compared
Switching your mortgage monthly payment to a biweekly schedule can help you pay off your loan sooner, but the savings usually come from paying more each year, not simply paying more often. A standard accelerated biweekly plan collects half your monthly payment every two weeks, creating the equivalent of one extra monthly payment annually.
That can be useful if you receive a paycheck every other week. It can also create unnecessary fees or payment-processing problems if the arrangement is poorly designed. Before enrolling, compare the annual payment amount, how your servicer applies the money and whether a simpler extra-principal payment would accomplish the same goal.
Monthly, biweekly and twice-monthly payments are different
A monthly plan generally requires 12 payments per year. An accelerated biweekly plan generally collects 26 half-payments, equivalent to 13 full payments. A twice-monthly, or semimonthly, plan collects 24 half-payments, equivalent to 12 full payments.
The distinction matters because “twice a month” and “every two weeks” are not interchangeable.
| Payment arrangement | Typical collection schedule | Annual equivalent | Extra payment built in? |
|---|---|---|---|
| Monthly | One full payment each month | 12 monthly payments | No |
| Accelerated biweekly | Half a monthly payment every two weeks | 13 monthly payments | Yes |
| Semimonthly | Half a monthly payment twice each month | 12 monthly payments | No |
| Monthly with extra principal | One regular payment plus a chosen additional amount | Depends on the extra amount | Only what you add |
Does a mortgage monthly payment change under a biweekly plan?
Usually, the contractual monthly amount does not change just because you enroll in a different withdrawal schedule. The biweekly arrangement changes how money is collected and, ideally, adds principal payments over time.
However, not every plan labeled “biweekly” works the same way. Some arrangements divide your annual required payments into 26 smaller withdrawals rather than collecting half a monthly installment each time. Those plans may help with budgeting but do not necessarily add an extra payment.
Compare annual dollars paid, not just withdrawal frequency. Ask whether the program collects 12 or 13 monthly-payment equivalents and how much actually reaches principal.
Where the interest savings come from
Mortgage interest is charged on the outstanding principal balance according to your loan's terms. Paying additional principal reduces that balance sooner, leaving less principal on which future interest can accrue.
An accelerated schedule makes this happen by increasing your annual payments. Earlier application of funds may also affect interest, depending on the loan's interest-calculation method and servicing practices, but you should not assume every half-payment immediately reduces your balance.
Your mortgage monthly payment is therefore only one part of the comparison: the annual amount applied to principal is what drives most of the payoff advantage in a typical accelerated plan.
Two borrowers can use different schedules and achieve similar results if they pay comparable extra amounts at comparable times. One might use an approved biweekly program while another adds extra principal to each regular monthly payment.
Paying extra does not lower your interest rate. It generally reduces the time you carry the debt and the total interest paid. Your required installment usually stays the same unless a separate change, such as an approved recast or refinance, changes it.
A worked example: $300,000 at 6%
Consider a hypothetical $300,000 fixed-rate mortgage with a 30-year term and a 6% interest rate. Its scheduled principal-and-interest payment is approximately $1,798.65 per month.
This example excludes property taxes, homeowners insurance, mortgage insurance and program fees.
| Approach | Payment amount | Approximate annual principal-and-interest outlay |
|---|---|---|
| Standard monthly | $1,798.65 each month | $21,584 |
| Accelerated biweekly | $899.33 every two weeks | $23,382 |
| Monthly with an equivalent annual extra | $1,798.65 plus $149.89 each month | $23,382 |
Adding one-twelfth of the regular principal-and-interest payment each month produces approximately the same annual outlay as 26 half-payments. Rounding can create small differences.
Under a standard monthly amortization calculation, paying approximately $1,948.54 each month from the start would retire this hypothetical loan in roughly 24 years and 7 months. Total interest would fall from approximately $348,000 to approximately $274,000, a savings of about $74,000.
Those figures describe the monthly-extra-payment alternative, not a guaranteed result for every biweekly service. Actual biweekly results depend on posting dates, fees and how extra funds are applied.
The required mortgage monthly payment in this example remains approximately $1,798.65 for principal and interest; the additional $149.89 is voluntary. Paying extra later in the loan generally produces less interest savings than starting immediately, assuming the same additional payment amount.
How your servicer handles half-payments matters
Your mortgage servicer receives payments and manages the account. Its procedures matter more than the name of the payment program.
A servicer may hold a partial payment in a suspense or unapplied-funds account until enough money arrives to cover a full periodic payment. During that interval, the money may not reduce your principal balance.
A third-party payment company may also collect funds before forwarding them to the servicer. That creates another timing consideration, especially around the monthly due date.
Before changing your schedule, confirm when the first full payment will reach the servicer. Do not assume that sending half by the due date satisfies the monthly obligation. A grace period also does not change the contractual due date.
Your mortgage monthly payment must still be credited correctly and on time under the arrangement. Keep your existing payment method in place until the servicer confirms how the transition will work, while checking that you will not accidentally make duplicate payments.
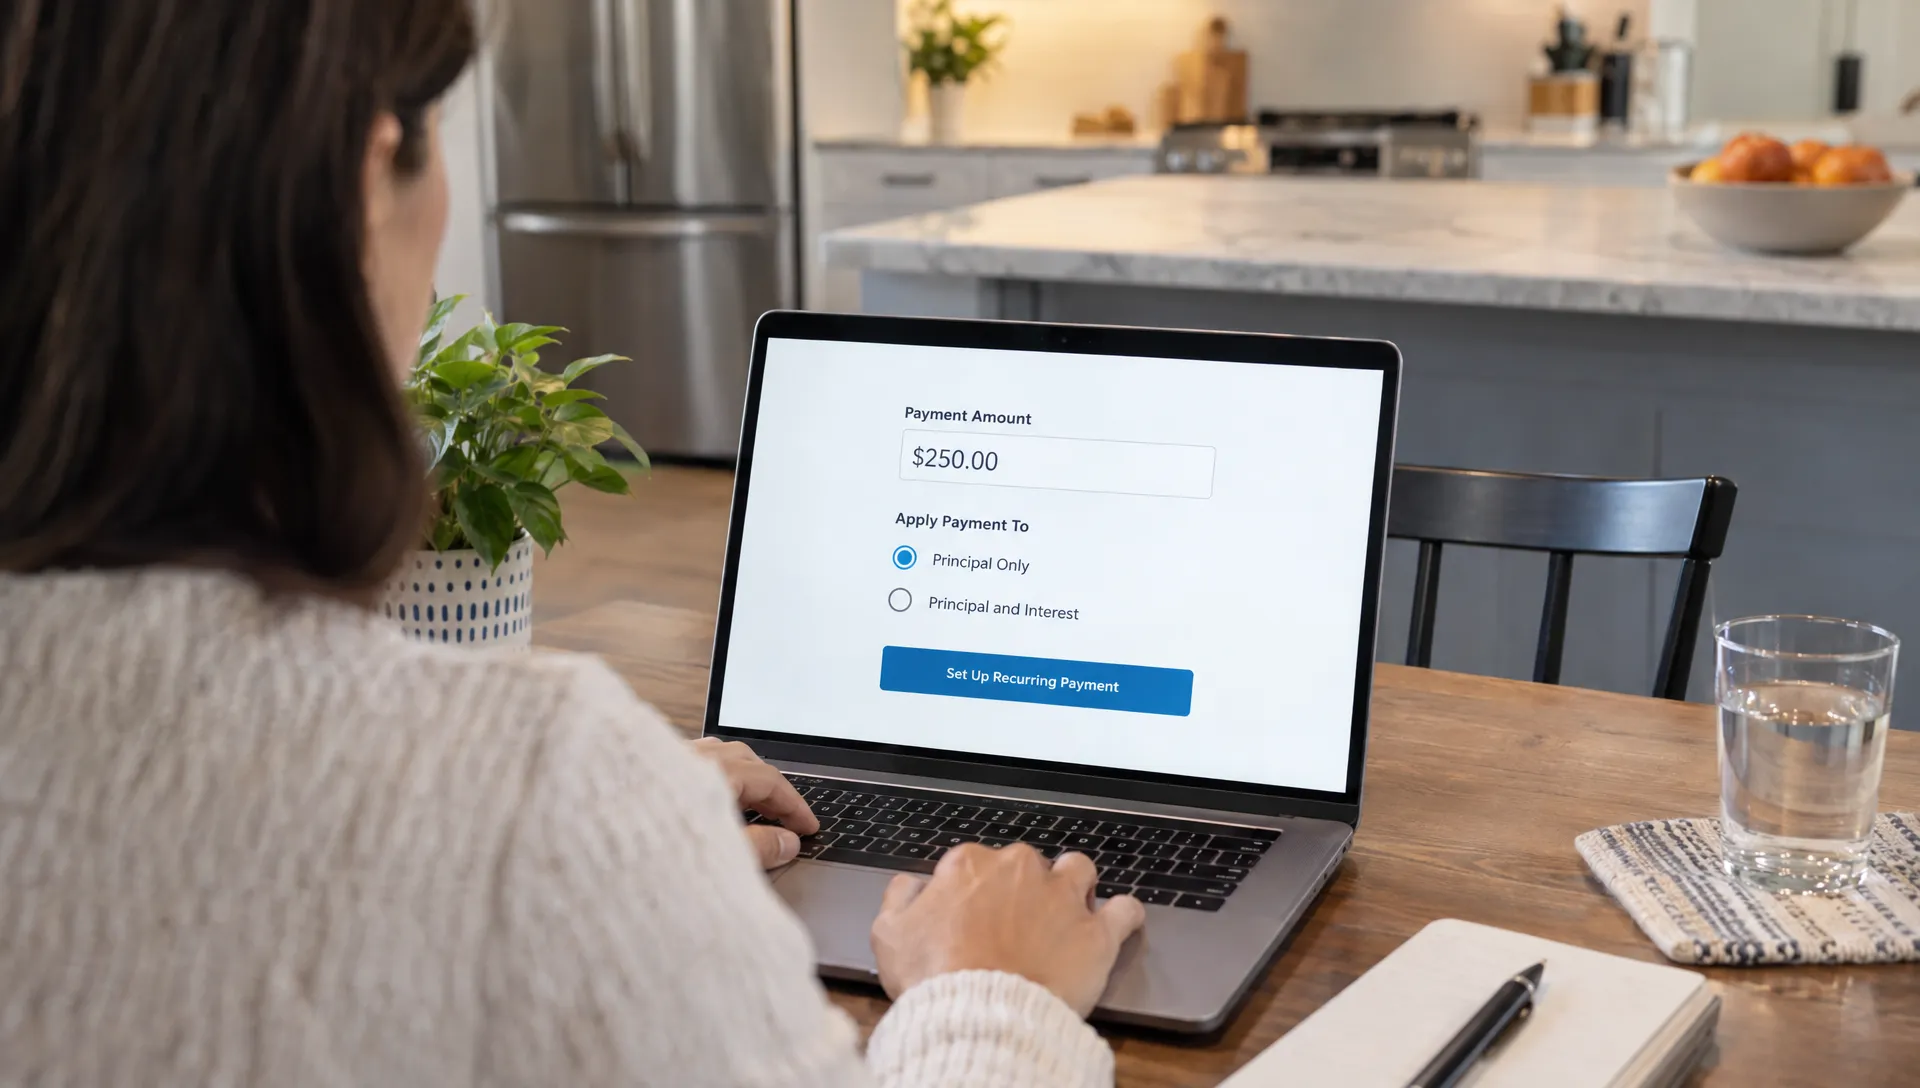
After enrollment, review statements for the payment received, the amount applied to principal and any funds held unapplied. Confirm that extra money is credited as a principal reduction rather than merely advancing a future payment date. Ask whether you need to provide specific principal-only instructions.
Compare the full housing budget, not just principal and interest
The example above isolates loan repayment. Your actual bill may also include escrow for property taxes and homeowners insurance, plus mortgage insurance when applicable.
If a program collects half your entire payment every two weeks, ask what happens to the extra amount collected for escrow-related costs. Do not assume every dollar beyond 12 monthly installments reduces your loan balance.
Your mortgage monthly payment can also rise because of an escrow adjustment or, with an adjustable-rate mortgage, an interest-rate reset. A biweekly collection schedule does not prevent either change. Extra withdrawals may need to increase when the required payment changes.
Before committing to accelerated repayment, budget for utilities, maintenance, repairs and any homeowners association dues paid separately. New Era Lending's guide to monthly mortgage costs buyers often miss explains why the mortgage bill alone is not the full cost of ownership.
Fees and cash-flow pressure can outweigh convenience
An enrollment charge or recurring processing fee reduces the value of an accelerated plan. Before paying for a service, ask whether your servicer offers a no-fee way to make additional principal payments directly.
For example, a hypothetical $5 processing charge on each of 26 withdrawals would cost $130 annually. That is money you could otherwise retain or potentially apply toward principal.
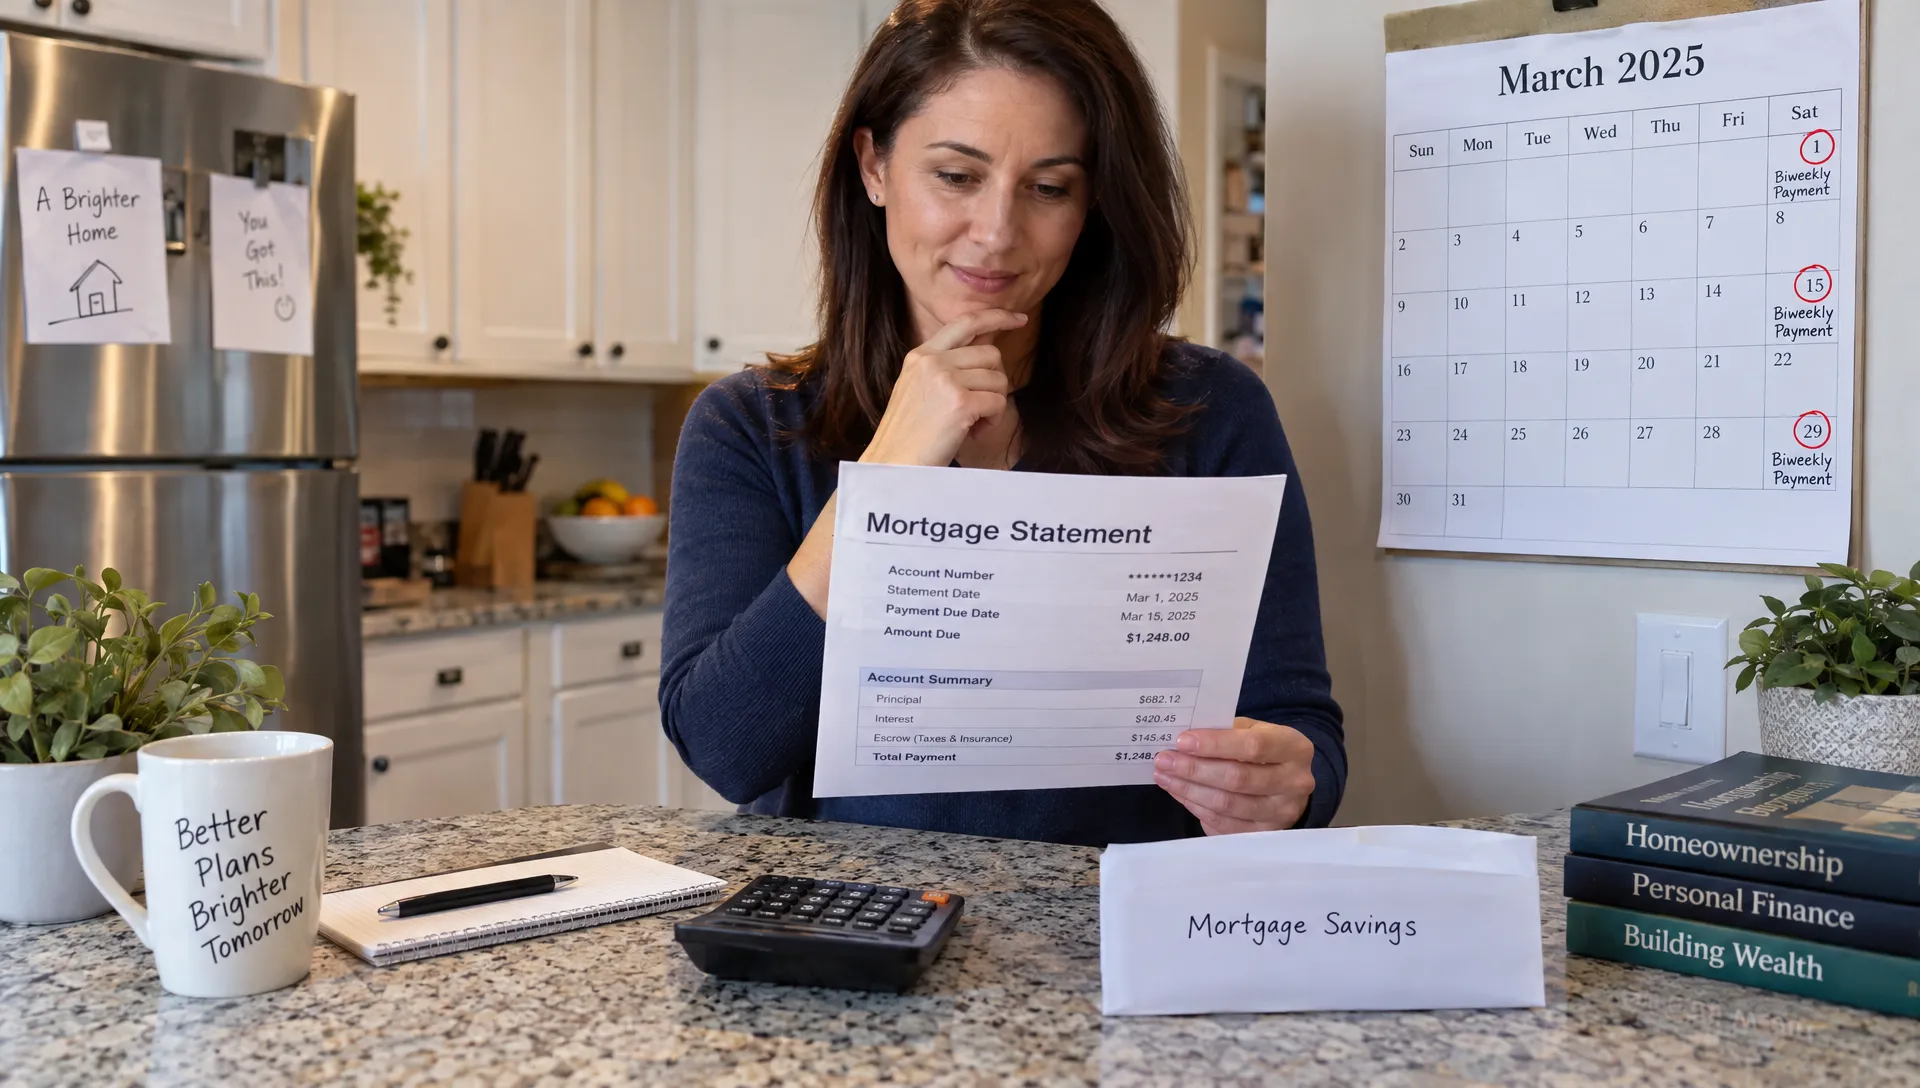
The schedule can also strain cash flow. Biweekly withdrawals generally create two months each year with three half-payment withdrawals instead of two. That may fit someone paid every other week, but it can be awkward for someone paid monthly or on the first and fifteenth.
A comfortable mortgage monthly payment does not automatically mean you can afford 13 payment equivalents each year. Test the higher annual commitment against your emergency savings, irregular expenses and other debt obligations.
Paying extra principal also converts accessible cash into home equity. Getting that money back generally requires selling the home or qualifying for another borrowing arrangement. Preserving cash may be more useful when a major repair is approaching or your income is uncertain.
Check your loan documents for any prepayment restrictions or penalties before making substantial additional payments.
Alternatives that keep the monthly schedule
Add one-twelfth of principal and interest each month
Divide your regular monthly principal-and-interest amount by 12 and add that amount to each monthly payment. Use the servicer's approved process for directing the addition to principal.
This spreads one extra annual payment across the year without requiring a separate biweekly program. It also makes the additional amount easy to identify when reviewing your statement.
For borrowers whose income varies, keeping the mortgage monthly payment on its existing schedule and making optional additions can preserve flexibility. Confirm how to adjust or stop recurring extra payments if your budget changes.
Make occasional lump-sum principal payments
A tax refund, bonus or proceeds from selling an unused asset can support a one-time principal payment without creating an ongoing commitment.
For example, a Georgia homeowner selling an old vehicle could compare cash offers for an unwanted car with other sale options, then decide whether any net proceeds are better used for savings, higher-interest debt or mortgage principal.
The amount and timing will determine the interest benefit. A lump sum paid earlier generally saves more interest than the same amount paid later, assuming the same loan terms. There is no need to spend or sell something solely to participate in an accelerated repayment plan.
Which payment plan fits your situation?
Monthly payments may fit best when you want straightforward bill management, receive income monthly or need to prioritize cash reserves. You can still add principal when your finances allow.
Accelerated biweekly payments may fit best when you are paid every two weeks, can comfortably afford the extra annual payment and have verified a low-cost arrangement with reliable payment application.
Monthly payments with automatic extra principal may fit best when you want similar annual acceleration without changing the collection schedule. This approach can be particularly practical when the servicer provides a clear principal-only payment option.
Before choosing, build a baseline estimate of your mortgage monthly payment that separates principal and interest from escrow and other costs. New Era Lending's guide to estimating your monthly mortgage payment can help you establish that starting point.
If you are comparing new loans rather than changing an existing payment schedule, review each lender's Loan Estimate. Check the loan amount, rate, term, projected payments and escrow assumptions. Then evaluate voluntary extra payments separately so that different assumptions do not distort the comparison.
Questions to ask before enrolling
Get clear answers from the servicer before authorizing withdrawals:
- Does the plan collect 26 half-payments, or does it divide 12 annual payments into smaller withdrawals?
- When are partial payments credited, and can they be held as unapplied funds?
- How are extra collections divided between principal and escrow?
- Are there setup charges, transaction fees or cancellation costs?
- How will the first payment cycle satisfy the monthly due date?
- Can I make the same extra principal payments directly without a program?
Request the terms in writing and review the first statements after the change. A convenient withdrawal schedule is useful only if payments reach the account on time and the extra amount is applied as intended.
Frequently asked questions
Are biweekly mortgage payments better than monthly payments? They can be better for borrowers who want automatic extra repayment and can afford it. They are not inherently better than monthly payments with a comparable amount of extra principal, especially if the biweekly service charges fees.
Will switching to biweekly lower my mortgage monthly payment? Usually not. It changes the collection schedule and may increase your annual payments. The required monthly installment generally stays the same unless the loan is separately modified, refinanced or recast with approval.
Do twice-monthly payments pay off a mortgage faster? Not automatically. Twenty-four half-payments equal 12 full payments, so there is no extra annual installment. Any benefit from payment timing depends on how the loan calculates interest and how the servicer applies funds.
Can I stop making extra payments later? Voluntary extra payments can often be adjusted, but the rules depend on your payment arrangement. Confirm cancellation procedures and continue making every required payment on time.
Compare the schedule before committing
The strongest plan is one you can sustain without sacrificing essential savings or paying avoidable fees. Compare annual outlay, principal application and flexibility rather than choosing by the payment-plan label alone.
For help evaluating a purchase or refinance, connect with New Era Lending for personalized mortgage guidance. For an existing loan's withdrawal schedule or extra-payment instructions, contact your current servicer.