Home Buying Loan Options for Condos With Financing Restrictions
A condo can fit your budget and still fail a lender’s property review. Comparing home buying loan options means checking both your eligibility and the condominium project’s eligibility before committing money to inspections, appraisal fees or a nonrefundable deposit. The useful question is not simply which mortgage has the lowest down payment. It is which loan can finance this particular unit, given the building’s insurance, finances, condition and ownership structure.
A condo mortgage requires two approvals
Your mortgage application involves two separate decisions. The lender evaluates your income, credit, debts and available funds. It also determines whether the condo meets the requirements of the selected loan program.
That second review can involve the homeowners association, commonly called the HOA, and the broader condominium project. A well-maintained unit does not resolve inadequate building insurance, major structural repairs or certain project-level legal problems.
Borrower preapproval is not condo project approval. Even a recent sale in the building does not prove your purchase will qualify. The previous buyer may have used another program, paid cash or closed before the project’s circumstances changed.
Legal classification matters, too. A property that looks like a townhouse may legally be a condominium, while a similar-looking property may have a different ownership structure. Understanding how property type affects mortgage requirements helps you ask the right questions before choosing a program.
Identify the restriction before changing loan programs
The right home buying loan options depend on why financing is restricted, not simply on whether someone calls the building “non-warrantable.” That term generally describes a condo that does not meet applicable conventional agency project requirements, but the underlying issue determines what happens next.
| Project issue | Why it can affect financing | Useful next step |
|---|---|---|
| Missing HOA documents | The lender cannot complete its review | Request the specific missing records |
| Inadequate master insurance | Coverage may not meet program requirements | Obtain an insurance review and identify any required changes |
| Critical repairs or structural concerns | Building safety or soundness may be compromised | Request engineering reports and the remediation plan |
| Weak reserves or significant delinquencies | The HOA may struggle to meet obligations | Review financial statements, collections and reserve information |
| Litigation | The dispute may create unacceptable project risk | Provide details for the lender’s legal or underwriting review |
| Rental or ownership concentration | The project may exceed program limits | Check the selected program and review method |
Not every lawsuit makes a project ineligible. A routine collection matter differs from litigation involving structural defects. Likewise, rental restrictions and investor ownership are separate questions that require actual project documents.
Fannie Mae’s ineligible project guidance illustrates why the specific issue matters. Ask the lender to identify the requirement involved and whether the problem is missing evidence, a correctable deficiency or an unacceptable project characteristic.
Which home buying loan options can work for a restricted condo?
Start with programs that match both your financial profile and the project. Moving to a different mortgage only helps if that program can accept the restriction.
Conventional financing: check the available review path
A conventional loan may remain possible when the problem is incomplete paperwork or a condition the HOA can correct. Depending on the transaction and project, a lender may use a full review, limited review or an applicable review exemption.
Limited review does not mean no standards. It can reduce certain documentation requirements, but it does not make prohibited project characteristics acceptable. A larger down payment may change the review path available for some transactions without resolving critical repairs or disqualifying insurance deficiencies.
Ask whether the objection comes from agency rules or an additional lender requirement, often called an overlay. Another lender might handle an overlay differently, but it cannot simply disregard agency requirements while making the same type of agency-eligible loan.
Before switching lenders, obtain a clear explanation of the issue so you do not pay twice to discover the same obstacle.
FHA financing: consider project approval or single-unit approval
FHA should be part of your home buying loan options comparison if you meet borrower requirements, but FHA eligibility also depends on the property. A condo may qualify through an FHA-approved project or, in qualifying circumstances, through the single-unit approval process.
Single-unit approval is not a general exception for every unapproved building. Both the unit and the project must satisfy applicable requirements, and the lender must be able to complete that process.
Use HUD’s FHA condominium lookup as a starting point, then have the lender verify the relevant project or phase and current status. An expired approval or a listing agent’s statement that the building “takes FHA” is not enough.
FHA’s low-down-payment structure can help an eligible buyer preserve cash, but it does not eliminate project review, closing costs or mortgage insurance.
VA financing: verify the project separately
For eligible veterans, service members and certain surviving spouses, a VA purchase loan may offer financing without a down payment, subject to entitlement, value and other requirements. Condo purchases also require the applicable VA project approval.
Do not assume FHA approval establishes VA eligibility. Ask the lender to verify the correct project and phase in VA’s records. If approval is needed, determine who will assemble the submission and whether the expected timeline fits your contract.
VA financing can reduce upfront cash needs for eligible borrowers, but unresolved project approval can still prevent closing. A funding fee may also apply unless the borrower qualifies for an exemption.
Portfolio and non-warrantable condo financing: evaluate the exact exception
When agency programs cannot accept a project, portfolio mortgages may expand your home buying loan options. A portfolio lender keeps selected loans rather than requiring every loan to meet a standard agency purchase framework.
Some lenders offer programs for particular non-warrantable condo characteristics. Their acceptable exceptions, down payments, reserve requirements and pricing vary. “Non-warrantable financing” is not one standardized product, and it should not be confused with automatic approval for a building with serious defects.
Request a written explanation of the project characteristic the program accepts. Then compare the interest rate, annual percentage rate, fees, fixed or adjustable structure and any prepayment penalty. Ask how the restriction could affect a future refinance or resale.
A jumbo loan is not automatically a workaround either. A larger loan amount does not, by itself, remove condo eligibility requirements. The lender’s actual project standards still control.
Build the condo file before your deadline gets tight
Ask the lender which documents it needs for this project before ordering records yourself. Requirements differ, and duplicate requests can waste time and money.
To evaluate home buying loan options efficiently, give the lender the property address, unit number, project name, intended occupancy and proposed down payment early. Also disclose any known assessment, lawsuit, inspection finding or insurance concern rather than waiting for underwriting to uncover it.
The project review may require:
- HOA questionnaire: Information about ownership, rentals, delinquencies, litigation and project operations.
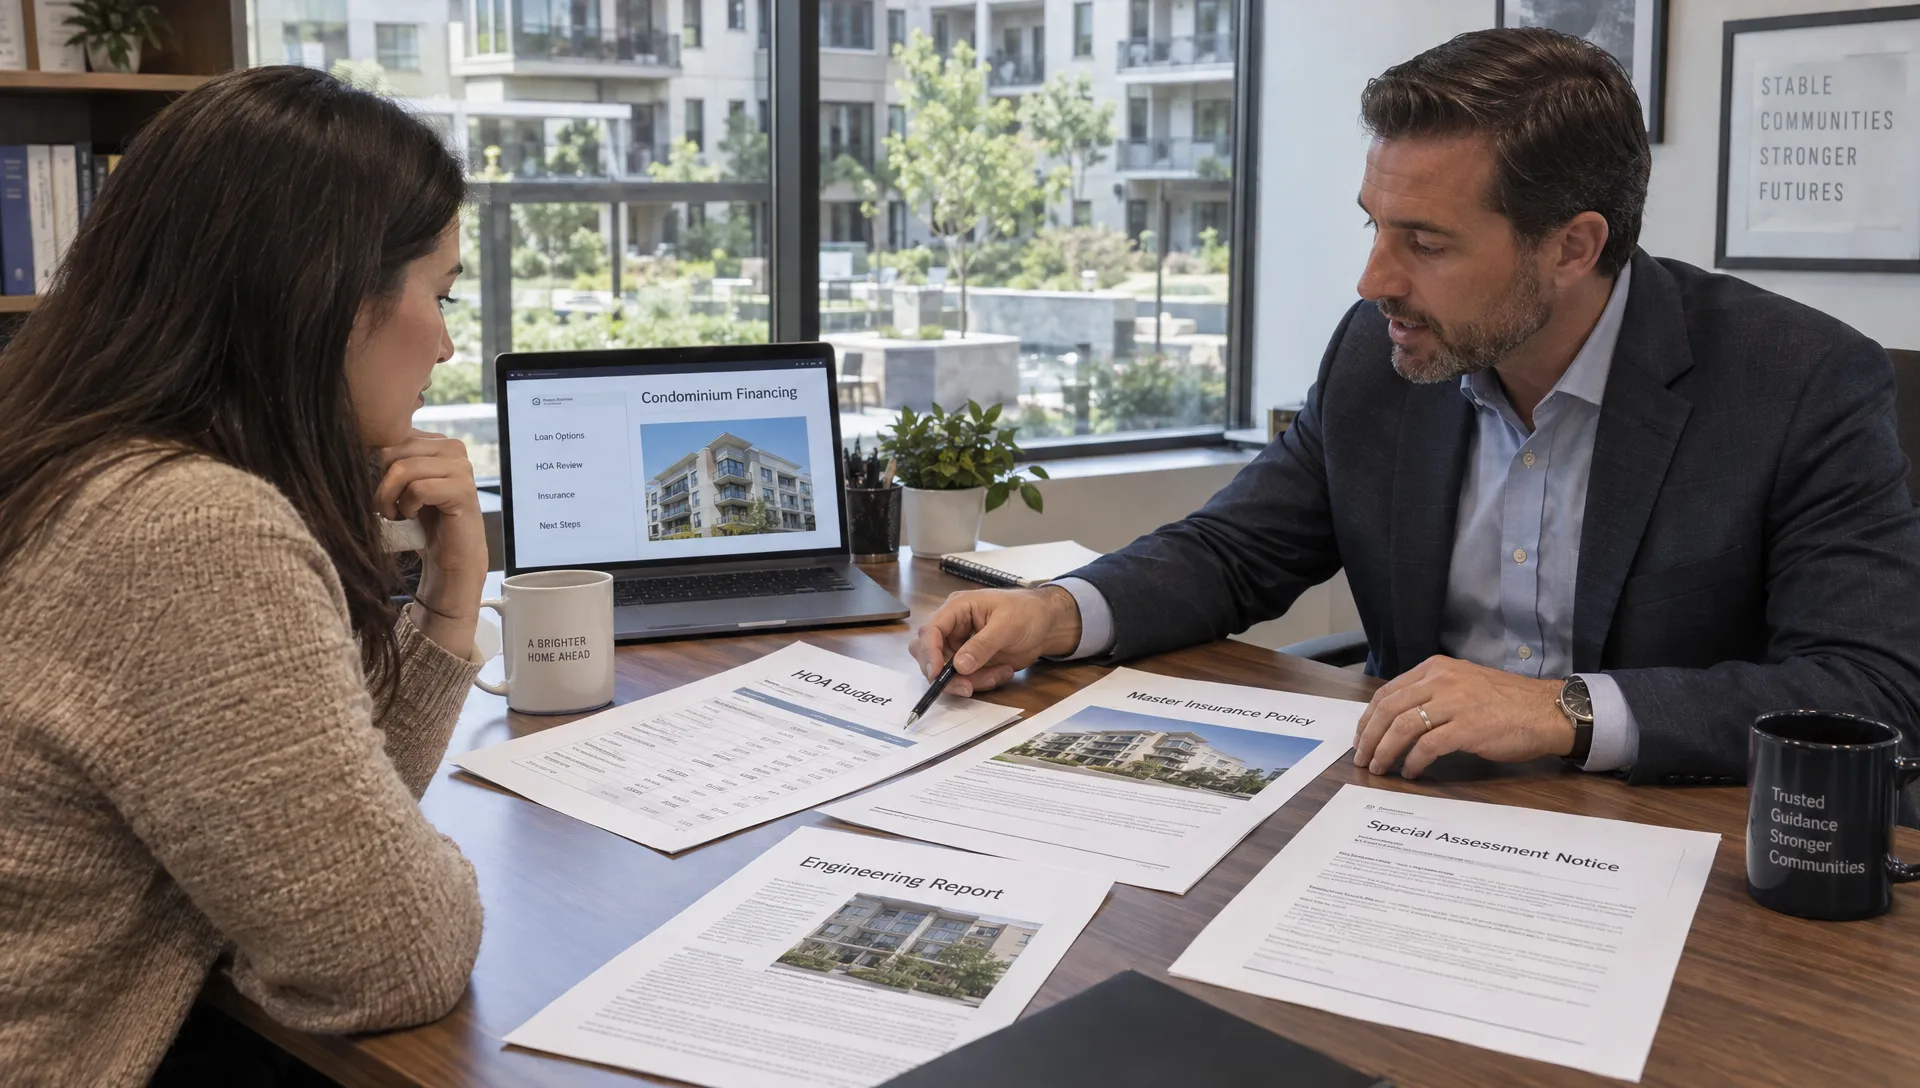
- Financial records: The current budget, financial statements, reserve balances and applicable reserve study.
- Insurance documents: Master policy information and any additional coverage records the lender requests.
- Condition records: Relevant inspection reports, engineering findings, repair plans and assessment notices.
- Governing documents: The declaration, bylaws and other records needed to confirm ownership rights or restrictions.
Recent meeting minutes can also help reveal planned work or disputes that are not obvious from a budget. Ask whether an assessment is proposed, approved, being collected or already spent.
Confirm who orders each document, what it costs and how long the HOA or management company expects to take. A complete file supports a faster decision, but it does not guarantee approval.
Budget for the HOA’s finances as well as your own
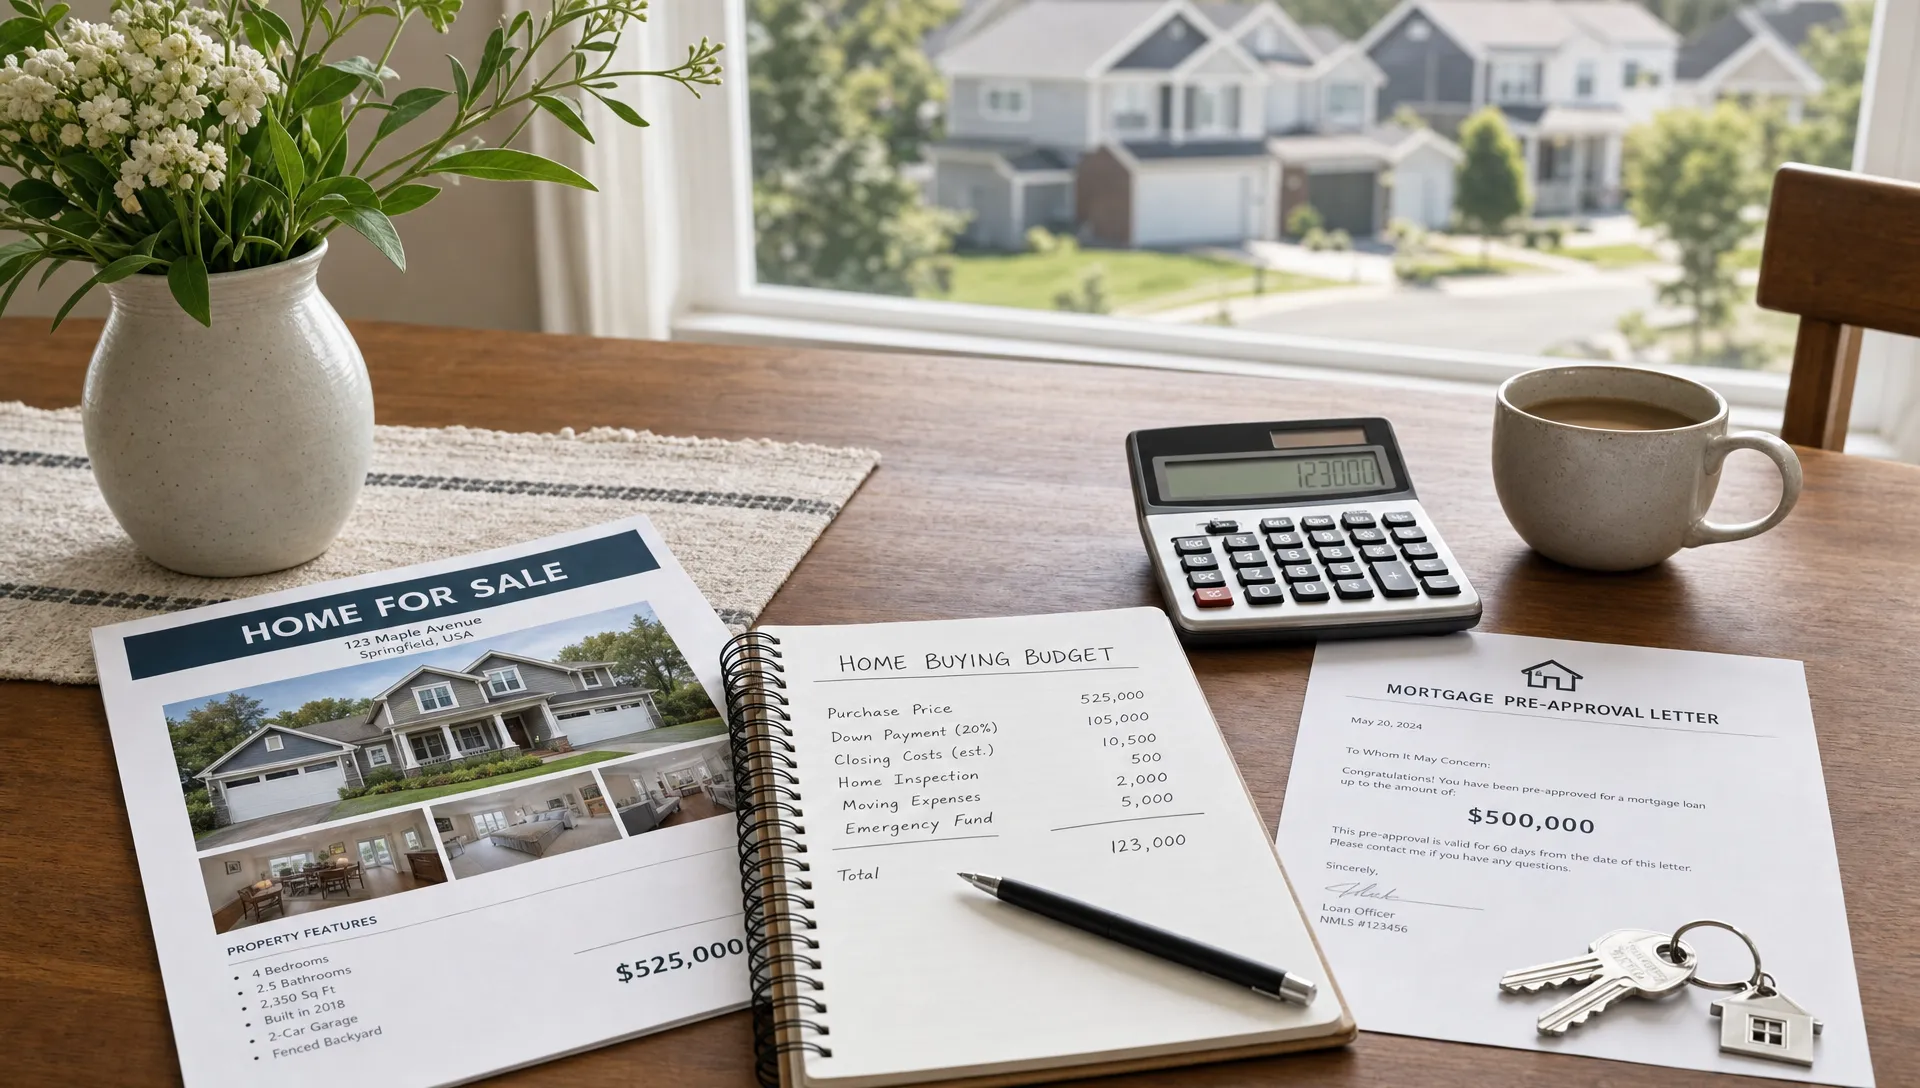
A mortgage payment alone does not capture condo affordability. Include principal, interest, property taxes, applicable mortgage insurance, unit-owner insurance and HOA dues. Add special assessments and any separate required charges.
When comparing home buying loan options, keep money available beyond the down payment. Spending every available dollar to reach a particular loan-to-value ratio can leave you exposed if dues rise or a major assessment arrives after closing.
Review what the HOA dues cover and what remains your responsibility. A master insurance policy does not necessarily replace the unit-owner coverage your lender requires. Ask about deductibles and whether loss-assessment coverage is appropriate with a qualified insurance professional.
Your household obligations also belong in the budget. If you are planning around a possible child support obligation, a state-specific child support estimate can help with preliminary cash-flow planning. It is not a court order, legal advice or a mortgage underwriting calculation. Provide the lender with the applicable legal documents and payment records rather than treating an online estimate as a qualifying figure.
A whole-payment mortgage budget is more useful than comparing interest rates without accounting for these ongoing costs.
What a $400,000 condo illustrates
For a $400,000 purchase, a 3% down payment equals $12,000, 3.5% equals $14,000 and 20% equals $80,000. These are illustrations, not confirmation that a particular condo qualifies for any program.
Some conventional programs allow 3% down for eligible borrowers and properties, while FHA can allow 3.5%. VA financing may require no down payment for an eligible transaction. Closing costs, prepaid expenses and any required reserves are separate.
The practical comparison of home buying loan options must include project approval alongside cash needed to close. A low-down-payment offer is not useful if the lender cannot finance the building.
Suppose the same condo also carries a $15,000 special assessment. Determine who must pay it under the contract, when it is due and whether the underlying work affects eligibility. Even if the seller agrees to pay, the building condition that triggered the assessment may remain a financing problem.
Protect the contract while the project is reviewed
Discuss financing and condo-document contingencies with your real estate agent and, where appropriate, a local real estate attorney. Contract protections and cancellation rights vary by jurisdiction and agreement. Do not assume a borrower preapproval protects your deposit if the project fails review.
Ask how the financing contingency addresses condo eligibility, when document-review rights expire and what notice is required to cancel. Set realistic deadlines based on the HOA’s document turnaround and the lender’s review process.
Before spending more money to pursue additional home buying loan options, ask for a decision checkpoint: What remains unresolved, who can resolve it and what evidence will the lender accept?
A missing insurance endorsement may have a practical solution. An unresolved structural problem without a funded repair plan presents a different risk. Distinguishing those situations helps you decide whether to extend the contract, change programs or leave the transaction.
Financing availability is not the same as a sound purchase. Even if another lender accepts the property, evaluate potential assessments, insurance costs and future buyers’ ability to obtain financing. A smaller pool of eligible buyers can complicate resale.
Frequently asked questions
Can I buy a non-warrantable condo with a mortgage? Sometimes. Certain portfolio or specialized programs accept specific project characteristics that agency programs do not. Approval depends on the reason for the restriction, the lender’s standards and your financial profile. Serious condition issues may still prevent financing.
Does putting 20% down guarantee condo approval? No. A larger down payment may affect pricing or the review path, but it does not automatically resolve project eligibility, inadequate insurance or critical repair concerns. Compare home buying loan options based on the actual restriction rather than down payment alone.
Can an FHA single-unit approval solve an unapproved condo problem? It may provide a path for an eligible unit in an eligible project. It does not waive all project requirements, and lender participation matters. Ask for an eligibility review before assuming this route will work.
Should I pay cash now and refinance later? Only if the purchase works without assuming a future refinance. The restriction may persist, lending standards may change and the unit may not appraise as expected. A later mortgage is a separate approval decision, not a guaranteed exit strategy.
Start with the condo, then choose the loan
Before committing to a restricted condo, gather the project’s known issues and ask for a property-specific financing assessment. The goal is to identify a workable program without overlooking the building’s financial or physical risks.
New Era Lending combines mortgage technology with personalized human guidance. Discuss your borrower profile, the condo’s restrictions and your closing timeline, then ask which available programs merit a closer review. Confirm project eligibility and full costs before treating any option as a solution.