Can You Get a Loan for the Purchase of a Vacation Home?
Yes, you can get a loan for purchase of a vacation home, usually through a conventional second-home mortgage. Approval depends on more than whether you can afford another monthly payment. The lender will also consider how you plan to use the property, your existing debts, available savings and whether the home meets its requirements.
The main distinction is personal use versus investment use. A weekend retreat and a full-time vacation rental may require different financing, even when they are the same type of property.
Is the property a second home or an investment?
For mortgage purposes, calling a property a vacation home does not determine its classification. Its intended use does.
Under Fannie Mae’s second-home requirements, the property generally must be a one-unit dwelling suitable for year-round occupancy. You must occupy it for part of the year and retain exclusive control over it. Timeshares and arrangements that give a management company control over occupancy do not meet those requirements.
A mountain cabin you visit throughout the year may qualify. A beach house operated primarily as a short-term rental may need investment-property financing instead. Seasonal access, unusual ownership arrangements or a condo-hotel structure can also complicate eligibility.
Describe your intended use accurately before requesting quotes. Changing from second-home financing to investment financing later can affect pricing, documentation and the down payment.
What does a loan for purchase of a vacation home require?
Down payment and loan-to-value ratio
Some conventional second-home programs allow qualified borrowers to put down as little as 10%. That is not a universal minimum: the lender, property type, loan size and borrower profile can require more.
A 10% down payment produces a 90% loan-to-value ratio, or LTV. On a $450,000 property, that means putting down $45,000 and borrowing $405,000, before any financed costs.
With 20% down, the loan would be $360,000 and the LTV would be 80%. That generally avoids borrower-paid private mortgage insurance on a conventional loan, but it also ties up more cash. Preserving an emergency fund may be more valuable than putting every available dollar into the property.
Credit, income and existing debts
When reviewing a loan for purchase of a second home, lenders assess your credit history, documented income and debt-to-income ratio, or DTI. The required credit profile varies by program and lender, so a published minimum score is not a promise of approval.
DTI compares qualifying monthly debt payments with gross monthly income. Your existing housing payment generally remains part of that calculation, along with the proposed vacation-home payment and obligations such as car loans or student loans.
If your primary residence is paid off, its property taxes, insurance and applicable association dues still matter. Self-employed borrowers and applicants with variable income may need additional documentation to establish stable qualifying income.
Savings beyond the down payment
Lenders may require cash reserves after closing, measured in months of qualifying housing payments. The amount depends on underwriting requirements, including how many other financed properties you own.
Keep three categories separate: your down payment, closing costs and remaining reserves. A balance that looks sufficient for the down payment may not cover all three.
Not every asset is treated identically. Ask which bank, investment or retirement accounts can count and what documentation is required before transferring funds between accounts.
Which mortgage options work for a vacation home?
A conventional second-home mortgage is a common loan for purchase of a vacation property intended mainly for personal use. Both fixed-rate and adjustable-rate structures may be available, depending on the lender.
A fixed-rate mortgage keeps principal and interest predictable. An adjustable-rate mortgage introduces future payment uncertainty, so compare its adjustment schedule and caps rather than focusing only on the starting rate.
If the amount you need exceeds the applicable conforming loan limit, a jumbo mortgage may be an option. Requirements vary, and some programs call for larger down payments or more reserves.
FHA, VA and USDA purchase programs generally require a primary residence, rather than a home bought solely for vacations. Eligible veterans should distinguish the VA loan occupancy rules from conventional second-home rules before choosing a program.
A home equity loan or HELOC on your current residence is another possible funding source. However, it adds debt secured by that home and must be disclosed during underwriting.
What would the monthly payment look like?
Before choosing a loan for purchase of a vacation home, estimate the complete ownership cost, not just principal and interest.
Here is a hypothetical example, not a rate quote or an offer of credit. It assumes a $450,000 purchase, 20% down and a fully amortizing, 30-year fixed mortgage at a 7% interest rate. The interest rate is not an APR.
| Item | Illustrative amount |
|---|---|
| Purchase price | $450,000 |
| Down payment | $90,000 |
| Mortgage amount | $360,000 |
| Monthly principal and interest | About $2,395 |
| Monthly property taxes | $400 |
| Monthly homeowners insurance | $200 |
| Monthly association dues | $150 |
| Estimated monthly total | About $3,145 |
The tax, insurance and association figures are assumptions, not estimates for a particular location. Actual costs can differ substantially, especially in coastal, wildfire-prone or resort markets.
This total also excludes utilities, maintenance, furnishings and travel. It does not include closing costs or special assessments. A property that appears affordable at the mortgage-payment level may feel very different after those expenses are included.
Budget for the home when you are not there
An unoccupied property still needs attention. Consider leak monitoring, winterization, landscaping, snow removal and someone who can respond to an urgent repair. Confirm that the insurance policy matches the home’s actual occupancy and any rental activity.
Your loan for purchase should leave room for these ongoing expenses, rather than consuming your entire discretionary budget.
Optional improvements deserve a separate allowance. If you plan to add a hot tub or sauna, this guide to budgeting and financing a major home wellness purchase covers installation, site preparation and operating expenses that can be easy to overlook.
Avoid opening new financing for those additions during mortgage underwriting without first speaking with your loan professional. New debt can change your qualification.
Can you rent out the home when you are away?
Occasional rentals do not automatically determine the mortgage classification. The property must still satisfy the applicable second-home requirements, and the lender must understand the intended arrangement.
Do not assume projected vacation-rental income will help you qualify for a standard second-home mortgage. Under Fannie Mae’s second-home rules, rental income cannot be used to qualify. Other financing structures have their own requirements.
If reliable rental revenue is essential to making the numbers work, discuss investment-property loan options before making an offer. A loan for purchase of a rental-focused property should match that business purpose from the beginning.
Also investigate local short-term rental ordinances, permit requirements and association restrictions. Mortgage approval does not grant permission to rent. An otherwise eligible property may prohibit short stays or limit the number of rental permits available.
For your personal budget, test whether you could carry the home through several months without bookings. Rental demand, repair downtime and local rules can change.
How to prepare before making an offer
Get a second-home financing review
Tell the lender that you are considering a vacation home, rather than requesting a generic purchase preapproval. Share your planned personal use, possible rentals, target price and current housing obligations.
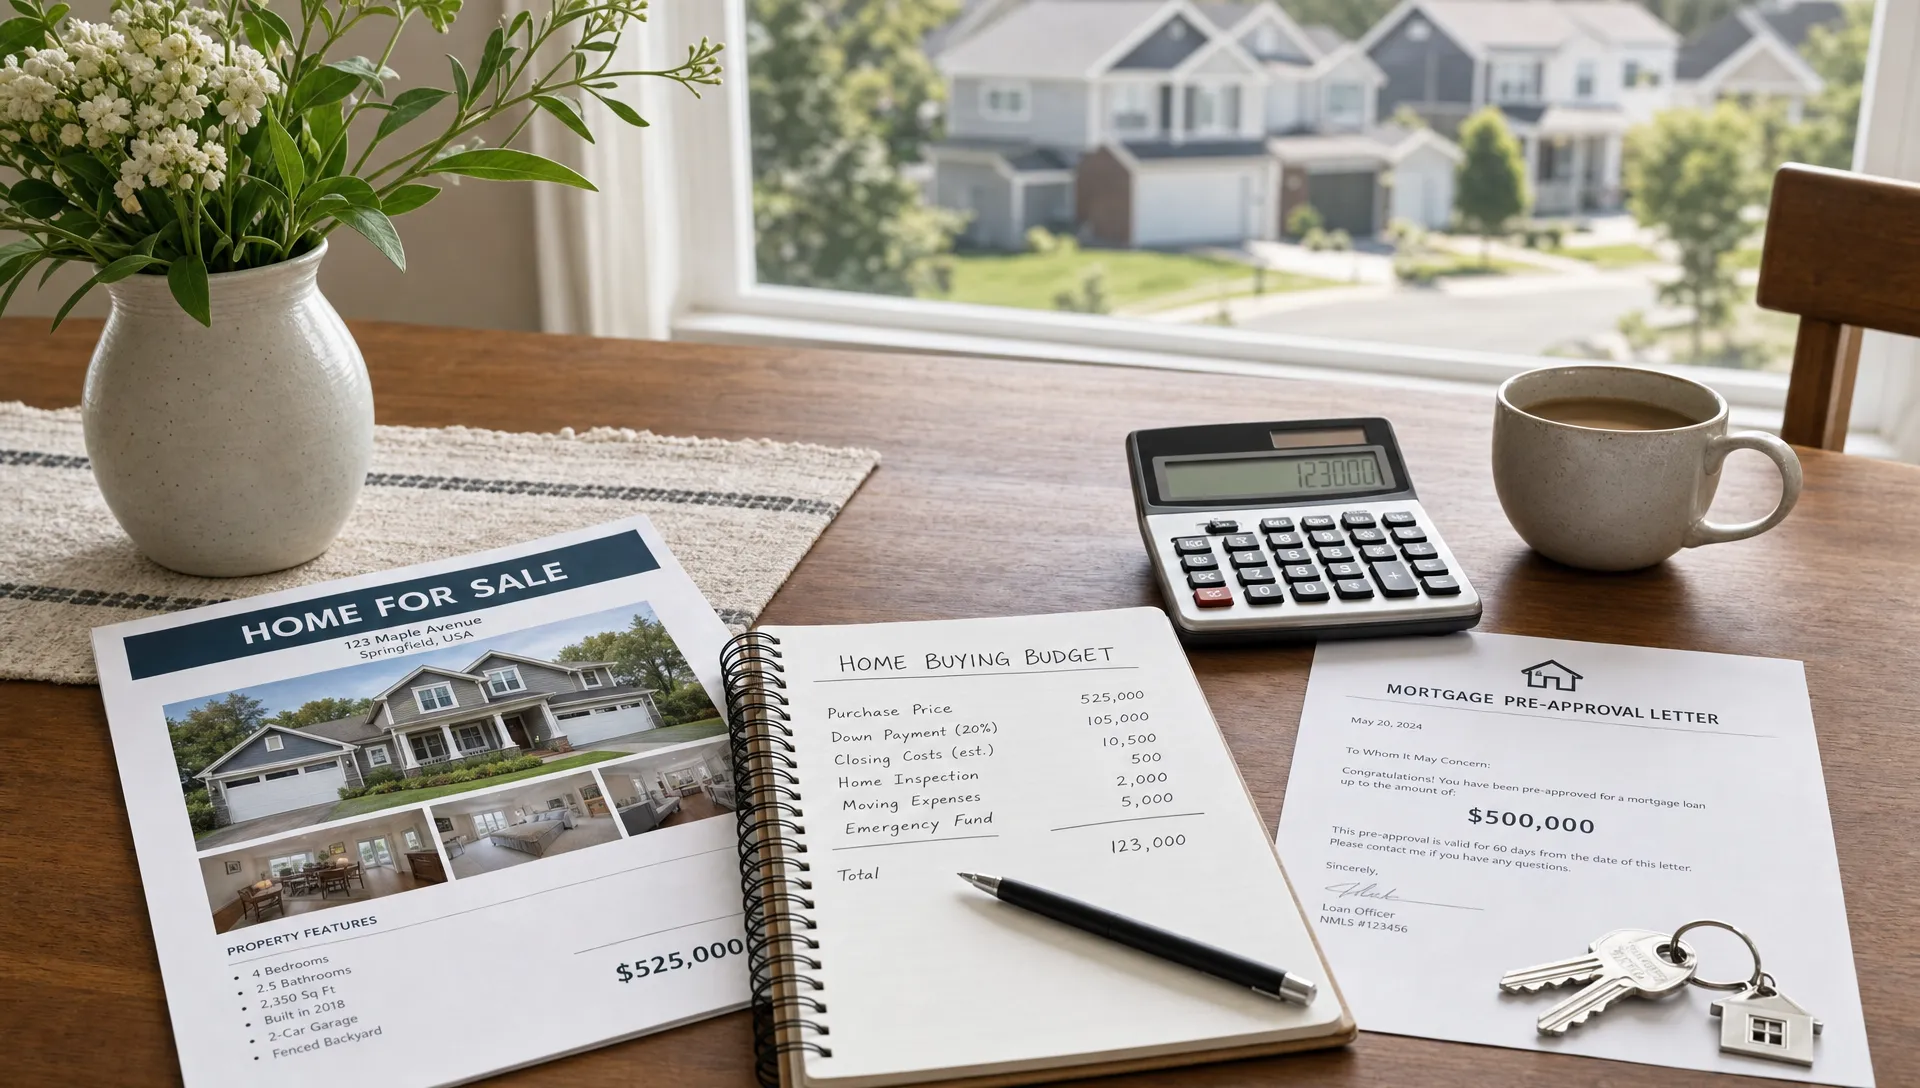
A useful review identifies the likely occupancy classification, down payment range, reserve requirements and documentation needs. Ask what assumptions remain unresolved. Preapproval is not final approval, and the property itself must still qualify.
Gather recent income records, account statements and information about other real estate you own. Documenting the source of a large deposit early can prevent delays later.
Investigate the property before contingencies expire
A loan for purchase can be delayed by property issues even when the borrower is well qualified. Ask early about year-round access, utilities, insurability and any unusual ownership structure.
For a condo, the lender may need to review the project as well as the individual unit. Hotel-style operations, financial problems or significant building concerns can affect available financing.
Obtain insurance quotes early, particularly where flood, wind or wildfire coverage may be costly or difficult to secure. A standard homeowners policy generally does not cover flood damage, and separate coverage may be required.
Coordinate financing, appraisal and inspection deadlines with your real estate agent. Avoid assuming that approval for one property guarantees approval for another.
How to compare vacation-home mortgage offers
Compare offers using the same occupancy classification, down payment and loan structure. A quote for a primary residence is not a useful substitute for a second-home quote.
For a loan for purchase of a vacation home, review the interest rate alongside discount points, lender fees, mortgage insurance and estimated cash to close. A lower rate can come with higher upfront costs, so consider how long you expect to keep the loan.
The Consumer Financial Protection Bureau’s Loan Estimate guide explains where to find the payment, closing costs and comparison figures on the standardized form. Once you receive Loan Estimates, compare them rather than relying solely on advertising or preliminary worksheets.
Ask whether the rate is locked, when the lock expires and which costs could change. For an adjustable-rate mortgage, also review when adjustments begin and how high the payment could rise under the loan terms.
Finally, compare affordability without assuming that you will refinance later. A future refinance depends on rates, equity and your financial circumstances at that time.
Frequently asked questions
Can I buy a vacation home with 10% down? Some conventional second-home programs permit 10% down for eligible borrowers and properties. Other situations require more. Credit, loan size, reserves and lender requirements all affect the result, and mortgage insurance may apply when the down payment is below 20%.
Is an 80% LTV good for a vacation-home mortgage? An 80% LTV means the mortgage equals 80% of the property value used for underwriting. It generally avoids borrower-paid private mortgage insurance on a conventional loan. Whether it is the right choice also depends on the savings you would have left after closing.
Can I get a loan for purchase if I still have a mortgage on my main home? Yes, provided you qualify while accounting for both properties and your other debts. The lender will review income, credit, assets and applicable reserve requirements. Owning a primary home outright is not normally required.
Are vacation-home mortgage rates higher? Second-home financing often costs more than comparable primary-residence financing because occupancy affects loan pricing. The difference varies with market conditions, credit, LTV and the lender. Compare personalized quotes rather than assuming a fixed rate premium.
Does a vacation home have to be a certain distance from my primary home? There is no single mileage rule that applies to every lender and program. The location and intended use must support the second-home classification. Ask about lender-specific distance or location requirements before committing to a nearby property.
Explore financing that matches your plans
Start with how you will use the property, then build a budget that includes both homes, closing costs and a realistic savings cushion.
New Era Lending combines technology-driven mortgage tools with personalized human guidance. Discuss your vacation-home plans, existing obligations and available down payment to explore financing options that fit your circumstances. Available programs and approval depend on borrower eligibility, property requirements and location.