How to Choose an Equity Lending Provider for Renovations
Choosing an equity lending provider for renovations means looking beyond the lowest advertised rate. The lender’s payment structure, fees and funding schedule need to fit the work you are planning, whether that is a roof replacement or a kitchen remodel with several contractor payments.
Your home secures the debt, so missed payments can lead to foreclosure. A renovation that improves the property does not remove that risk or guarantee that you will recover the project cost when you sell.
A useful comparison starts with a defined project budget, then tests each provider against the same requirements. Here is how to evaluate offers without letting a large approval amount or a low introductory payment drive the decision.
Start with a scope and a borrowing ceiling
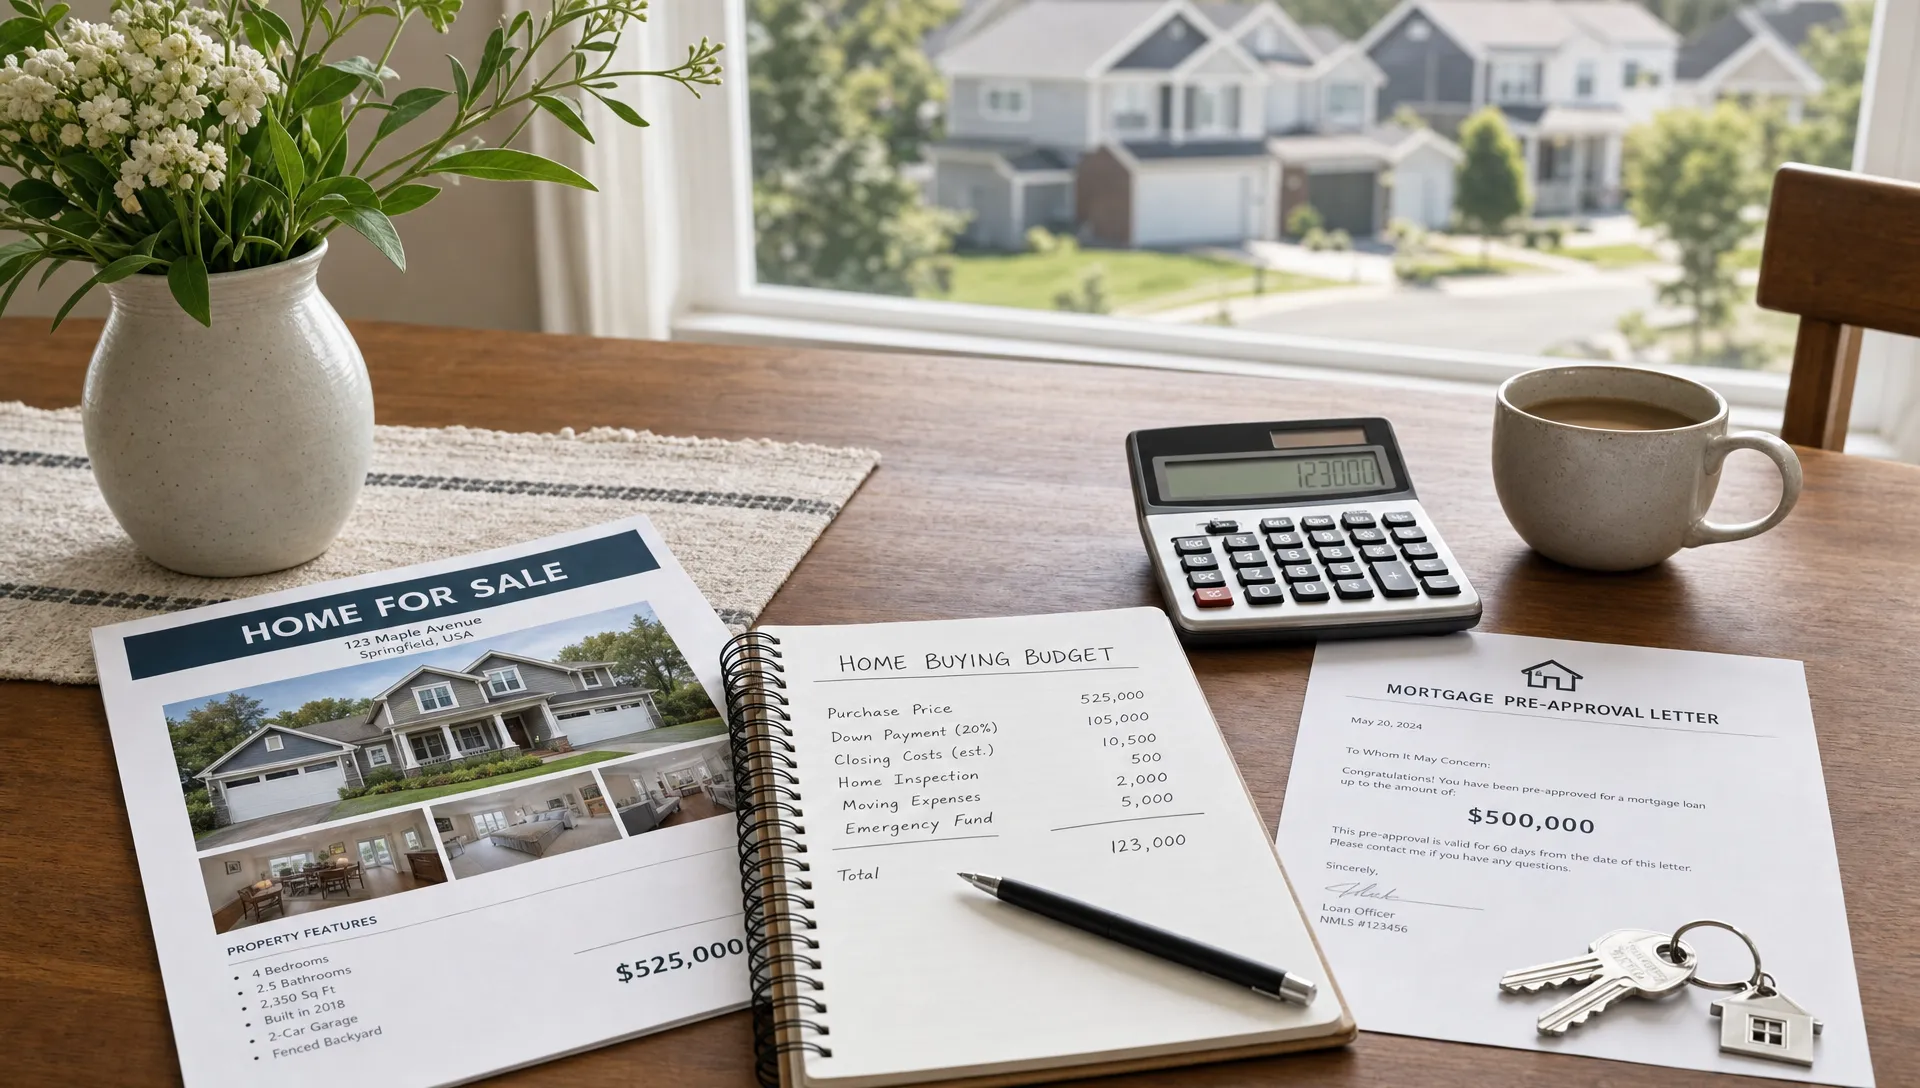
Before contacting lenders, obtain itemized estimates that separate labor, materials, permits and payment milestones. Identify work that must happen now and upgrades you could postpone. A signed fixed-price contract and an exploratory estimate create different financing needs.
For equity lending to support the renovation rather than expand it, set your borrowing ceiling before you hear how much a provider might approve. Include a project contingency, but keep household emergency savings separate.
For example, $45,000 of planned work plus a $4,500 contingency creates a $49,500 project budget before financing costs. That reserve is an illustration, not a universal recommendation. Its size should reflect uncertainty about hidden damage, materials and the condition of your home.
Roofing projects deserve particularly clear estimates. The service breakdown from YG Étanchéité, a roofing and waterproofing specialist in Réunion, illustrates how diagnosis, waterproofing, roof covering and maintenance are distinct tasks. For a U.S. renovation, obtain local estimates and verify applicable contractor licensing, permits and insurance.
Finally, ask whether lender fees will be paid separately or deducted from the loan proceeds. An approved amount of $50,000 does not necessarily leave $50,000 available for construction.
Match the financing structure to the renovation
A provider should explain why a particular product fits your project, not simply offer whichever product is easiest to sell. The main equity lending options differ in how you receive money and repay it.
| Financing option | Potential renovation fit | Main issue to evaluate |
|---|---|---|
| Home equity loan | A defined project with a known upfront cost | Usually provides a lump sum with fixed payments, but interest generally begins on the full funded balance |
| Home equity line of credit (HELOC) | Work completed in stages with uncertain payment dates | Allows borrowing during a draw period, but rates are commonly variable and later payments can increase |
| Cash-out refinance | A renovation considered alongside replacing the existing mortgage | Changes financing on the full mortgage balance, not just the renovation funds |
A second mortgage can preserve your existing first-mortgage terms, though it adds another payment. A cash-out refinance may simplify payments, but replacing an attractive existing mortgage can make the overall transaction expensive.
For a closer product comparison, review the differences between a home equity loan and a HELOC.
Ask each provider whether you can qualify using the home’s current condition and value. Do not assume a standard equity product will lend against the renovation’s projected future value. If the property needs major structural repairs, ask whether renovation-specific financing would be more suitable.
Compare equity lending providers using identical assumptions
Request written quotes from more than one provider using the same loan amount, repayment term, property information and intended use. Otherwise, a lower payment may simply reflect a longer repayment period or a temporary introductory rate.
Make sure the comparison captures these details:
- Rate structure: Fixed or variable, introductory period, rate-lock terms and any conditions required to receive the quoted rate.
- Upfront charges: Origination fees, points, appraisal charges, title costs and other closing expenses.
- Ongoing or exit costs: Annual fees, inactivity charges, prepayment terms and repayment of lender-paid closing costs after early closure.
- Usable funds: The amount available for the renovation after fees and any required debt payoffs.
Also ask whether automatic payments or another banking relationship is required for a discount. A rate that depends on conditions you will not maintain is not the rate to use in your budget.
Keep quotes dated. Offers obtained weeks apart may reflect different market conditions rather than a meaningful difference between providers.
Understand which disclosures you should receive
For most closed-end home equity loans and cash-out refinances, lenders provide a standardized Loan Estimate after receiving a qualifying application. The CFPB’s Loan Estimate guide explains the form’s major sections.
HELOCs use different disclosures. Ask for the opening disclosures and agreement showing the index, margin, rate caps, draw period, repayment period and applicable fees.
When comparing equity lending offers, do not assume APR works identically across products. A closed-end loan’s APR reflects certain financing charges, while a HELOC’s disclosed APR generally reflects the interest rate without incorporating closing costs in the same way.
Compare total dollar costs as well as rates. If you expect to repay the renovation debt early, ask each provider to show the balance and costs at that expected payoff date, not just at the end of the full term.
Test the payment against your household budget
Approval tells you what a lender is willing to offer, not what your household can comfortably sustain. Add the proposed payment to your existing mortgage, property taxes, insurance, other debts and normal savings commitments.
The following examples illustrate fully amortizing loans at a hypothetical 9% fixed annual interest rate over 10 years. They are not current offers or New Era Lending quotes.
| Amount borrowed | Approximate monthly principal and interest |
|---|---|
| $10,000 | $127 |
| $30,000 | $380 |
| $50,000 | $633 |
These figures exclude fees, taxes and insurance. Actual pricing depends on the product, borrower, property and lender.
An equity lending offer with a longer term may reduce the monthly payment while increasing total interest. Ask for both the monthly obligation and the total scheduled repayment, then consider whether you want to keep paying for the improvement that long.
If cash flow is already tight, use this guide to accessing home equity without straining your budget before increasing the requested amount.
Stress-test delays and changing HELOC payments
For a HELOC, request more than an estimate of the initial minimum payment. Ask the provider to calculate payments on your expected balance at today’s rate, at a meaningfully higher rate and when the repayment period begins.
Some plans permit interest-only payments during the draw period. Those payments do not reduce principal, and the later repayment obligation can be substantially larger. Confirm your plan’s actual terms rather than assuming all lines work alike.
Also model a construction delay. You may be paying interest while a room remains unusable or while you are covering temporary housing. A lender should explain the borrowing cost, but your renovation budget must account for those separate expenses.
Before signing an equity lending agreement, decide how you would handle a cost overrun without depending on another loan approval. Possible responses include reducing optional finishes, postponing a second phase or using a designated project reserve.
Verify funding dates and contractor payment rules
Ask the provider to separate estimated application processing, appraisal, underwriting, closing and disbursement dates. An approval is not the same as spendable funds.
For many non-purchase loans secured by a primary residence, a federal three-business-day right of rescission applies. The timing depends on signing and receiving required disclosures and cancellation notices. Ask whether it applies to your transaction and when funds can actually be released.
A contractor’s deposit deadline should not depend on an optimistic closing estimate. Confirm payment milestones before authorizing work or ordering nonreturnable materials.

Some financing arrangements release funds directly to the homeowner, while others may involve inspections, contractor requirements or controlled disbursements. Have the provider explain the process for the specific product being offered. Do not assume a standard HELOC includes construction oversight.
Ask about minimum draws, transfer methods and how quickly a withdrawal becomes available. HELOC access may also be reduced or frozen under circumstances allowed by the agreement and applicable law. An unused credit limit is not identical to cash already held in an account.
Check the provider, not just the sales pitch
Verify the company’s legal name and the individual loan originator’s registration or licensing information through NMLS Consumer Access. Confirm that the provider is authorized to handle your transaction in your state. A legitimate registration does not, by itself, establish that an offer is competitive.
Then evaluate how the provider responds to specific questions. A useful equity lending conversation should produce clear explanations of costs, qualification requirements and next steps, with important terms supplied in writing.
Ask who will handle the file after application, how you will receive updates and who can resolve an issue if an appraisal or title problem delays closing. A responsive salesperson is helpful, but the processing and closing handoffs matter too.
Use the provider’s designated secure document-upload process for sensitive records. Verify unexpected changes to payment or wiring instructions through a trusted, independently confirmed phone number.
Be cautious if someone pressures you to sign before reviewing disclosures, guarantees approval before verification or encourages borrowing beyond your stated project budget. Also question any arrangement in which a contractor insists you use one lender without giving you a reasonable opportunity to compare alternatives.
Make the final choice with a short scorecard
Reduce the decision to five categories: payment affordability, total cost, funding reliability, flexibility and service quality. Compare each provider against your project’s actual constraints rather than against a generic promise of convenience.
For a fixed-price roof replacement, predictable payments and a reliable funding date may matter most. For a phased renovation, access rules and the cost of carrying an unused line may deserve more weight.
The best equity lending provider for your project is not necessarily the one offering the largest limit. It is the one whose written terms fit the amount you need, the dates you need it and the payment you can sustain.
Before choosing, ask your preferred provider to resolve every blank or conditional item in the quote. Confirm whether the rate is locked, which fees can change and what could still prevent closing.
Keep the financing decision separate from contractor selection. Lender approval does not verify workmanship, establish that a contractor’s price is fair or guarantee that the renovation will increase your home’s value. Review the construction contract and ask about permits, inspections and appropriate lien releases as the work progresses.
Frequently asked questions
How much would a $50,000 home equity loan cost per month? At a hypothetical 9% fixed annual interest rate over 10 years, principal and interest would be approximately $633 per month. Fees and other housing expenses are additional. Different rates or repayment terms change the payment.
Can I use equity lending for a roof replacement? Generally, home equity proceeds can be used for roof work, subject to the product’s terms. Ask whether the roof’s current condition affects the appraisal, eligibility or funding process before committing to a contractor’s schedule.
Should I choose the provider with the lowest rate? Not automatically. Compare fees, repayment length, variable-rate exposure and the amount you actually receive. A slightly lower rate may not offset higher upfront charges, particularly if you plan to repay the debt quickly.
What happens if the appraisal is lower than expected? The provider may reduce the available amount or decline the application because borrowing limits depend partly on property value and existing secured debt. Ask how appraisal disputes are handled and decide in advance which project elements you could postpone if financing falls short.
Discuss your renovation financing needs
Bring your contractor estimates, existing mortgage details and target monthly payment to a financing conversation. Ask for a written explanation of available products, net proceeds, costs and the expected funding timeline.
New Era Lending combines technology-driven mortgage tools with personalized human guidance for home financing and equity access. Ask which options are available for your state, property and renovation plan, then compare the written terms before committing.