


Simple Refinance: 7 Steps to Lower Costs Without Surprises
A simple refinance should leave you with more than a lower advertised rate. It should improve your finances after fees, mortgage insurance and the new repayment schedule are accounted for. A smaller monthly payment can still cost more over time if you restart a long loan term or add closing costs to your balance.
These seven steps focus on cost controls: what to compare, which numbers to verify and when to pause before committing. You do not need to predict the next rate move. You need an offer that works for your budget and the length of time you expect to keep the mortgage.
1. Define the savings you actually want
Choose one primary goal before requesting quotes. You might want a lower required payment, less total interest or the removal of mortgage insurance. Those goals can lead to different loan choices, so “save money” is not specific enough.
Pull your latest mortgage statement and record your balance, interest rate, remaining term and monthly principal and interest. Separately identify mortgage insurance, property taxes and homeowners insurance. Taxes and insurance generally remain expenses after refinancing, even if the new escrow payment looks different.
For a simple refinance, write your target as a measurable outcome, such as lowering the loan-related monthly payment without extending the payoff date. That gives you a standard against which to judge every offer.
Also set a limit on the cash you can comfortably bring to closing. Using most of your emergency fund to secure a lower rate can leave you vulnerable to repairs or an income interruption.
If payment relief is your priority, New Era Lending’s guide to lowering rates without hurting your budget provides additional context on balancing savings with upfront expenses.
Checkpoint: Write down your desired payment, maximum upfront expense and expected holding period before comparing lenders.
2. Check eligibility before paying application-related expenses
An attractive quote is not useful if it assumes a credit profile, property value or loan type that does not match your situation. Ask which assumptions support the proposed pricing and what could change after underwriting.
Start with your estimated equity. For example, a $240,000 mortgage balance on a home estimated at $300,000 produces an estimated 80% loan-to-value ratio before financed costs. The lender’s accepted valuation, not an online estimate, determines the ratio used for approval.
A simple refinance becomes easier to evaluate when the lender explains how credit, equity and mortgage insurance affect the offer. Ask whether the proposal assumes an appraisal waiver, whether mortgage insurance applies and whether your current loan has a prepayment penalty.
Before authorizing an appraisal or another paid service, confirm the charge, when it becomes due and whether it is refundable. An appraisal fee may remain your responsibility even if the transaction does not close.
Avoid opening new credit accounts or making major financed purchases during the application process. Also tell your loan professional about upcoming employment changes early, rather than waiting for a verification request.
Checkpoint: Get a clear explanation of eligibility assumptions and potential out-of-pocket charges before ordering services. Do not treat an initial quote as a final approval.
3. Compare matching offers, not just interest rates
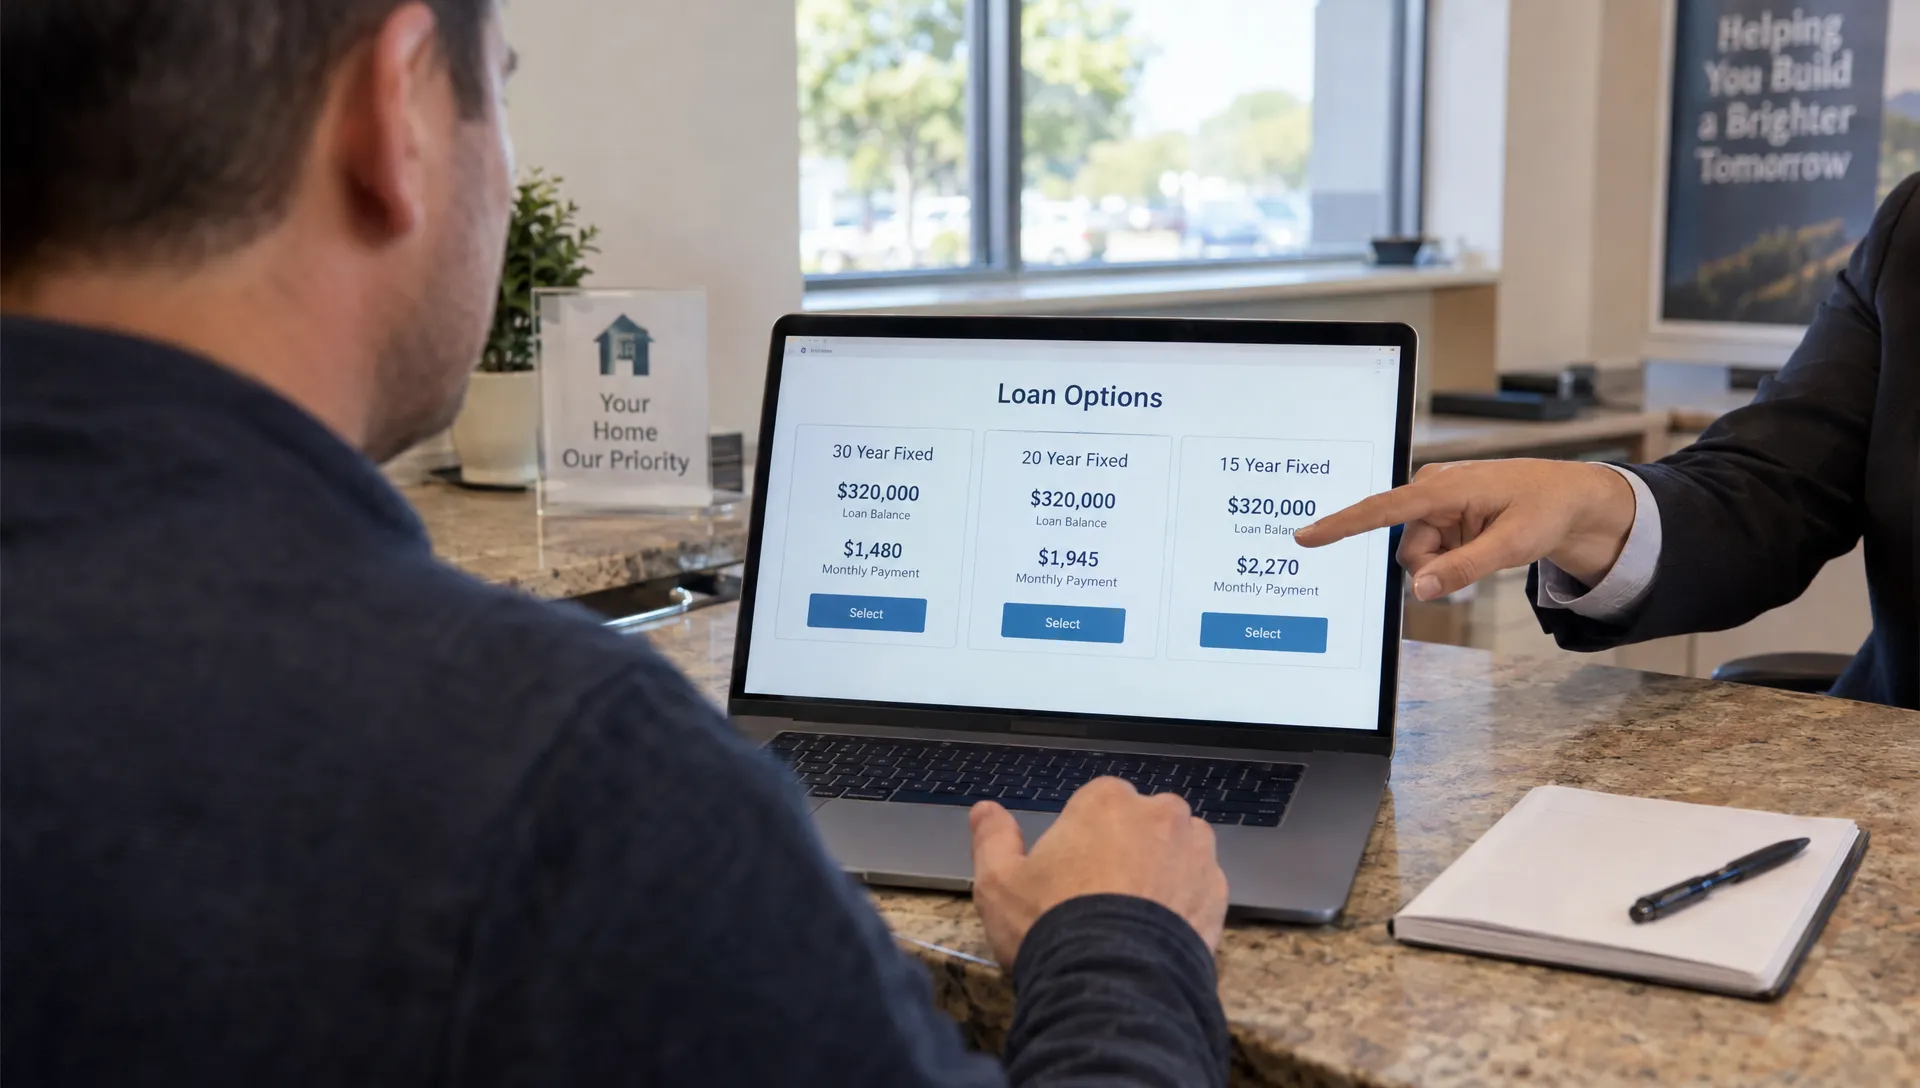
Request quotes for the same loan amount, loan type, term and rate-lock period. Compare them as close together in time as practical because pricing can change. A 15-year offer and a 30-year offer answer different questions, even when one has a noticeably lower rate.
Ask for a no-points option alongside any offer that includes discount points. Points are upfront charges used to reduce the interest rate. Lender credits generally work in the opposite direction: accepting a higher rate may reduce the money required at closing.
For a simple refinance, compare both the monthly payment and the price of obtaining it. A rate that requires substantial points may not suit someone who expects to sell or refinance again soon.
The Consumer Financial Protection Bureau’s Loan Estimate explainer shows where to find the interest rate, projected payments, closing costs and rate-lock information. Lenders generally must provide a Loan Estimate within three business days of receiving an application.
APR is useful context, but it does not replace a comparison based on your expected holding period. Likewise, the lowest cash-to-close figure does not necessarily identify the least expensive loan.
For more detail on matching quote assumptions, review how to compare home refinance rates.
Checkpoint: Confirm that the offers use matching assumptions, then identify what you pay for each rate.
4. Check whether a simple refinance pays for itself
Separate transaction costs from money needed to fund expenses you would owe anyway. Origination charges, points and title-related fees are transaction expenses. Prepaid interest and escrow deposits affect closing cash, but they should not automatically be treated as equivalent costs in a savings calculation.
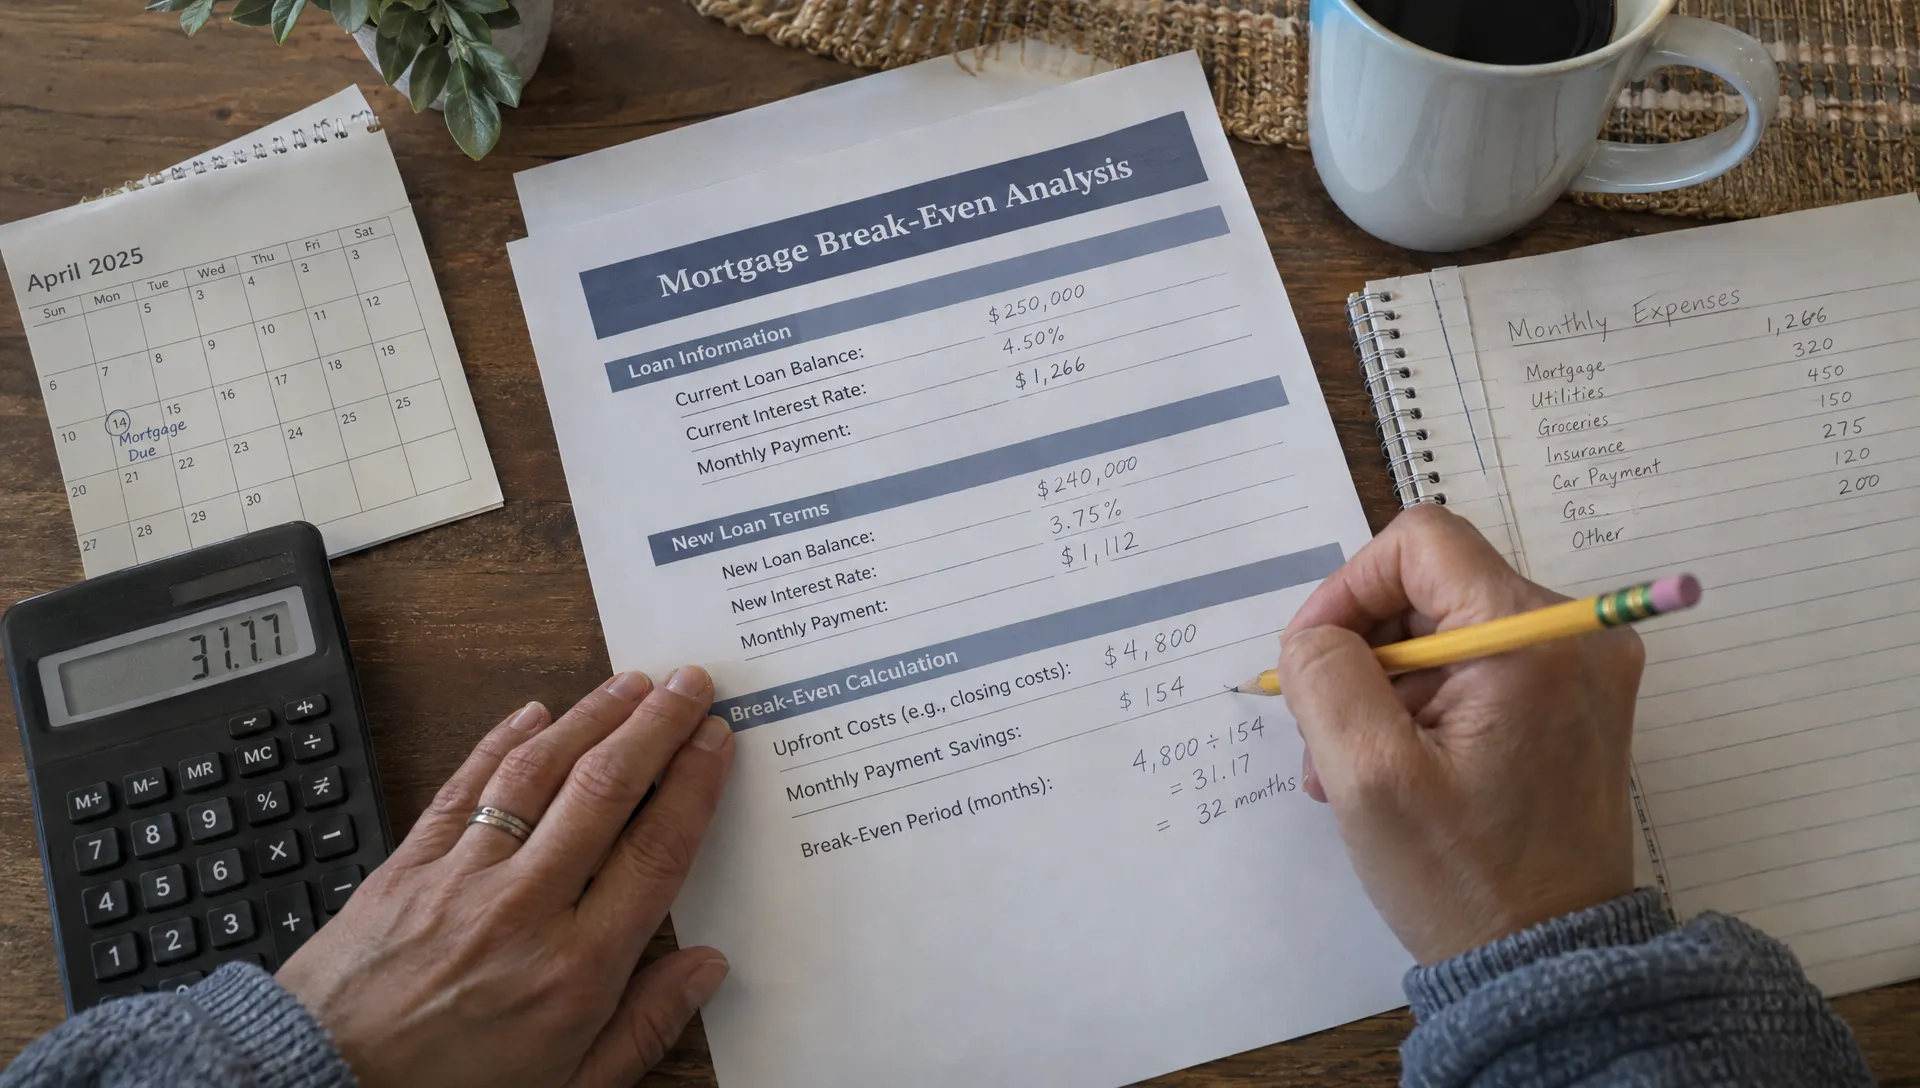
Consider this hypothetical example. Assume the remaining repayment term stays the same, mortgage insurance does not change and transaction costs are paid upfront.
| Planning item | Illustrative amount |
|---|---|
| Current monthly principal and interest | $1,600 |
| Proposed monthly principal and interest | $1,450 |
| Monthly payment savings | $150 |
| Net transaction costs after lender credits | $3,600 |
| Separate prepaid items and escrow funding | $1,400 |
| Cash needed for those two closing categories | $5,000 |
| Simple transaction-cost break-even | 24 months |
The calculation is $3,600 ÷ $150 = 24 months. If you keep the loan for only 18 months, the $2,700 in payment savings would not recover the transaction costs.
This shortcut has limits. If you extend the term, finance the fees or change loan types, compare projected interest and remaining balances at your expected sale or refinance date too. Lower payments are not always equivalent to economic savings.
Ask about the expected refund of your existing escrow balance, but do not count that refund as refinance savings or assume it will arrive before closing.
Checkpoint: Verify both the break-even date and the cash required. They answer different questions.
5. Prepare documents once and protect your information
A simple refinance should not require you to guess what the lender needs. Request a document checklist tailored to your employment, income and property, then submit complete files rather than cropped screenshots or partial statements.
Common requests include income records, bank statements, identification, your current mortgage statement and homeowners insurance information. Self-employed borrowers may need additional business and tax documentation. Requirements vary by loan program and underwriting findings.
Keep a small tracking sheet with the document requested, date submitted and any follow-up needed. If the lender requests an updated statement, confirm whether the original is outdated or whether something was missing. That distinction helps prevent repeated work and avoidable delays.
New Era Lending offers secure document uploads and e-signature support. Use the verified submission channel provided by your loan professional rather than sending sensitive files through unfamiliar links.
If phone storage or an app problem is blocking document preparation, TechSocial’s everyday phone and app troubleshooting guides offer general device help. Keep mortgage documents within your lender’s verified channel, regardless of which device you use.
Checkpoint: Confirm receipt of the required files and ask which outstanding items could delay underwriting or closing. Avoid sending duplicate versions unless the lender requests them.
6. Match the rate lock to a realistic closing schedule
A simple refinance can become more expensive if the rate lock expires before the loan is ready to close. Before locking, ask whether the proposed period accounts for underwriting, any appraisal, title work and your own availability to sign.
Get the lock terms in writing. Confirm the rate, points or credits, expiration date and whether a lock fee applies. If an offer is not locked, the quoted rate and pricing may change.
Ask what happens if the closing is delayed. An extension may carry a charge, and responsibility for that charge can depend on the circumstances and lender policy. Do not assume it will be waived because the delay was outside your control.
If you are offered a float-down feature, request its written conditions. A float-down is not a promise that every market improvement will produce a lower rate; eligibility, timing and fees can vary.
Maintain a realistic schedule on your side as well. Respond promptly to requests, arrange property access if an appraisal is needed and flag travel or signing constraints early.
Continue making payments on your existing mortgage as required until you receive clear payoff and payment instructions. A pending refinance does not suspend your current obligations.
Checkpoint: Know the lock expiration date, remaining approval conditions and potential extension charges before committing to the schedule.
7. Reconcile the final numbers before signing
The last cost check in a simple refinance is a side-by-side review of the final Closing Disclosure and your latest Loan Estimate. For most consumer mortgage refinances, you must receive the Closing Disclosure at least three business days before closing.
The CFPB’s Closing Disclosure explainer identifies the sections covering loan terms, payments, closing costs and cash to close. Use that review window to ask questions rather than waiting until the signing appointment.
Focus on four checks:
- Loan terms: Confirm the loan amount, rate, repayment term and any prepayment penalty or balloon payment.
- Pricing: Verify that points, lender credits and lender charges match the agreed offer or have a documented explanation.
- Closing cash: Reconcile escrow deposits, prepaid interest, payoff figures and any fees added to the loan balance.
- Payment timing: Confirm your first payment date, payoff arrangements and when any existing escrow refund is expected.
Some figures can change legitimately. A different closing date can change prepaid interest, and the mortgage payoff includes more than the principal balance shown on an older statement. Ask for an explanation of each material difference.
Verify wire instructions by calling a trusted number obtained independently, not a number supplied in a last-minute email. If instructions change unexpectedly, stop and confirm them before sending funds.
Checkpoint: Sign only when you understand the final terms, cash requirement and funding schedule. Keep copies of the closing documents and check that the old mortgage is paid off after funding.
Frequently asked questions
What makes a simple refinance worthwhile? It should meet your stated goal after transaction costs and repayment changes are considered. A lower rate alone is not enough. Your expected holding period, mortgage insurance and remaining loan balance also matter.
Is a no-closing-cost refinance actually free? Usually not. Costs may be covered through lender credits associated with a higher rate or added to the loan balance. Ask which arrangement applies and compare the cost over the period you expect to keep the mortgage.
Does restarting a 30-year term always cost more? Not necessarily, because the rate and repayment behavior also matter. However, extending the term can increase total interest despite lowering the payment. Compare alternatives that preserve your payoff timeline.
Can I cancel after signing? Many refinances secured by a principal residence have a three-business-day right to cancel after closing. Exceptions apply. Ask your lender to explain whether that right applies to your transaction and when funds will be disbursed.
Start with a clear cost comparison
Bring your current mortgage statement, savings goal and expected holding period to New Era Lending. Its personalized guidance and mortgage technology can help you evaluate available options. Request a comparison that clearly separates payment savings, transaction costs and cash needed at closing before deciding whether to proceed.