


New Mortgage Programs to Watch Before You Buy
The best new mortgage programs are not always the ones with the biggest advertised benefit. A down payment grant may come with a repayment obligation, a lender credit may affect your interest rate and a promising pilot may not cover your ZIP code. Before you build a homebuying budget around an incentive, find out what is available, what you qualify for and what the benefit actually costs.
For a 2026 purchase, focus on changes that could improve your specific situation: fresh assistance funding, closing cost support, more flexible underwriting or financing that makes a repair-needing property practical. Here are the developments worth checking before you make an offer.
What actually makes a mortgage program new?
Mortgage marketing often uses “new” to describe several different things. A program might be newly launched, an established benefit might receive another funding round or a lender might begin offering an option that has existed for years.
Those distinctions matter. Established programs generally have published rules you can review. A pilot may have limited participation, while an announced proposal may not be accepting applications at all.
When researching new mortgage programs, ask for the program’s official name, administrator and current eligibility guide. Also confirm whether applications are open and whether funds can be reserved for your expected closing date.
Separate announcements from available financing. A news story about proposed assistance is not evidence that you can use it to buy a home. Your budget should rely on a documented benefit that the administering agency and participating lender confirm is available to you.
State and local assistance with fresh funding
State housing finance agencies, cities and counties are worth checking because assistance availability can change with funding cycles. An existing program may reopen applications, expand eligible locations or adjust income and purchase-price limits.
The benefit may help with a down payment, closing costs or both. However, “assistance” does not necessarily mean a grant. Some programs provide a second mortgage that is deferred, repayable or forgivable only after you satisfy conditions.
Ask how the assistance affects your future options. Selling, refinancing, moving out or transferring ownership can trigger repayment under some programs. A benefit that works well for a long-term owner may be less useful if you expect to relocate soon.
Among new mortgage programs, a newly funded local assistance option deserves attention when it addresses your actual cash shortfall without making the monthly payment uncomfortable.
Before applying, verify income limits, eligible properties, required education and participating lenders. Confirm when funds are reserved, too. If you need a clearer explanation of grants versus second mortgages, review the ways to cover a down payment and other upfront costs before treating the advertised amount as free money.
Affordable conventional options and lender credits
Another area to watch is support attached to conventional mortgages. This can include lender-funded grants, closing cost credits or access to an established affordable lending product through a participating lender.
For example, Fannie Mae’s HomeReady mortgage is an established option that permits a down payment as low as 3% for eligible borrowers. It is not a newly created program, but changes in lender participation or an additional eligible incentive could make it newly relevant to your purchase.
Keep the mortgage and the incentive separate in your comparison. The underlying loan determines your payment, mortgage insurance and repayment obligations. The incentive determines how much help you receive and what restrictions accompany it.
When comparing new mortgage programs, ask whether a credit is an independent benefit or part of the loan’s pricing. A lender credit that reduces closing costs in exchange for a higher interest rate is different from a grant with separate eligibility rules.
Request a comparison with and without the incentive. Use the same purchase price, down payment and loan term so you can see whether the offer improves upfront affordability, ongoing costs or both. Also check whether assistance can be combined with other benefits.
Rent-history reviews and targeted homebuyer pilots
Some automated underwriting pathways can consider documented rent payment history when evaluating eligible mortgage applications. That can be relevant if you have consistently paid rent but have a limited credit history.
This is not the same as a guarantee of approval or a universal reduction in credit requirements. The lender still evaluates income, debts, credit and the property. Ask whether its underwriting process can consider your rental history, what documentation is needed and whether that approach applies to your application.
Targeted pilots may also focus on groups such as first-generation homebuyers or residents of designated communities. Their definitions deserve close attention. “First-generation” and “first-time” are not interchangeable, and each program can set its own requirements.
For borrowers overlooked by a standard product search, these new mortgage programs are worth investigating through official administrators and participating lenders rather than relying on social media summaries.
Before sharing sensitive documents, confirm the program’s identity and application channel. Find out whether participation is limited, whether funding remains available and whether a homebuyer education course must be completed before funds can be reserved.
Employer and community homebuyer benefits
Employer-assisted housing and community benefits are another category to check, particularly if you work for a large organization or are buying near your workplace. Availability depends on the employer or sponsoring organization, not simply your occupation.
Potential benefits can take the form of purchase assistance, a forgivable loan or access to a participating lending arrangement. Do not assume that every teacher, healthcare worker or public employee qualifies for a special mortgage.
Ask your benefits team for written rules covering eligible employees, property locations and required length of service. If assistance is tied to continued employment, find out what happens if you change jobs or leave the organization.
Also ask whether the benefit can be combined with your intended mortgage and other assistance. A benefit that looks attractive on its own may not fit the financing structure you plan to use.
Renovation financing for homes that need work
If move-in-ready homes stretch your budget, renovation-focused new mortgage programs or newly available lender offerings may broaden the properties you can consider. The useful change is access to suitable financing, not simply a lower listing price.
Established products such as FHA 203(k) financing can combine a purchase with eligible rehabilitation costs. Availability, project requirements and lender participation need to be confirmed before you make an offer. Not every repair, contractor or property will qualify.
Start with a realistic scope of work. Separate cosmetic preferences from safety issues, required repairs and problems that could affect the appraisal. Contractor estimates help you understand costs before you decide whether a property is affordable.
For example, buyers in Topsfield and Massachusetts’ North Shore can request a written garage door repair estimate to help price a faulty opener or damaged door. A repair quote supports budgeting, but it does not replace a home inspection or establish that the work qualifies for renovation financing.
Include inspection costs, potential temporary housing and a contingency for unexpected work in your planning. A home is not affordable merely because the purchase price is low. Confirm how repairs are approved, how contractors are paid and whether the closing timeline can accommodate the project.
How to compare new mortgage programs before you apply
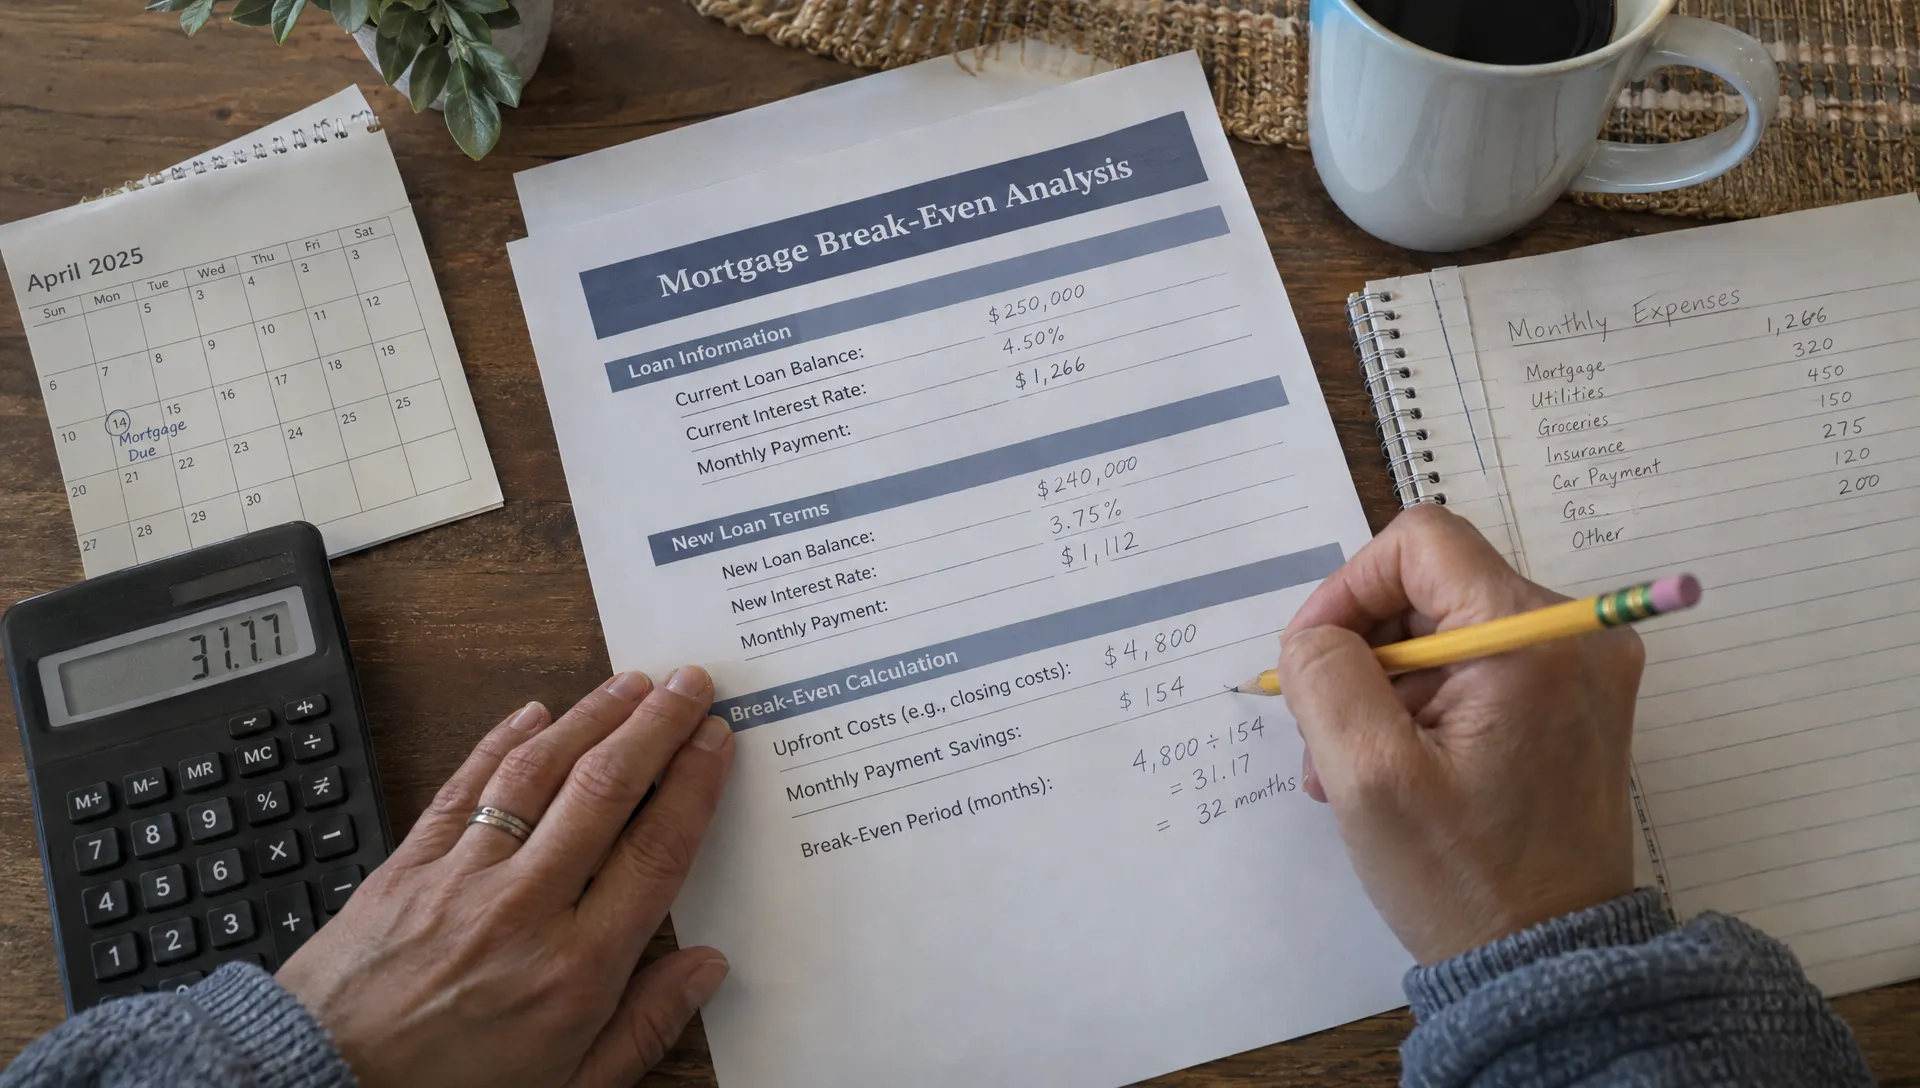
Compare each opportunity against a mortgage without the additional benefit. That baseline makes it easier to distinguish genuine savings from costs that have been shifted elsewhere.
| Comparison point | What to verify | Why it matters |
|---|---|---|
| Cash needed at closing | Down payment, fees, credits and assistance | A benefit may cover only certain expenses |
| Ongoing housing payment | Principal, interest, taxes, insurance, mortgage insurance and applicable dues | Upfront help does not guarantee a comfortable payment |
| Assistance repayment | Interest, monthly payments, forgiveness rules and repayment triggers | A second loan can create future obligations |
| Mortgage pricing | Interest rate, APR, points and lender credits | A smaller upfront bill can accompany higher borrowing costs |
| Program availability | Funding status, reservation rules and deadlines | Eligibility alone does not guarantee funding |
| Future flexibility | Conditions affecting a sale, refinance or move | Restrictions can conflict with your plans |
Once you apply, use the Consumer Financial Protection Bureau’s Loan Estimate guide to understand the standardized mortgage disclosure. Obtain separate assistance documents as well, because the main mortgage disclosure may not explain every condition attached to a grant or subordinate loan.
The strongest new mortgage programs improve a constraint you actually face, such as limited closing cash, without creating a larger problem elsewhere. For a closer look at pricing trade-offs, learn how to compare mortgage offers beyond the headline rate.
Turn your shortlist into a financing plan
Bring your lender two scenarios: the purchase with the benefit and the purchase without it. Ask for estimated cash to close, the full monthly housing payment and any separate assistance obligations under each scenario.
Then check the timeline. Education courses, income reviews, funding reservations and renovation approvals can add steps. Before agreeing to a closing date, ask which approvals remain outstanding and who is responsible for each one.
Keep an emergency reserve in the comparison. Using assistance to preserve savings can be valuable, but a program should not encourage you to spend every available dollar on the transaction.
Finally, get confirmation of the benefit before relying on it in an offer. A general preapproval is not necessarily confirmation that a particular grant, pilot or employer benefit has been approved or reserved for you. Clarify both the mortgage decision and the assistance decision.
Frequently asked questions
Are new mortgage programs only for first-time buyers? No. Some target first-time or first-generation buyers, while others depend on income, location, employment or property type. Check the program’s definition rather than assuming that previous homeownership automatically disqualifies you.
Does down payment assistance always have to be repaid? No. Some assistance is a grant, while other support is a repayable, deferred or conditionally forgivable loan. Request the written agreement and identify what happens when you sell, refinance or stop occupying the home.
Can I combine more than one homebuyer benefit? Sometimes, but each program and the underlying mortgage must permit the combination. Your lender also needs to confirm how the funds are documented and applied. Do not add advertised benefits together before checking compatibility.
Should I delay buying while waiting for a new program? An announced benefit may have uncertain timing, limited funding or requirements you do not meet. Base your plan on financing available to you now. Revisit it if a confirmed program materially improves affordability without pushing you beyond a comfortable budget.
Get guidance before committing to an incentive
New Era Lending combines smart mortgage tools with personalized human guidance to help buyers evaluate their financing options. Share your purchase location, budget, expected timeline and any assistance you are considering.
Start a conversation with New Era Lending to discuss which options may fit your situation and what needs to be verified before you make an offer.