


New Home Finance: A Checklist Before You Make an Offer

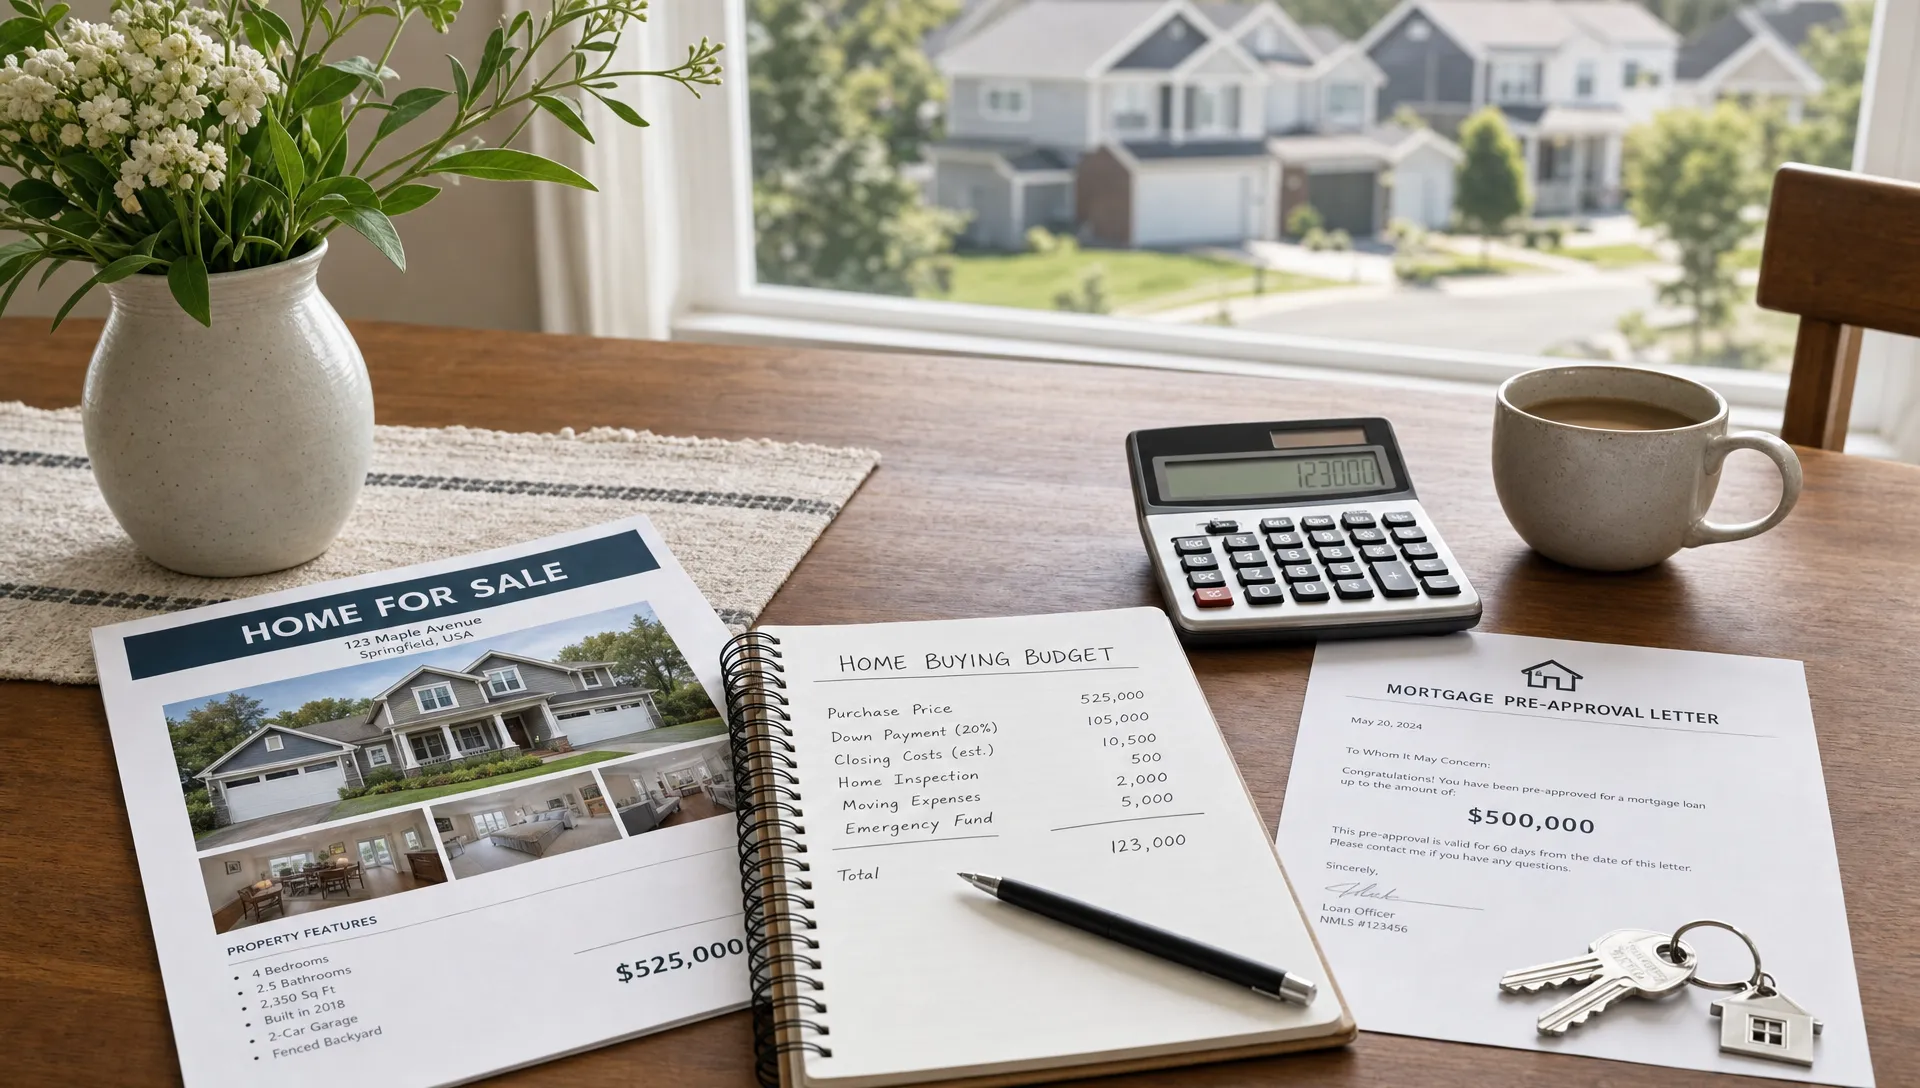
Your new home finance checklist should do more than confirm that a lender will consider your application. Before you make an offer, you need to know what this particular property will cost each month, how much cash it will require and which contract terms could leave you exposed.
A preapproval helps, but it does not settle the property’s insurance cost, appraisal value or eligibility for your loan. Use the checks below to turn a listing price into an offer you can support without draining the savings you will need after closing.
1. Calculate the payment for the actual property
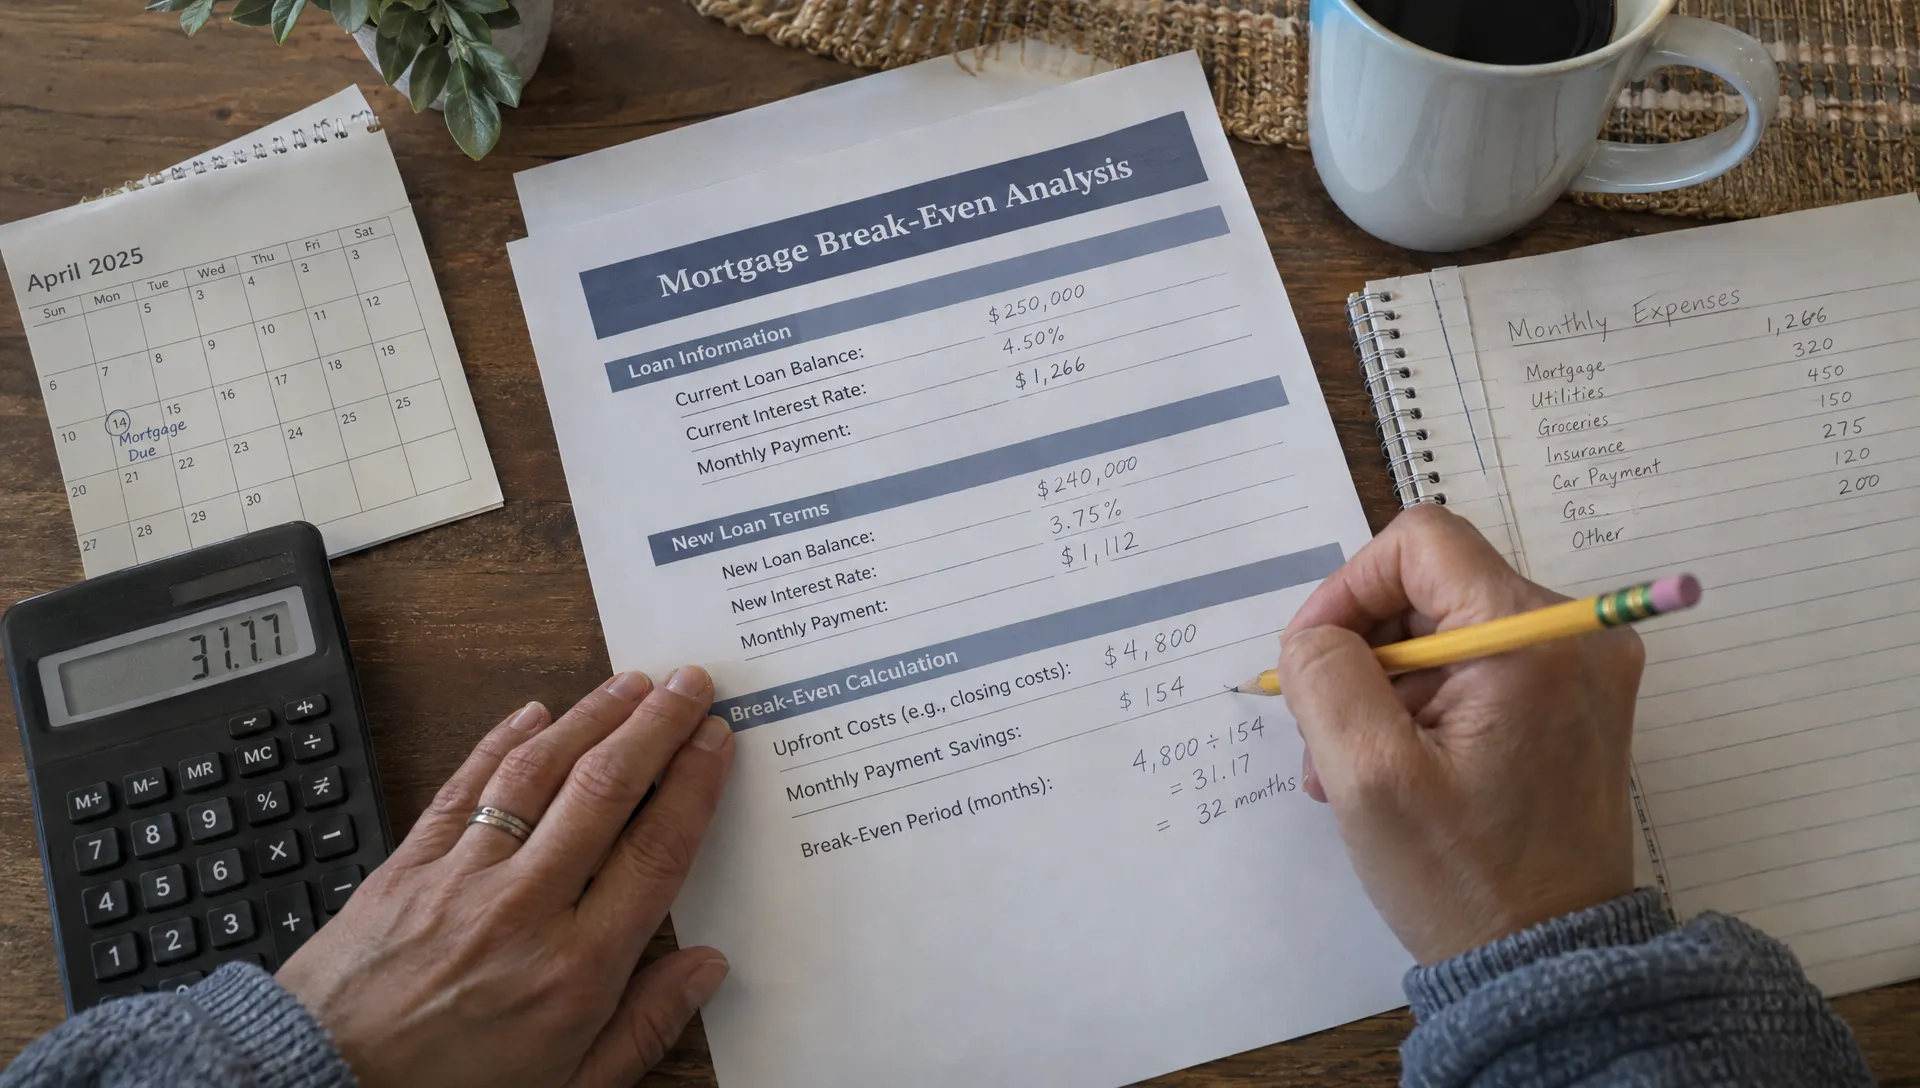
Start with a comfortable monthly housing budget, then test the listing against it. The principal-and-interest figure on a mortgage calculator is only part of the cost.
Request estimates for property taxes, homeowners insurance, any required flood insurance, mortgage insurance and homeowners association dues. Budget separately for utilities and maintenance, even if those expenses are not part of the lender’s qualifying calculation.
For example, consider this illustrative budget, not a rate quote:
| Monthly expense | Hypothetical amount |
|---|---|
| Principal and interest on a $360,000 mortgage at 6.5% over 30 years | $2,275 |
| Property taxes | $450 |
| Homeowners insurance | $180 |
| Mortgage insurance | $150 |
| HOA dues | $100 |
| Total before utilities and maintenance | $3,155 |
Actual costs depend on the borrower, property, loan program and location. A lower advertised mortgage payment may exclude several of these items.
Your new home finance budget should use the property’s likely ongoing costs, not simply copy the seller’s current tax bill. A sale, reassessment or expired exemption can change taxes. For new construction, an initial bill may reflect land rather than the completed home.
Before offering: Get a property-specific payment estimate and an insurance quote. If either is unavailable, leave room in your budget rather than assuming the lowest possible cost.
2. Verify exactly what your preapproval means
Preapproval processes vary. A letter based mainly on information you supplied is not the same as a file with verified income, assets and credit or one that has received an underwriting review.
Ask your lender these questions before relying on the letter:
- Which documents have you reviewed, and what conditions remain?
- Does this approval cover the property type I want to buy?
- When does the letter expire, and what would require an update?
- Can you support the proposed financing and closing deadlines?
Also confirm the assumptions behind the approval: purchase price, down payment, loan program, estimated taxes, insurance and HOA dues. An approval calculated for a house without association fees may not transfer neatly to a condominium with substantial monthly dues.
The lender’s debt-to-income ratio measures qualifying debt payments against qualifying gross income. Your personal budget must go further by accounting for groceries, childcare, retirement contributions and other spending that may not appear in that calculation.
For new home finance decisions, treat the approved maximum as a borrowing limit, not a spending recommendation. Ask for an updated review if your income, employment, debts or available cash have changed.
Before offering: Make sure the letter supports your intended offer and that your agent understands any unresolved financing conditions. Preapproval is not a final commitment to lend.
3. Reconcile the cash you need and when you need it
Separate cash requirements into three stages: money due shortly after acceptance, money due at closing and money you intend to keep afterward.
An earnest money deposit usually becomes a credit toward your closing obligations rather than an additional purchase expense. However, it may be due well before closing, and whether you can recover it depends on the contract and your compliance with its terms.
Inspection fees and other upfront expenses may also be payable before your mortgage closes. At closing, you may owe the remaining down payment, lender and third-party charges, prepaid interest and initial escrow deposits.
Your new home finance cash plan should show both the total amount and the source of each dollar. Ask how gift funds, investment sales, retirement-account withdrawals or proceeds from another home must be documented before relying on them.
The Consumer Financial Protection Bureau’s Loan Estimate explainer shows where to review projected payments, closing costs and estimated cash to close. Lenders generally must provide this form within three business days after receiving a mortgage application. A preliminary worksheet is not the same document.
For a closer look at the individual charges, review the closing costs buyers often overlook.
Before offering: Keep a separate emergency reserve. Ask which costs are already paid, which are credits and which remain due so you do not count the same expense twice.
4. Confirm that the loan structure fits your cash position
You do not always need 20% down, but a smaller down payment can change your monthly payment, mortgage insurance and total borrowing cost.
These are general program possibilities, not a statement that every borrower or property qualifies:
| Loan category | Potential down payment starting point | What to investigate |
|---|---|---|
| Certain conventional programs | 3% | Borrower eligibility, mortgage insurance and program restrictions |
| FHA | 3.5% for eligible borrowers | Credit requirements, upfront and annual mortgage insurance |
| VA | No down payment for eligible borrowers in qualifying circumstances | Entitlement, property requirements and any funding fee |
| USDA | No down payment for eligible borrowers and properties | Income limits, location eligibility and program fees |
The VA explains eligibility and other conditions for its purchase loan benefit. A zero-down option does not necessarily eliminate closing costs or other cash requirements.
Compare loan structures using the same property, purchase price and timing assumptions. Ask how a larger down payment changes both your payment and the cash you retain.
A workable new home finance plan balances monthly affordability with liquidity after closing. Using every available dollar to reduce the loan can leave you unprepared for repairs or an income interruption.
Before offering: Verify assistance-program eligibility, funding availability and timing if your purchase depends on that support. Do not treat an unapproved grant or anticipated seller credit as confirmed cash.
5. Check whether the property creates financing problems
A borrower can qualify while the chosen property does not. Before making an offer, tell your lender whether the home is a condominium, manufactured home, multiunit property, investment purchase or newly built house. Each can introduce different requirements.
Ask your agent about visible condition concerns, outstanding permits, association issues and known special assessments. For a condominium, lender review may extend beyond the unit to the project’s finances, insurance and other characteristics.
Insurance deserves early attention. Get a quote for the address, disclose known property details accurately and ask about deductibles, exclusions and coverage availability. Do not assume the seller’s policy or premium will be available to you.
The property review is part of new home finance preparation because required repairs, insurance costs or project eligibility can change whether the deal works. An appraisal also does not replace a home inspection.
Separate required repairs from optional improvements. For example, San Diego buyers considering garage floor coatings from Bay City Coatings can request a written quote and place that elective project in a post-closing improvement budget. Do not assume a standard purchase mortgage will provide extra funds for cosmetic work.
For new construction, ask whether the quoted price includes the lot, selected finishes and all contracted upgrades. Confirm whether you are financing a completed home or need construction financing.
Before offering: Identify issues that need lender review now, rather than discovering them after paying for inspections and appraisal work.

6. Put a dollar limit on your offer’s risks
The offer price is only one financial term. Earnest money, seller credits, contingency deadlines, appraisal provisions and closing dates can all change your exposure.
A financing contingency may provide a contractual path to cancel if financing cannot be obtained under its terms. An appraisal contingency addresses a different issue: what happens if the appraised value does not support the agreed price. The wording, deadlines and required notices matter.
Suppose you offer $400,000 and the appraisal comes in at $380,000. The lender generally bases its loan-to-value calculation on the lower of the purchase price or appraised value. Your additional cash need depends on the loan structure and any renegotiation; it is not automatically resolved by having a preapproval.
Before agreeing to appraisal-gap coverage, ask the lender to calculate your cash requirement at a lower value. Set a firm dollar cap that preserves your minimum savings balance.
A competitive new home finance strategy should not depend on waiving protections you cannot afford to lose. Review contingency changes with your agent and, where appropriate, a local real estate attorney.
Seller concessions also have limits and program-specific rules. They generally cannot replace a required down payment, and credits beyond allowable costs may not benefit you.
Before offering: Confirm which deadlines you can meet, what could put your deposit at risk and how much additional cash you could contribute without borrowing unexpectedly.
7. Complete your new home finance sign-off
Before authorizing an offer, put the key assumptions in writing. You do not need final figures for every expense, but you should know which numbers are verified, which are estimates and what happens if they change.
| Final checkpoint | What you should have |
|---|---|
| Monthly affordability | Property-specific payment estimate plus a maintenance allowance |
| Available cash | Documented funds for upfront expenses, closing and retained savings |
| Financing readiness | Current preapproval and a clear list of remaining conditions |
| Property suitability | Early lender feedback on property type and known concerns |
| Contract exposure | Understood contingency deadlines and a defined appraisal-gap limit |
| Timing | A closing schedule your lender says is realistic |
Tell your lender before opening new credit, financing furniture, changing jobs or moving substantial funds. These actions can affect qualification or create documentation requirements while the loan is being reviewed.
Once your offer is accepted, the mortgage process from offer to closing introduces additional steps, including appraisal, title review and final underwriting. An accepted offer starts that work; it does not mean financing is complete.
Frequently asked questions
How much down payment do I need before making an offer? It depends on the loan program, borrower eligibility and property. Some qualifying loans allow low or no down payment, but you may still need closing funds, upfront expenses and reserves. A new home finance plan should identify all required cash, not just the down payment.
What salary do you need for a $400,000 mortgage? There is no universal salary requirement. Qualification depends on the interest rate, loan term, taxes, insurance, other debts and program rules. Ask a lender to calculate the full payment and qualifying income, then test that payment against your actual household spending.
Should I lock my mortgage rate before making an offer? Ask what your lender permits and what any lock requires. Availability, fees, expiration dates and extension costs vary. A quoted rate is not necessarily locked, and a lock that expires before closing can create additional costs.
Can I rely on a builder’s financing incentive? Compare the complete written offer with another financing option. Check the purchase price, loan costs, interest rate, incentive conditions and whether any payment reduction is temporary. Confirm what happens if construction delays push closing beyond a rate-lock period.
Review the numbers before you commit
Bring the listing address, proposed offer price, available funds and preferred closing date to your lender before signing. Flag any appraisal-gap promise, requested seller credit or unusual property condition.
New Era Lending combines mortgage technology with personalized human guidance. Request a property-specific financing review so you can distinguish what is confirmed from what still needs approval before your offer becomes a contract.