


Borrowing Money on Your Home: Safe Ways to Access Equity
If you’re considering borrowing money on your home, start with one fact: accessing equity creates debt secured by your property. A home equity loan, home equity line of credit (HELOC) or cash-out refinance can provide useful funding, but none removes the risk of foreclosure if you cannot repay.
The safer approach is to match the loan to a specific expense, compare its full cost and review the protections available before signing. Your approval amount is only one part of that decision. Payment stability, closing costs and the terms of your existing mortgage can matter just as much.
Compare the three main ways to access equity
Home equity is your home’s current market value minus the debt secured by it. Borrowing against that equity does not mean withdrawing money you have saved in an account. You are taking out a new loan or replacing an existing one.
These are the main structures to compare:
| Option | How you receive money | What happens to your existing mortgage | Main issue to check |
|---|---|---|---|
| Home equity loan | Usually a lump sum | Generally stays in place | Fixed payment, repayment term and upfront costs |
| HELOC | Draw funds as needed during a draw period | Generally stays in place | Variable rates, payment changes and draw restrictions |
| Cash-out refinance | Cash from a larger replacement mortgage, after paying existing debt and costs | Replaced by a new mortgage | Cost of refinancing the entire mortgage balance |
When borrowing money on your home, choose the repayment structure before focusing on the advertised rate. A home equity loan often has a fixed rate and predictable payments. A HELOC generally has a variable rate, though some offer fixed-rate features.
A cash-out refinance deserves particular scrutiny if your current mortgage has favorable terms. You are not simply pricing the extra cash: you are also changing the financing on the balance you already owe. A second mortgage may preserve your first mortgage, but it adds another payment.
Estimate usable equity, not just total equity
Lenders generally will not let you borrow every dollar of equity. They evaluate the property’s value, existing liens and the maximum loan-to-value ratio permitted by the program.
For loans that remain alongside your mortgage, combined loan-to-value (CLTV) measures all relevant secured debt against the home’s value. With a HELOC, the lender may count the full credit limit, not just the amount initially drawn.
Consider this hypothetical example:
- Your home is valued at $500,000.
- Your current mortgage balance is $300,000.
- A lender’s assumed maximum CLTV is 80%.
- Total permitted secured debt would be $400,000, leaving $100,000 before fees and other adjustments.
That 80% limit is an illustration, not a universal lending rule. Actual limits depend on the lender, loan type, occupancy and borrower qualifications.
For borrowing money on your home, the more useful number is often the net amount available after costs, rather than the headline loan amount. Ask whether fees will reduce your proceeds, be paid separately or increase your balance.
Then set your own borrowing limit. New Era Lending’s guide to accessing equity without overborrowing explains why a defined expense should drive the amount requested.
Test the payment when circumstances are less favorable
A manageable first payment does not guarantee a manageable loan. Review what happens over the full repayment period, especially when the initial payment is temporary.
A HELOC may allow interest-only payments during its draw period. Those payments do not reduce principal, and the payment can increase when repayment begins. Variable interest rates can also change what you owe each month. Some agreements may require a large final payment, so check the maturity terms.
Before borrowing money on your home, ask the lender to show payments under several realistic conditions. For example, request a HELOC payment estimate at a rate two percentage points higher than the starting rate. This is a stress test, not a rate forecast.
For any loan, calculate the combined cost of your mortgage, new debt, property taxes, homeowners insurance and association dues. Test that total against a temporary income reduction or a major repair bill.
Keep emergency savings separate from the borrowing plan. Depending entirely on an unused HELOC for emergencies can leave you exposed because lenders may freeze or reduce access under circumstances allowed by the agreement.
What can prevent you from borrowing money on your home?
Having equity does not guarantee approval. Lenders also need evidence that you can repay, and their requirements differ by product and program.
Common obstacles include insufficient usable equity, recent missed payments, high debt obligations relative to income or income that cannot be adequately documented. Credit history matters, but there is no single credit-score cutoff that applies to every lender and equity product.
The property can create obstacles too. An appraisal below your estimate reduces available equity. Unresolved liens, title problems, property-condition concerns or an ineligible property type can delay or prevent approval. An investment property may also face different requirements from a primary residence.
Prepare accurate income records, mortgage statements, insurance information and details of other debts. Self-employed applicants may need additional documentation to establish qualifying income.
If an application is declined, review the lender’s adverse action notice rather than assuming the problem is only your score. Ask what specifically affected the decision and whether correcting an error or resolving a title issue could change the outcome. Avoid paying anyone who promises guaranteed approval or a guaranteed credit-score increase.
Compare total costs, not just rates
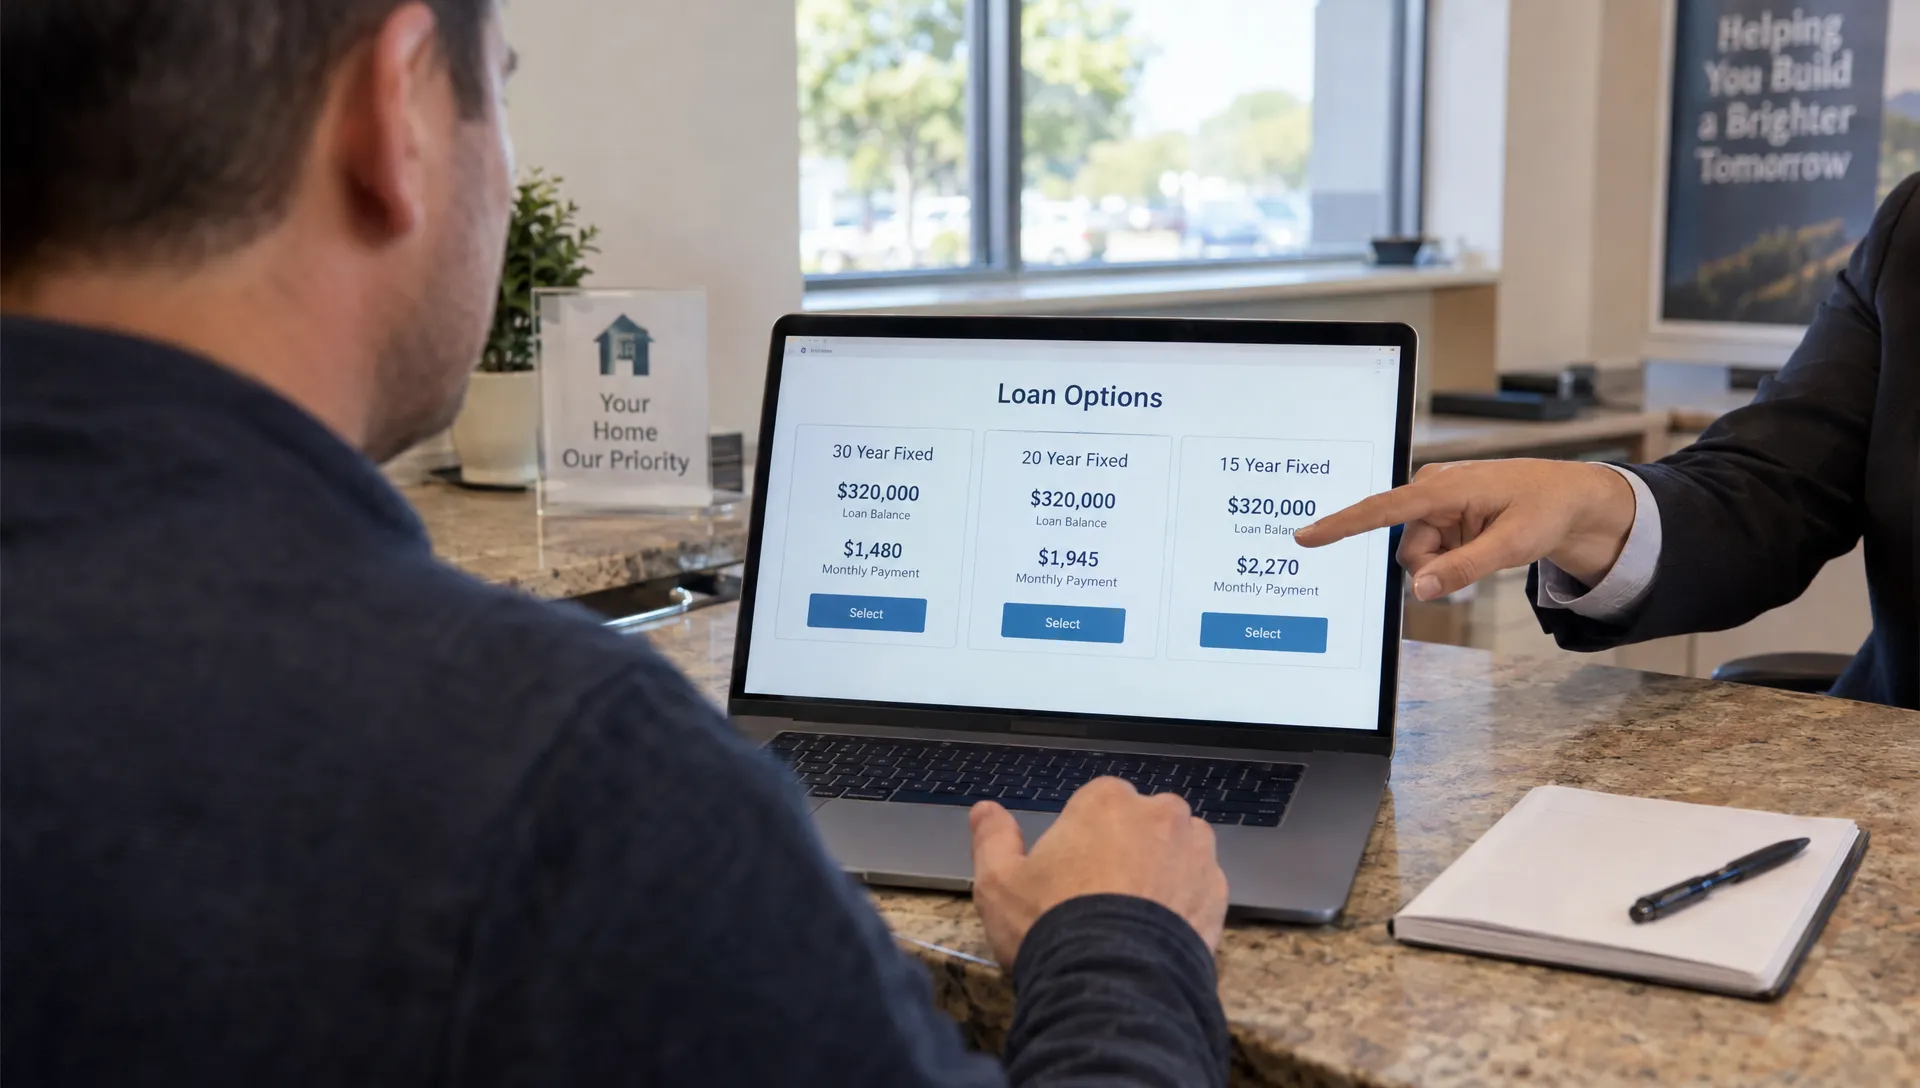
Request quotes for the same amount and repayment term whenever possible. Otherwise, a lower payment may simply reflect more years of interest.
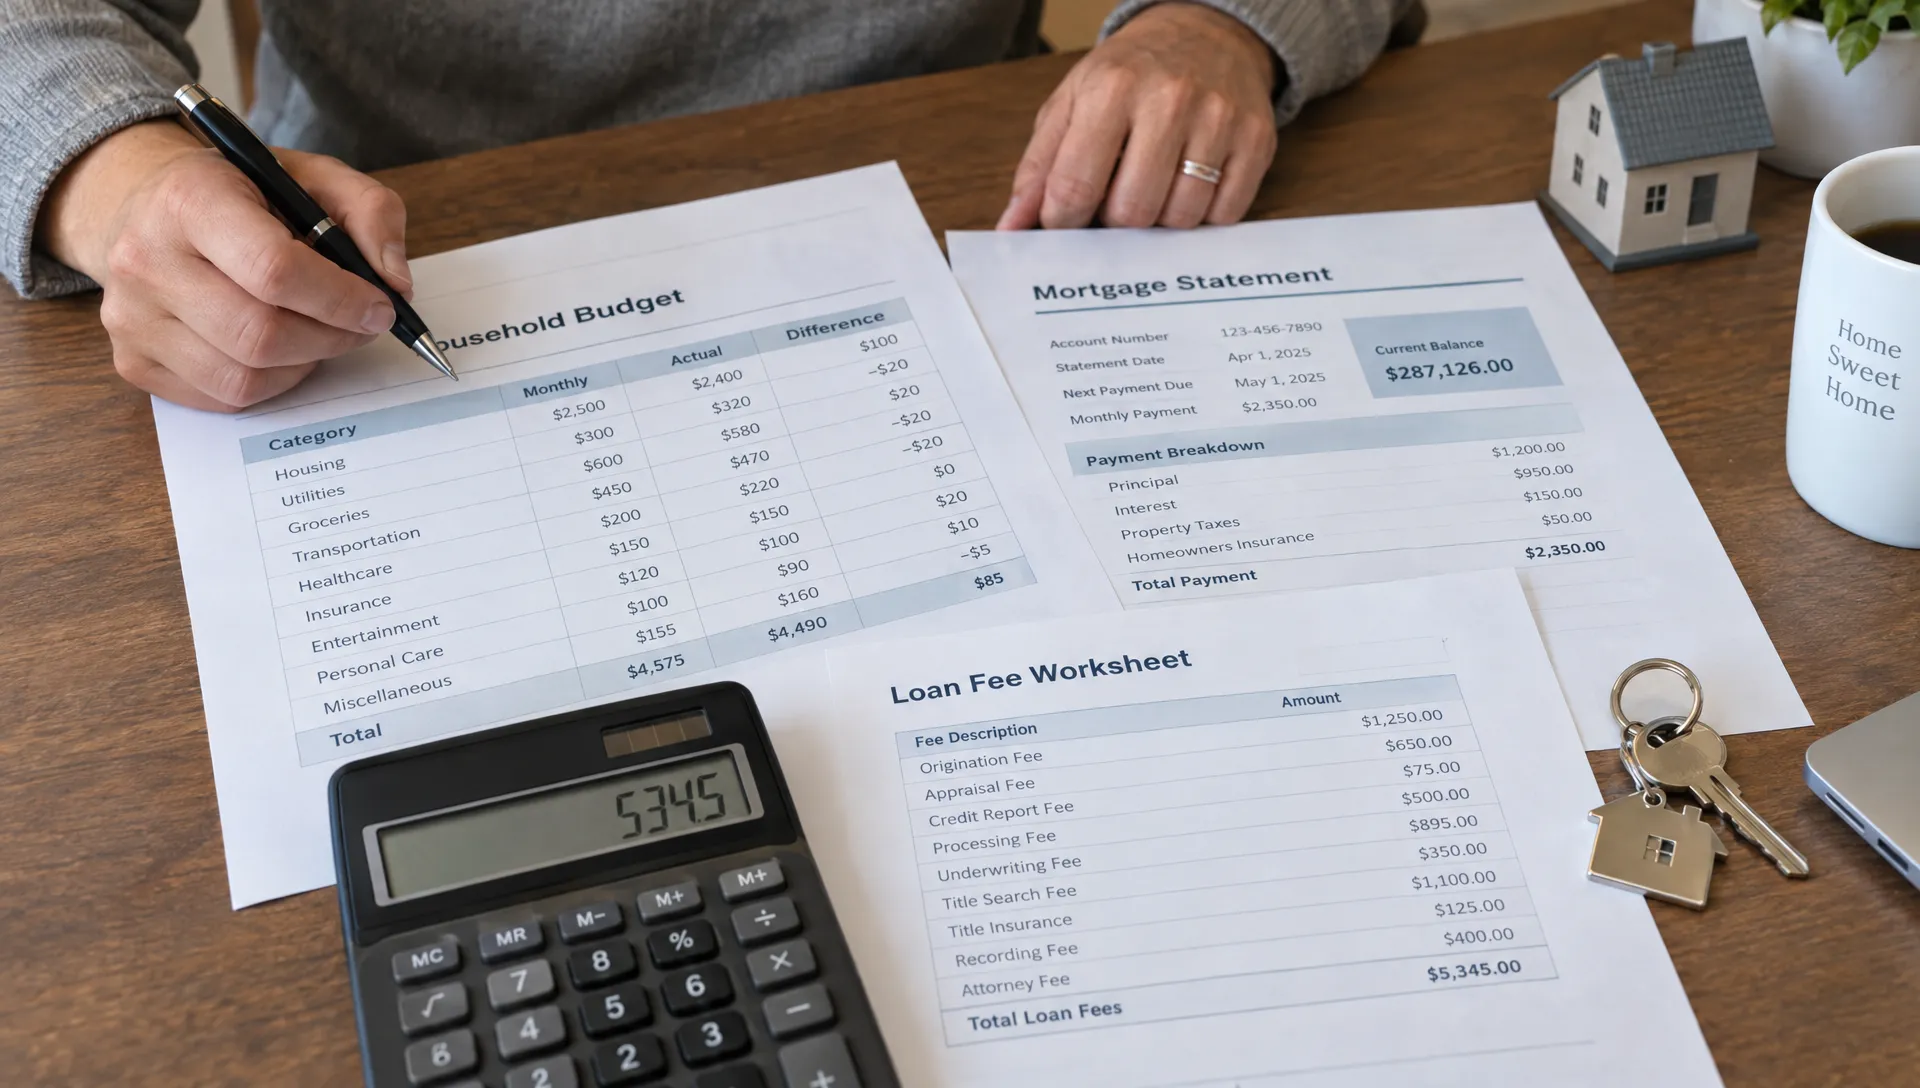
The cost of borrowing money on your home can include origination charges, appraisal fees, title work and recording charges. HELOCs may also carry annual fees, minimum-draw requirements or early-closure charges. Not every lender charges every fee, so request an itemized breakdown.
Understand what the APR includes
For a closed-end home equity loan or cash-out refinance, the annual percentage rate (APR) incorporates interest and certain financing charges. It helps with comparisons, but you should still review cash needed at closing and total payments.
A HELOC’s disclosed APR generally does not capture fees in the same way as a closed-end loan’s APR. A lower HELOC APR therefore does not automatically mean a cheaper borrowing arrangement.
Scrutinize “no closing cost” offers
An offer without upfront closing costs may involve a higher rate, costs added to the balance or lender-paid charges subject to repayment if you close the account early. Ask how the offer is funded.
For a refinance, also compare the new mortgage with keeping your existing loan and adding separate financing. Calculate costs over the period you expect to keep the loan, not merely the first month.
Review disclosures and cancellation rights before signing
Ask which disclosure rules apply to your transaction. Closed-end mortgage loans and open-end HELOCs do not use identical paperwork.
For most covered closed-end mortgage applications, lenders must provide a Loan Estimate within three business days after receiving an application. A covered loan’s Closing Disclosure generally must reach you at least three business days before closing. HELOCs use separate open-end disclosures.
The paperwork for borrowing money on your home should explain the rate, payment structure, fees and obligations. Compare final terms with earlier estimates and ask about changes before signing. Pay particular attention to adjustable-rate provisions, balloon payments, prepayment penalties and any obligation to repay waived fees.
Know whether you can cancel
Many nonpurchase loans secured by a principal residence have a federal right of rescission, generally lasting three business days. The timing depends on when the transaction is completed and required notices and disclosures are delivered.
The federal rescission rules for covered closed-end loans include exceptions, including certain refinancings with the same creditor. HELOCs have related but separate rules. Purchase mortgages generally do not receive this cancellation right.
Ask whether your transaction qualifies, when the deadline falls and how to deliver a valid cancellation notice. Do not assume you can reverse the loan after the deadline, and do not let anyone rush you through the explanation.
Consider alternatives before using your house as collateral
The expense itself should influence the financing decision. Borrowing money on your home for a necessary repair is different from using long-term secured debt for a short-lived discretionary purchase.
For smaller expenses, compare saving longer, reducing the project scope or using an affordable unsecured personal loan. An unsecured loan may carry a higher rate, but it does not place a direct mortgage lien on your house. Compare actual offers, fees and repayment periods rather than assuming one category is cheaper.
For wedding expenses, you may encounter event-specific offers such as Raphana Jewellery’s wedding loan page. This New Zealand retailer’s page should not be treated as a U.S. financing offer; verify local eligibility, collateral requirements and total costs separately.
Debt consolidation also requires caution. Paying off credit cards with home-secured debt changes the collateral risk, and running up the cards again can leave you owing both balances.
Verify the lender and protect the closing process
Check the company and loan originator through official licensing resources, such as NMLS Consumer Access and your state regulator. Licensing is a basic verification step, not a guarantee that an offer suits your needs.
A safer process for borrowing money on your home also includes protecting your documents and payment instructions. Use the lender’s verified secure upload system rather than sending sensitive records to an unfamiliar email address.
Treat last-minute changes to wiring instructions as a warning. Confirm any transfer instructions by calling a trusted number obtained independently, not the number in a suspicious message.
Walk away from requests to misstate income, conceal debts or sign blank forms. Be equally cautious if someone discourages you from comparing offers or cannot clearly explain the payment terms. Review the broader risks of borrowing against your home before committing your property as collateral.
Frequently asked questions
Can I borrow against a house that is paid off? Yes, some lenders offer home equity loans, HELOCs or mortgage financing on a property without an existing mortgage. You still need to meet income, credit, property and other underwriting requirements. The new loan creates a lien on the home.
Is borrowing money on your home a good idea? It can be reasonable when the expense is justified, repayment is affordable and the financing compares favorably with alternatives. It is harder to justify when it funds recurring budget shortfalls, speculative investments or discretionary spending you cannot otherwise afford.
Will I lose my existing mortgage rate? A home equity loan or HELOC generally leaves the existing first mortgage in place. A cash-out refinance replaces it, so the new rate and terms apply to the replacement balance. Review both the new payment and total financing cost.
Can I sell my home before the equity loan is paid off? Usually, but loans secured by the property generally must be paid off at closing from sale proceeds or other funds. Your remaining proceeds will depend on the sale price, selling costs and all outstanding secured balances.
Discuss your options before committing
Ask New Era Lending which equity-access options are available for your property and state. Request a clear explanation of net proceeds, total costs, payment changes and how each choice affects your current mortgage. Personalized guidance should help you evaluate the trade-offs, not simply borrow the largest amount available.